

Cisco Systems CSCO shares have dropped 6.7% in the past three trading sessions after the company reported first-quarter fiscal 2027 results on Nov. 12. Shares fell 6.2% in the Nov. 13 trading session, despite CSCO reporting record revenues and earnings and raising its fiscal 2027 guidance. The primary concerns were declining gross margins, higher component costs, slowing product-order growth and uncertainty surrounding the sustainability of AI-driven demand. However, does the dip offer an opportunity to take a position in CSCO shares? Let’s find out.
Cisco Suffers From Margin Pressure, Moderating Order Growth
Investor concerns around margin pressure and the quality of forward growth despite very strong top-line results have been plaguing Cisco shares. In the first quarter of fiscal 2027, non-GAAP gross margin contracted 250 basis points (bps) year over year to 65.6%, while non-GAAP product gross margin declined 350 bps to 63.7%. The contraction primarily reflected a higher mix of hardware revenues, particularly AI networking infrastructure and elevated memory costs. Cisco’s growing exposure to relatively lower-margin hardware raised concerns regarding its ability to sustain profitability as AI infrastructure revenues accelerate.
Cisco increased its fiscal 2027 hyperscaler AI infrastructure revenue forecast to $9 billion from $7.5 billion. However, the rapid expansion of this hardware-intensive business is expected to weigh on product margins. Moreover, moderating product order growth is a concern. Although total product orders increased 21% year over year in the reported quarter, growth slowed from 35% in the fourth quarter of fiscal 2026. This raised concerns that Cisco’s near-term demand momentum might be moderating following a period of significant expansion. The company faces tougher year-over-year comparisons, particularly in campus networking, and is also expected to suffer from uneven spending patterns of hyperscale customers.
Cisco now expects second-quarter fiscal 2027 revenues between $18 billion and $18.2 billion, implying a sequential decline from the reported $18.52 billion. Non-GAAP earnings per share are expected between $1.34 and $1.36, below the fiscal first quarter’s reported figure of $1.40 per share. Although the company raised its fiscal 2027 outlook, the sequential moderation in revenue and earnings raised concerns regarding the near-term growth trajectory.
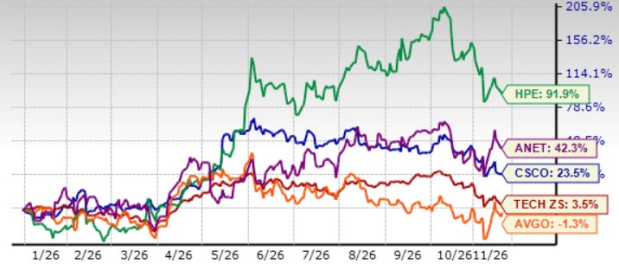
Year to date (YTD), Cisco shares have returned 23.5%, outperforming the broader Zacks Computer & Technology sector’s appreciation of 3.5%. Cisco has underperformed peers, including Hewlett Packard Enterprise HPE and Arista Networks ANET, but outperformed Broadcom AVGO over the same time frame. Shares of Hewlett Packard Enterprise and Arista Networks have appreciated 91.9% and 42.3% YTD, respectively, while Broadcom has dropped 1.3%.
CSCO's Price Performance
Image Source: Zacks Investment Research
Strong AI Infrastructure Demand Aids Cisco’s Prospects
Cisco is benefiting from accelerating investments in AI infrastructure as hyperscalers expand their data center networking capabilities. The company secured three new AI infrastructure design wins in the fiscal first quarter, bringing the total to 18 over the past five quarters. CSCO’s Silicon One P200, G200 and G300 networking platforms, alongside Acacia coherent optics, are strengthening the company’s competitive position in high-bandwidth AI connectivity. The growing design-win pipeline provides additional revenue opportunities extending into fiscal 2028 and beyond.
Cisco is witnessing stronger demand for AI networking infrastructure from enterprises, neocloud providers and sovereign cloud operators. First-quarter orders for Nexus data center switches associated with AI deployments increased 47% year over year. The company’s collaboration with NVIDIA and Supermicro to expand Secure AI Factory offerings is strengthening CSCO’s ability to deliver integrated AI infrastructure. The deployment of AMD GPU-based infrastructure using Cisco Silicon One systems for HUMAIN in Saudi Arabia highlights opportunities in sovereign AI projects. Increasing adoption of hybrid and private AI infrastructure should provide incremental growth opportunities.
Cisco’s expanding campus networking portfolio also represents a significant growth opportunity. First-quarter campus networking orders increased 14% year over year, supported by growing adoption of next-generation switching, routing and wireless products. Wireless orders increased more than 20%, while Wi-Fi 7 accounted for more than 60% of access-point orders. With next-generation products representing less than 10% of campus switching orders, Cisco has substantial room for further adoption. The company estimates a network refresh opportunity exceeding $100 billion, supported by enterprise modernization and increasing bandwidth requirements.
Fiscal 2027 Earnings Estimate Revisions Positive for CSCO
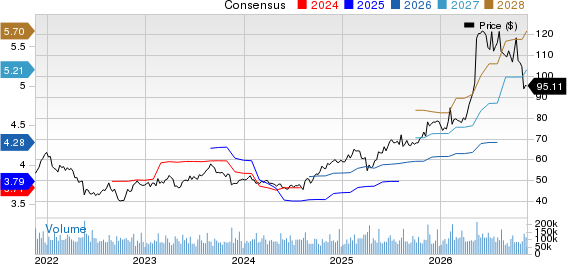
The Zacks Consensus Estimate for CSCO’s fiscal 2027 earnings is currently pegged at $5.21 per share, up by a nickel over the past 30 days, indicating year-over-year growth of 20.3%. Fiscal 2027 revenues are pegged at $74.60 billion, indicating 17.8% growth over fiscal 2026’s reported figure.
Cisco Systems, Inc. Price and Consensus
Cisco Systems, Inc. price-consensus-chart | Cisco Systems, Inc. Quote
The consensus mark for CSCO’s second-quarter fiscal 2027 earnings is currently pegged at $1.25 per share, up by a penny over the past 30 days, indicating year-over-year growth of 20.2%. Quarterly revenues are pegged at $18.13 billion, indicating 18.1% year-over-year growth.
CSCO Shares Are Trading at a Premium
Cisco shares are trading at a premium, as suggested by the Value Score of D.
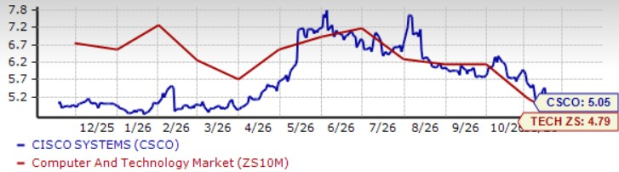
In terms of the forward 12-month price/sales, CSCO is trading at a premium of 5.05X, higher than the broader sector’s 4.79X and Hewlett Packard Enterprise’s 1.11X.
However, Cisco shares are trading at a discount compared with Arista Networks and Broadcom. In terms of the forward 12-month P/S, Arista Networks and Broadcom shares are trading at 13.19X and 9.09X, respectively.
CSCO Stock’s Valuation
Image Source: Zacks Investment Research
Conclusion
Cisco’s recent share-price decline offers an attractive entry point for long-term investors, supported by strong AI infrastructure demand, expanding hyperscaler relationships and a multi-year campus networking refresh cycle. Growing adoption of Silicon One, Acacia optics and integrated AI networking solutions, alongside positive earnings estimate revisions, strengthens its growth prospects. Although margin pressure, elevated component costs and premium valuation remain concerns, Cisco’s expanding AI opportunities and improving earnings outlook justify a bullish stance on CSCO shares.
CSCO currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Discover the Stocks Our Experts Want to Own This Quarter
Each quarter, four Zacks editors compile their favorite stocks into one report. As a sign of the times, three of this quarter's picks can potentially cash in on the massive AI boom. One grew its commercial revenue more than 140% last quarter.
The fourth stock is an online retailer posting its most significant growth since the pandemic. Its shares jumped more than 25% after its last earnings report, then pulled back, giving investors a chance to capitalize on what could be a longer-term bullish trend.
Get Your Free Ultimate Four Report >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Cisco Systems, Inc. (CSCO): Free Stock Analysis Report
Broadcom Inc. (AVGO): Free Stock Analysis Report
Arista Networks, Inc. (ANET): Free Stock Analysis Report
Hewlett Packard Enterprise Company (HPE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).