

Micron Technology (MU) reported earnings in what management called one of the most severe memory shortages the industry has seen. AI data centers need more DRAM and HBM chips, and supply has struggled to keep up. Wall Street expected adjusted earnings of $31.72 per share on $51.49 billion in revenue, compared with earnings of $2.86 per share a year earlier.
Micron beat both estimates. After the close on Sept. 30, the company reported adjusted earnings of $33.42 per share and revenue of $54.23 billion, up about 379% from $11.32 billion a year ago. It was the seventh straight quarter of triple-digit earnings growth, while gross margin reached about 86%. MU shares had entered the report trading at more than three times their price at the start of 2026, giving the company a market value above $1.2 trillion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Still, shares rose just 1.7% after hours, well short of the 6.3% move options traders had expected. Earnings beat forecasts, and guidance came in higher than expected, so why didn’t the stock move more? And is MU still worth buying here? Let’s find out.
Where Micron Beat Expectations
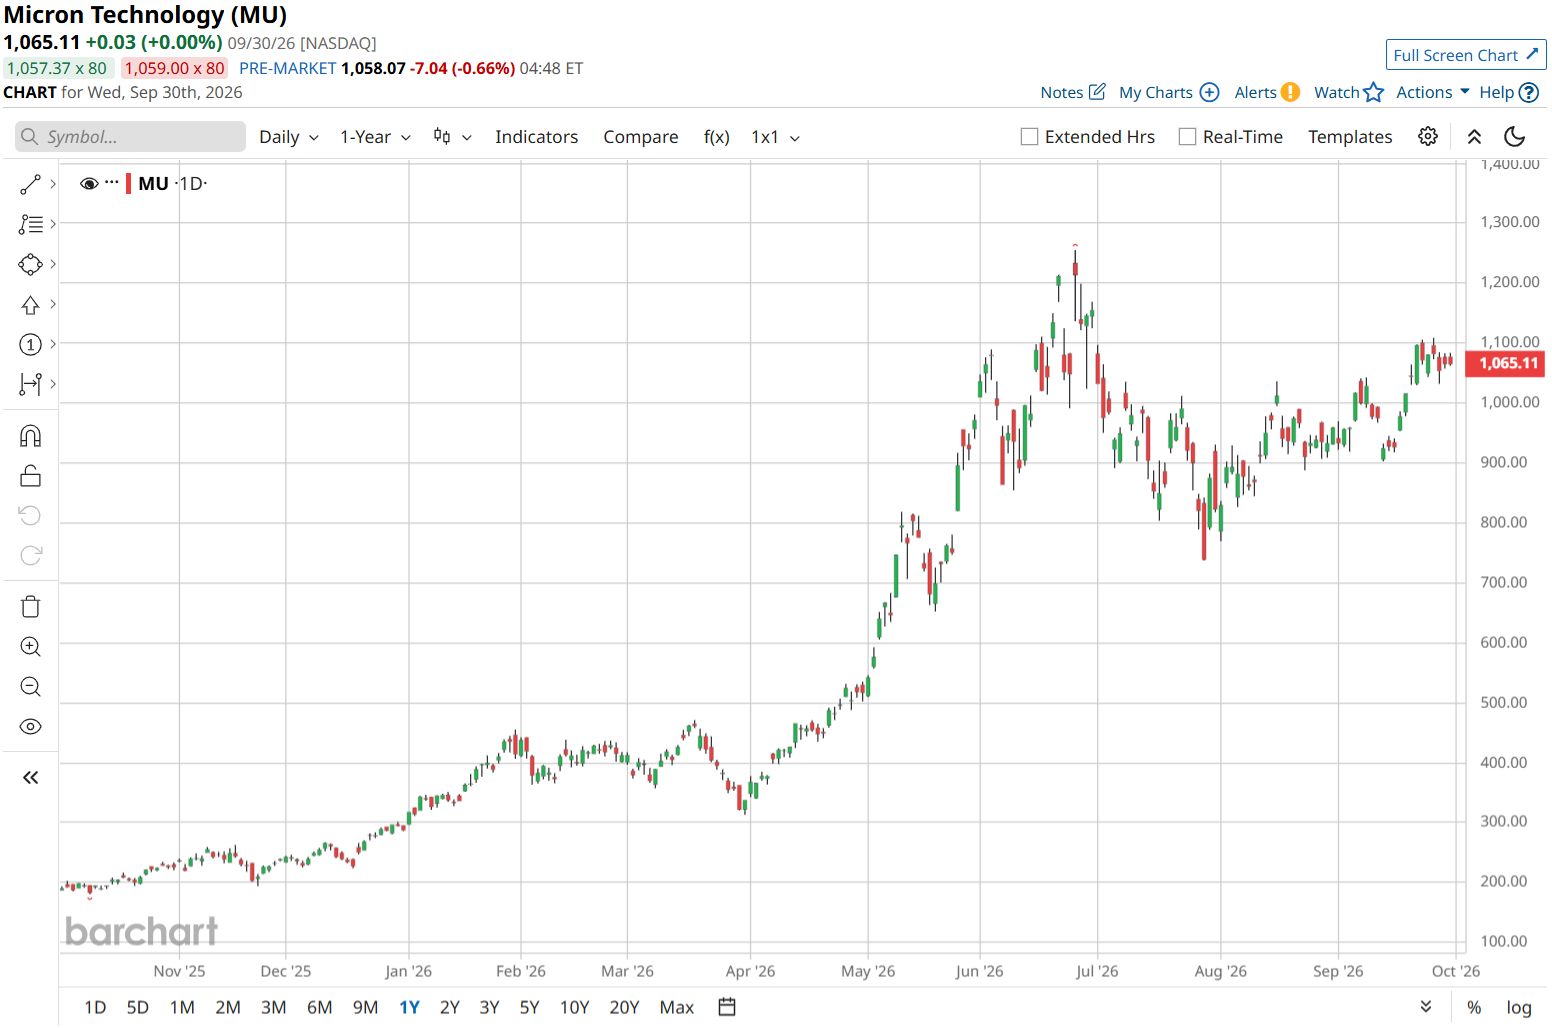
Micron Technology makes memory and storage chips used in data centers, phones, and cars. Its stock is up 536.57% over the past 52 weeks and 273.19% year to date.
 www.barchart.com
Even after that climb, MU trades at 6.63x forward earnings, compared with 23.30x for the technology sector.
The dividend adds a little income, but it is not the main reason to own the stock. Micron declared a quarterly payment of $0.15 per share, payable Oct. 29. Its quoted yield is about 0.05%, well below the technology sector’s 1.37% average. The forward payout ratio is 1.10%, the company pays quarterly, and it has only raised its dividend once.
The latest results help explain the rally. Fiscal fourth-quarter revenue rose to $54.23 billion from $41.46 billion the previous quarter and $11.32 billion a year earlier. GAAP net income was $37.70 billion, or $32.87 per diluted share. On a non-GAAP basis, it earned $38.40 billion, or $33.42 per share. Operating cash flow reached $43.97 billion.
For fiscal 2026, revenue was $133.19 billion, up from $37.38 billion in fiscal 2025. GAAP net income totaled $84.97 billion, or $74.33 per share, while non-GAAP net income reached $86.76 billion, or $75.52 per share. Annual operating cash flow was $89.68 billion. Even after net capital spending of $10.77 billion in the quarter and $27.37 billion for the year, adjusted free cash flow reached $33.20 billion and $62.31 billion, respectively. Micron Technology ended the year with $73.48 billion in cash and investments. For the first quarter of fiscal 2027, it expects about $61.5 billion in revenue, gross margin near 86%, and non-GAAP earnings of about $38.15 per share.
What Could Keep Growth Going
Micron now has 26 long-term customer agreements, up from the 16 cited in the earlier draft. They include take-or-pay commitments, meaning customers agree to buy a minimum amount of memory even if market conditions change. Micron puts the minimum value of orders covered by agreements with set pricing terms at about $150 billion. Customers have also made roughly $32 billion in financial commitments, mostly cash deposits. Management expects the deals to account for more than 35% of revenue through 2030, giving it a clearer view of demand as it plans production.
The company is building closer ties with AI customers, too. In June, Micron Technology announced an agreement with Anthropic, the company behind Claude. The two will work on memory and storage for AI systems, and Anthropic has agreed to buy from Micron Technology’s data-center product range. The deal also includes an investment in Anthropic.
Cars offer another source of demand. Micron Technology has signed agreements with Qualcomm (QCOM), Visteon (VC), HARMAN, JOYNEXT, DENSO, Astemo, and Hyundai Mobis to supply memory and storage for future vehicles. As cars add more connected and AI-powered features, they need more of both. These agreements give the suppliers more certainty about access to chips and give Micron Technology a better view of what they will need next.
What Analysts See Ahead for MU
Analysts expect Micron Technology to keep growing. Their average earnings estimate for the quarter ending November 2026 is $34.83 per share, compared with $4.61 a year earlier, a 655.53% increase. For fiscal 2027, they expect $160.39 per share, up from $74.85 in fiscal 2026.
Some analysts were bullish even before the latest results. Citi analyst Atif Malik raised his price target to $1,300 from $1,150 and kept a Buy rating, citing strong AI-memory demand and tight supply. His forecasts of $51 billion in fourth-quarter revenue and $31.45 in adjusted earnings per share were above Wall Street’s estimates at the time. Micron Technology went on to beat both of his forecasts.
Baird analyst Tristan Gerra also kept his Outperform rating and raised his target to $1,520. He believes strong memory demand and Micron Technology’s AI-related products could support further gains, despite the stock’s big run in 2026.
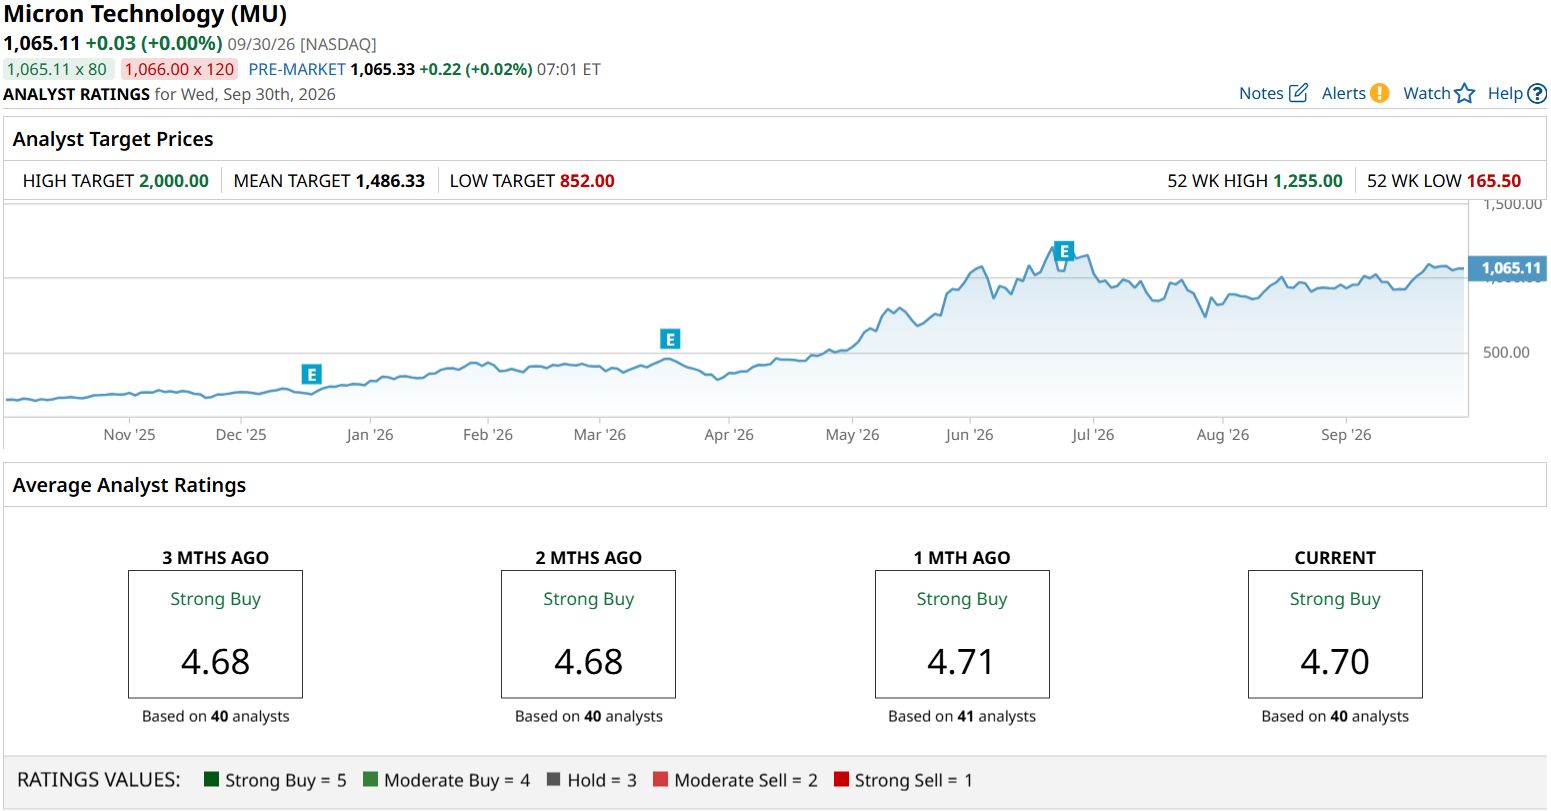
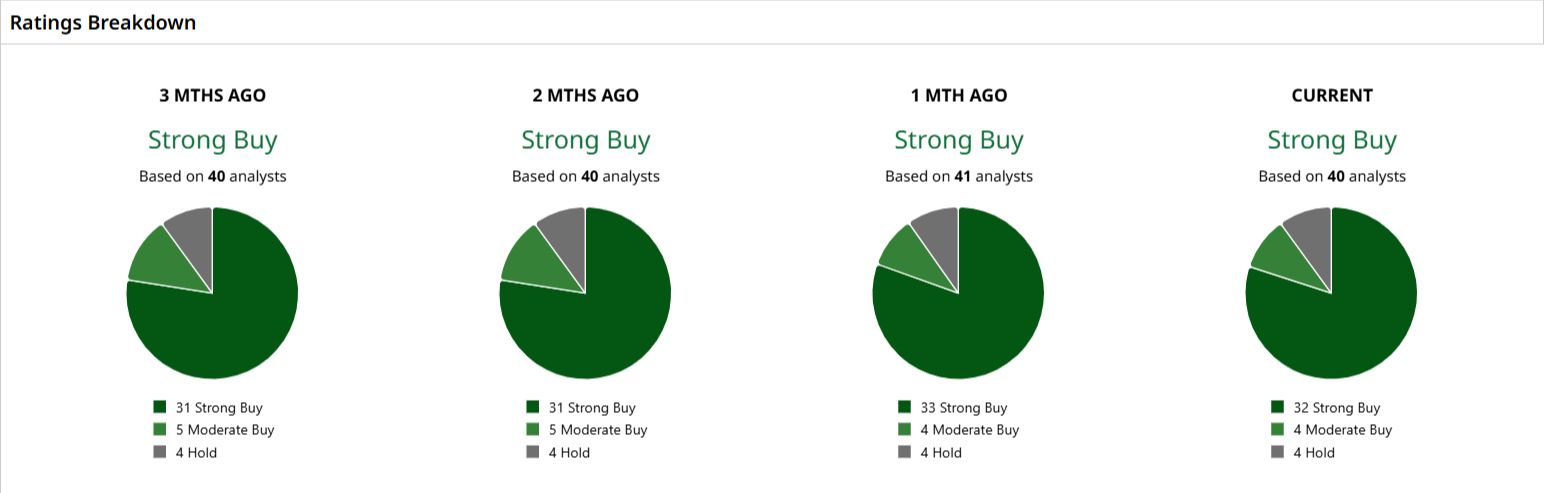
Overall, MU has a consensus “Strong Buy” rating from 40 analysts. Its average price target of $1,486.33 suggests about 39.5% upside from recent price levels.
 www.barchart.com
Conclusion
Micron just delivered another blowout quarter and raised the bar for the next one, so the question is less about whether the story is real and more about how to position around it. With multi-year take-or-pay contracts locking in demand, an AI partnership that deepens its role beyond commodity chips, and fresh automotive wins, the growth runway looks intact. Shares most likely keep climbing from here as the memory shortage and AI buildout play out, though the easy triple-digit gains are behind us. The practical play is to stay long or add on any pullbacks rather than chase every tick higher.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Commercializing AI Agents Will Help Okta Accelerate Its Growth Micron Beat on Earnings and Guided Above Estimates. How Investors Should Play MU Stock Here. Workday Plans to Cut 2.5% of Its Workforce and Revise Its Margin Outlook. How Investors Should View the Move. Chevron Stock May Attract Value Investors, Especially If It Hikes the Dividend Next Year