

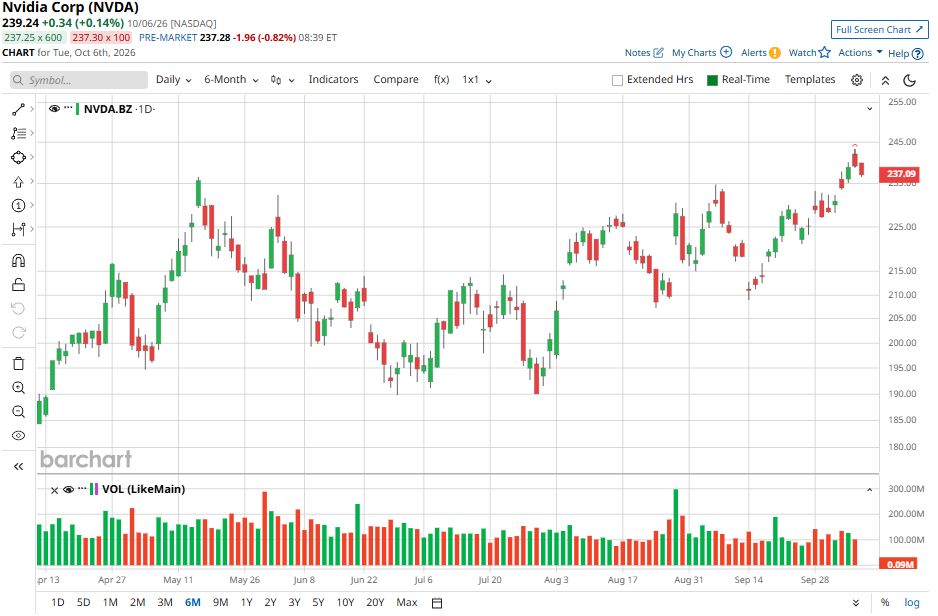
Nvidia (NVDA) stock has climbed more than 28% in 2026, but that performance pales in comparison with Advanced Micro Devices (AMD) and Intel (INTC), both of which have surged by more than 200% year-to-date. Despite lagging its peers, Nvidia still has a strong growth outlook, supported by several potential catalysts that could drive the stock significantly higher.
Nvidia is at the heart of the artificial intelligence (AI) revolution. Its GPUs, CPUs, networking hardware, and comprehensive AI platforms are helping businesses build and deploy next-generation AI applications. With demand for AI infrastructure showing no indication of slowing, Nvidia is positioned for substantial earnings growth in the years ahead.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
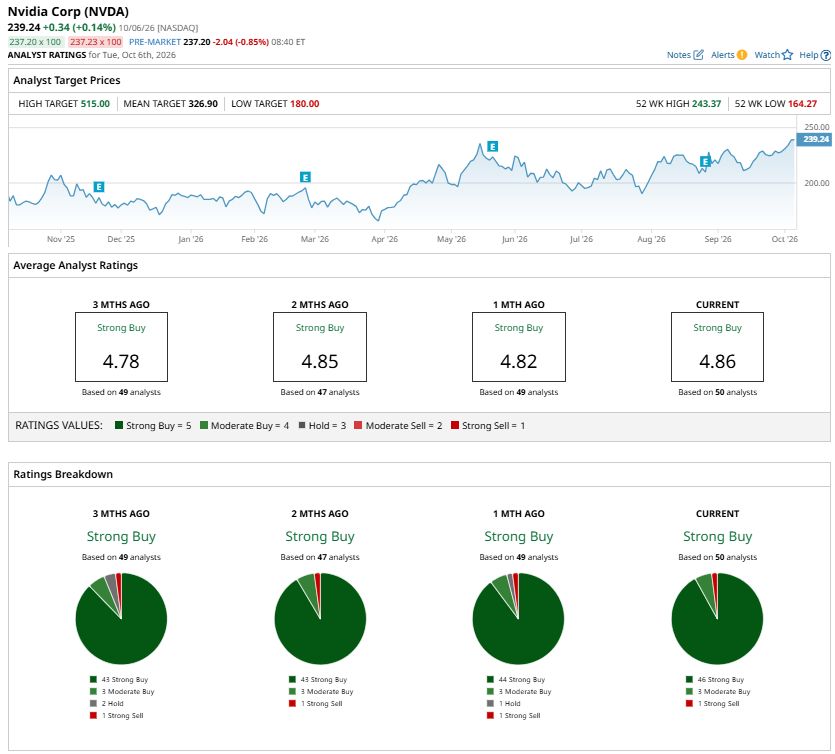
At the same time, Nvidia’s current valuation appears attractive relative to its growth prospects. That combination could give the stock room to move beyond Wall Street’s average 12-month price target of $326.90. Based on its Oct. 6 closing price of $239.24, reaching that target would represent about 37% upside. Here’s a closer look at why Nvidia could have further to run.
 www.barchart.com
Nvidia Still Has Plenty of Room to Grow
Nvidia has delivered extraordinary growth over the past few quarters, which naturally makes future year-over-year comparisons more difficult. Still, the rapid expansion of AI infrastructure suggests the company has plenty of room to keep growing. Demand is coming from a much broader customer base than just the major cloud providers, including AI startups, enterprises, AI labs, and governments developing their own sovereign AI infrastructure.
Nvidia’s recent results highlight just how strong that demand remains. Revenue increased 85% year over year in the first quarter of fiscal 2027 and then jumped 106% to $96.2 billion in the second quarter. For the third quarter, Nvidia expects revenue of about $108 billion. Even if it reaches that target, revenue would still be more than 89% higher than a year earlier. Given strong demand across its customer base, Nvidia could easily beat its own forecast.
The data center business will likely remain the company’s biggest growth driver, particularly as customers continue moving to Nvidia’s Blackwell architecture. Further, Nvidia offers a complete AI computing platform that combines hardware, networking, and software, allowing it to benefit from spending across the broader AI infrastructure market. The rollout of systems based on its next-generation Vera Rubin architecture could provide another boost.
Importantly, Nvidia’s opportunity extends beyond hyperscalers. Sovereign AI projects, regional NeoCloud providers, enterprises, and specialized data centers are increasingly investing in AI infrastructure. Nvidia expects these non-hyperscaler businesses to account for roughly half of its data center revenue eventually. The rapidly growing ecosystem of AI-native startups running on Nvidia’s platform adds another growth avenue.
Nvidia also has substantial potential in CPUs. As agentic AI applications become more sophisticated, they will require greater computing capacity. Its Grace CPU business has already generated more than $5 billion in trailing 12-month revenue, while Nvidia estimates the total server CPU opportunity at roughly $20 billion in fiscal 2027. The company expects CPU revenue to more than double in fiscal 2028, while its next-generation Vera CPU as a standalone product could expand its total addressable market further.
This growth should translate into stronger earnings. Analysts expect Nvidia’s earnings to more than double in fiscal 2027 and increase by roughly 68% in fiscal 2028. If AI infrastructure demand remains strong, Nvidia has a reasonable opportunity to outperform those expectations.
Nvidia Stock to Touch $327
Strong demand for AI infrastructure, expanding opportunities beyond hyperscalers, and robust earnings growth provide Nvidia with multiple catalysts for further upside. Although the stock’s 28% gain in 2026 trails AMD and Intel, Nvidia’s valuation appears more attractive.
Nvidia currently trades at 25.3 times forward earnings, well below AMD’s forward P/E of 98.6 and Intel’s 114.6. This represents a substantial valuation discount despite Nvidia’s leadership in AI infrastructure.
With analysts setting the average 12-month price target at $326.90, Nvidia appears well positioned to reach and surpass $327. Continued earnings growth, strong AI demand, and a comparatively attractive valuation could provide the catalysts needed to drive the stock higher. Most analysts have a “Strong Buy” rating for NVDA stock.
 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Nvidia Stock Is Worth Buying Before It Touches $327 Dear JPMorgan Stock Fans, Mark Your Calendars for Oct. 13 How to Play Rubrik Stock at New All-Time Highs Snowflake Stock Has Wall Street Raising Its Price Targets Again. Here’s Why.