

Lam Research (LRCX) is stepping onto the earnings stage after the market closes on Oct. 21, and the mood heading into the report is unlike most. Just weeks ago, Lam Research Chief Financial Officer Doug Bettinger spent two days on two different conference stages. He noted that customers want more tools than the company can ship, and there are no signs of a slowdown.
Now, it's time for analysts and investors to find out how Lam performed for the first quarter of fiscal 2027. Let's take a closer look.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
Why the AI Buildout Runs Through Lam
Lam Research sells etch and deposition equipment used by semiconductor companies to build advanced chips. That puts the company right next to the artificial intelligence (AI) boom as the industry spends on wafer fab equipment (WFE).
CFO Doug Bettinger noted at the Citi Global TMT Conference on Sept. 9 that Lam raised its 2026 WFE estimates from $135 billion to $140 billion, then to the low $150 billion range. Bettinger also said the share of WFE spending Lam can address is now “probably north of 36%,” up from the low 30% range and ahead of the pace the company laid out at its last Investor Day.
The reason is chip design. Newer chips, called gate-all-around, are built in 3D. Making them takes more etching, which carves material away, and more deposition, which adds thin layers. Those are the two things where Lam enjoys a competitive moat.
“Gate-all-around is more etch and deposition intensive. It's got selective etch requirements. It's got ALD requirements,” Bettinger said. “Those are things we do and things we do really well.”
Bettinger said every 100,000 wafer starts of that capacity adds $1 billion to Lam's addressable market. Backside power adds another $1 billion for the same capacity.
A Sold-Out Industry With a Space Problem
At the Goldman Sachs Communacopia + Technology Conference on Sept. 10, Bettinger was blunt. The industry, he said, is "sold out."
Bettinger noted that Lam’s biggest customers, which he calls Tier 1, have eight to 10 new clean rooms coming online between now and the end of 2027. Those customers would not build the clean rooms if they did not plan to equip them.
Lam does not want to be the bottleneck in the supply chain. The company is speeding up its second facility in Malaysia, getting more output from the space it already has, and hiring and training new staff. “Necessity is the mother of invention,” Bettinger told the Citi audience on Sept. 9.
Lam Research Vice President of Investor Relations Ram Ganesh added another clue. The company has said that $100 billion of AI data-center spending turns into roughly $8 billion of WFE, but Ganesh believes that figure has since moved $1 billion to $2 billion higher.
In the last quarter, Lam posted a 52% gross margin — its highest in 20 years — and guided 52% for Q1 fiscal 2027. Bettinger said the company now sees a path to the mid-50% range over several years. He credited new products, building closer to customers, and pricing as key reasons for the margin outlook.
Lam's Customer Support Business Group (CSBG) also just posted its third-straight record quarter at nearly $2.5 billion. Bettinger said industry utilization is “basically at 100%,” which keeps spare parts moving.
What Does Wall Street Expect on Oct. 21?
So, what do analysts expect Lam Research to post for the September quarter? Based on Yahoo Finance data, analysts estimate revenue of $8.14 billion on average, with a range between roughy $7.9 billion and $8.4 billion. A year ago, revenue came in at $5.32 billion, so that implies year-over-year (YOY) growth of 53% at the midpoint.
In terms of EPS, analysts expect earnings of $2.18 per share for the quarter, up from $1.26 a year ago. Finally, they foresee revenue of $8.54 billion and EPS of $2.32 for the December quarter as well.
For the full year, analysts expect fiscal 2027 revenue of $34.95 billion, up 50% YOY, with EPS of $9.49. For 2028, the revenue forecast stands at $42.11 billion while the EPS estimate is $11.94.
Similarly, using Barchart data, analysts expect EPS of $2.17 for the current quarter, up 72% YOY, and EPS of $9.35 for fiscal 2027, up 61% YOY. For fiscal 2028, EPS is expected to rise 22% YOY to $11.43.
Lam Research beat EPS estimates in each of the last four quarters. Last quarter, the company earned $1.82 against an estimate of $1.69 per share, a beat of roughly 8%.
Why Guidance Matters More Than the Beat
I expect Lam Research to deliver in fiscal Q1. Bettinger's tone and rising estimates both point that way. The bigger question is: What will Lam Research say about the road ahead?
Once earnings are reported, analysts will first want to compare the December outlook provided by management against the $8.54 billion estimate. Then, they should look to gross margin to see whether it holds near 52%. Finally, any update on Lam's Aether dry resist program will be important. Bettinger noted at the Citi conference that he is confident this business will beat its estimated $1.5 billion revenue opportunity, although China growth may prove slower for the company.
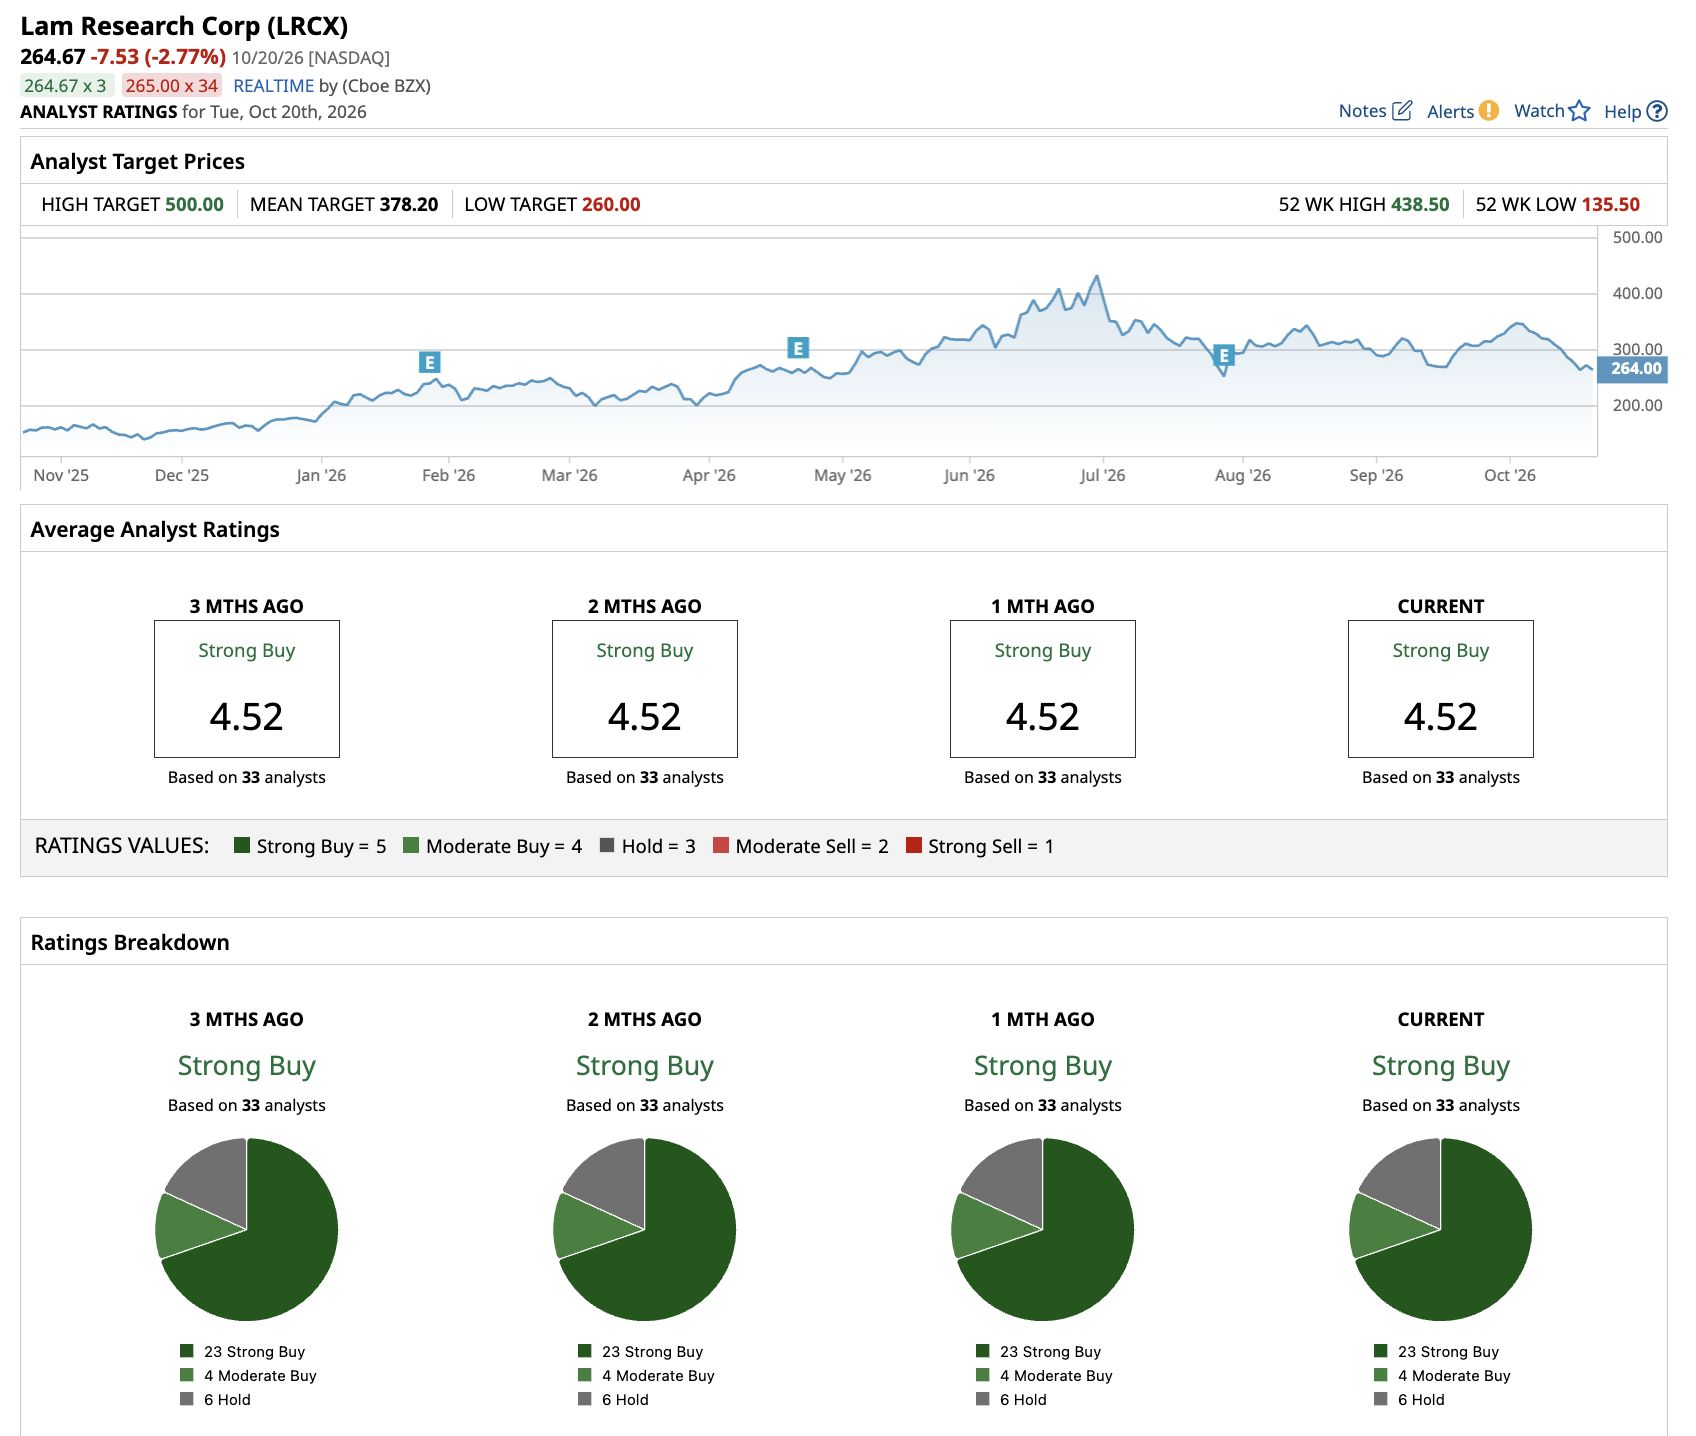
Overall, based on 33 analysts with coverage, LRCX stock has a consensus “Strong Buy” rating on Wall Street. Out of those analysts, 23 recommend a “Strong Buy” rating, four have a “Moderate Buy,” and six recommend a “Hold” rating. The average price target of $378.30 represents potential upside of 41% from current levels.
 www.barchart.com
On the date of publication, Aditya Raghunath did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.