

Cisco Systems (CSCO), which sells cloud and network gear (with an increasing proportion of sales from software), reported strong quarterly FCF growth and margins on Nov. 12, with higher FY guidance. But CSCO fell over 6%. Is it too cheap now?
CSCO closed at $95.64 on Friday, Nov. 13, down 6.24% and off its recent peak of $118.39 on Oct. 9. However, it's still above a pre-market trough of $95.72 on Nov. 5.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
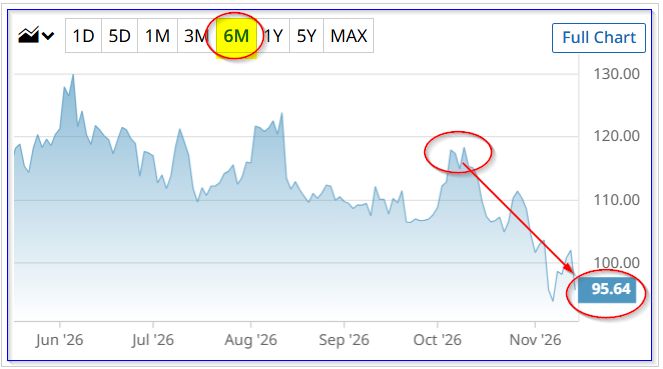 CSCO - last 6 months - Barchart - Nov. 13, 2026
It seems the whole Nvidia (NVDA) drama may have pulled this excellent company down with it. NVDA hit another 6-month low on Friday.
After all, analysts are now very positive on Cisco's prospects. For example, Yahoo! Finance shows that 28 analysts have an average price target (PT) of $134 (+40% higher). Moreover, Barchart's mean survey PT is $132.79, and AnaChart's survey of 16 analysts who've written recently about Cisco is $128.11.
These higher PTs show that analysts are all very bullish on CSCO. Its strong financial performance shows why.
Strong Revenue, FCF, FCF Margins, and Guidance
Cisco Systems had a stellar quarter (fiscal Q1 ending Oct. 24, 2026) with higher-than-expected revenue growth and free cash flow soaring 33% YoY.
For example, last quarter management projected FY 27 Q1 revenue to range from $18.0 billion to $18.2 billion, but it came in at $18.5 billion.
Moreover, management raised its FY 2027 revenue guidance (ending July 2027) from $72.2 billion to $73.4 billion, to $74.8 billion to $75.8 billion.
In addition, Cisco's FCF as a percent of revenue rose from 19.41% last Q1 to 20.82%, according to data from Stock Analysis. Moreover, since an increasing portion of revenue is now coming from software and subscriptions (up to 39%), its trailing 12-month (TTM) FCF margins are more important and rising.
For example, over the past year, FCF represented 20.51% of revenue, up from 20.1% last quarter. However, last year, it was 22%, although revenue was 33% lower.
The bottom line is that, based on higher revenue guidance, FCF is forecast to rise.
FCF Prospects and Valuation
For example, analysts now project that FY 27 (ending July 31, 2027) will be $74.74 billion, and the following year it will rise to $80.65 billion. So, using 3/4ths of the '27 forecast and ¼ of the next year, the next 12-month (NTM) revenue forecast is $76.22 billion.
So, assuming it makes at least 21% of revenue in FCF, its FCF could hit $16.0 billion.
As a result, using a 3.9% FCF yield metric (its average FCF yield over the last year), Cisco could be worth $410 billion (i.e., $16b / 0.039).
That's +8.7% higher than its present market cap of $377.1 billion. That implies a PT of $104 per share.
However, many tech stocks in the cloud and AI arena have a 3.0% to 3.5% FCF yield.
So, using a 3.33% FCF yield, CSCO would be worth $480.5 billion, (i.e., $16b /0.0333), or $100 billion more than its present stock price (i.e., +27.4% higher). That implies a PT of $121.84 per share.
Conclusion
Cisco is moving away from its heavy reliance on switching and network hardware, towards SaaS and software maintenance contracts. But the market is still skeptical. Nevertheless, FCF performance is improving.
As a result, CSCO could be worth anywhere from 8.7% to 27.4% more, but a lot will depend on higher revenue and maintaining high FCF margins.
Given that the stock has a high beta with other tech stocks like Nvidia (NVDA), it might make sense to wait until the loss-selling is over.
On the other hand, CSCO still looks like a good, long-term buy-in at today's price.
On the date of publication, Mark R. Hake, CFA did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Cisco Systems Had a Stellar Quarter, But CSCO Tumbled - Is It Too Cheap Here? Down 62% From All-Time Highs, Here’s How to Play CRWV Stock as CoreWeave Smashes Q3 Estimates Demand for the Anthropic IPO Far Outpaces Available Shares. Be Careful in an Early Scramble for Stock. Option Volatility and Earnings Report For Nov 16-20