

Atlanta, Georgia-based PulteGroup, Inc. (PHM) engages in the homebuilding business. Valued at $23.4 billion by market cap, the company sells and constructs homes, and purchases, develops, and sells residential land and develops active adult communities. PHM also provides mortgage financing, title insurance, and other services to home buyers.
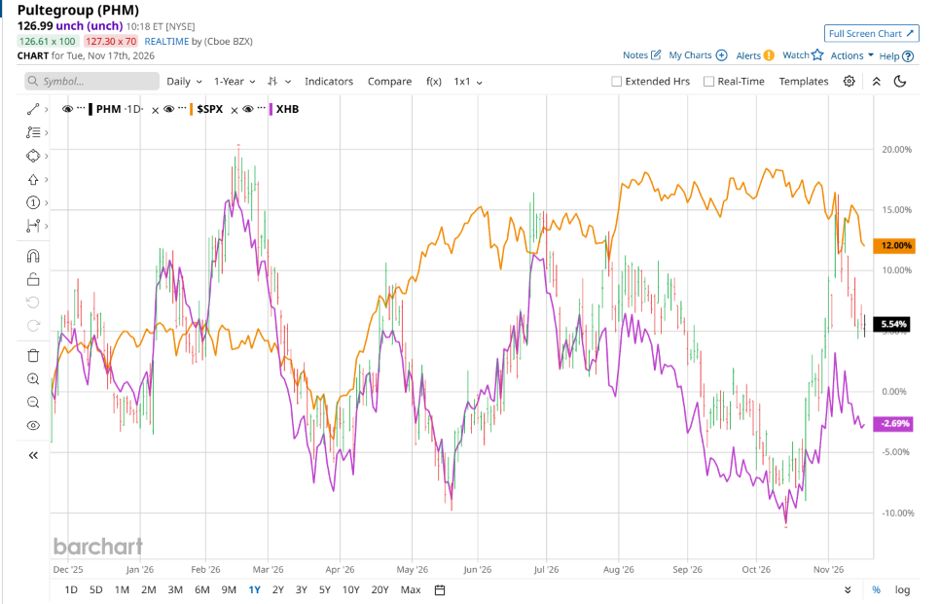
Shares of this homebuilding giant have outperformed the broader market over the past year. PHM has gained 11.3% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.1%. However, in 2026, PHM stock is up 8.1%, compared to the SPX’s 8.3% rise on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Zooming in further, PHM’s outperformance is also apparent compared to the SPDR S&P Homebuilders ETF (XHB). The exchange-traded fund has declined marginally over the past year. Moreover, PHM’s gains on a YTD basis outshine the ETF’s 2.5% losses over the same time frame.
 www.barchart.com
PHM’s strong outperformance has been driven by disciplined capital allocation, aggressive cost-control initiatives, and exceptional resilience in its active adult segment. Despite broader macroeconomic headwinds, higher mortgage rates, and soft first-time buyer demand that weighed on closing volumes, the company successfully reduced build costs by 5% year over year and maintained strict inventory controls. Furthermore, robust 11% sign-up growth in its rate-resilient Del Webb brand (bolstered by cash-heavy buyers) and a healthy $6.4 billion backlog reinforced investor confidence in management's margin-preservation strategy, helping offset a Q3 earnings report where EPS of $2.53 missed Wall Street's $2.63 consensus estimate, alongside revenue of $4 billion falling short of the forecasted $4.1 billion.
For the current fiscal year, ending in December, analysts expect PHM’s EPS to decline 19% to $9.27 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimates in two of the last four quarters while missing the forecast on two other occasions.
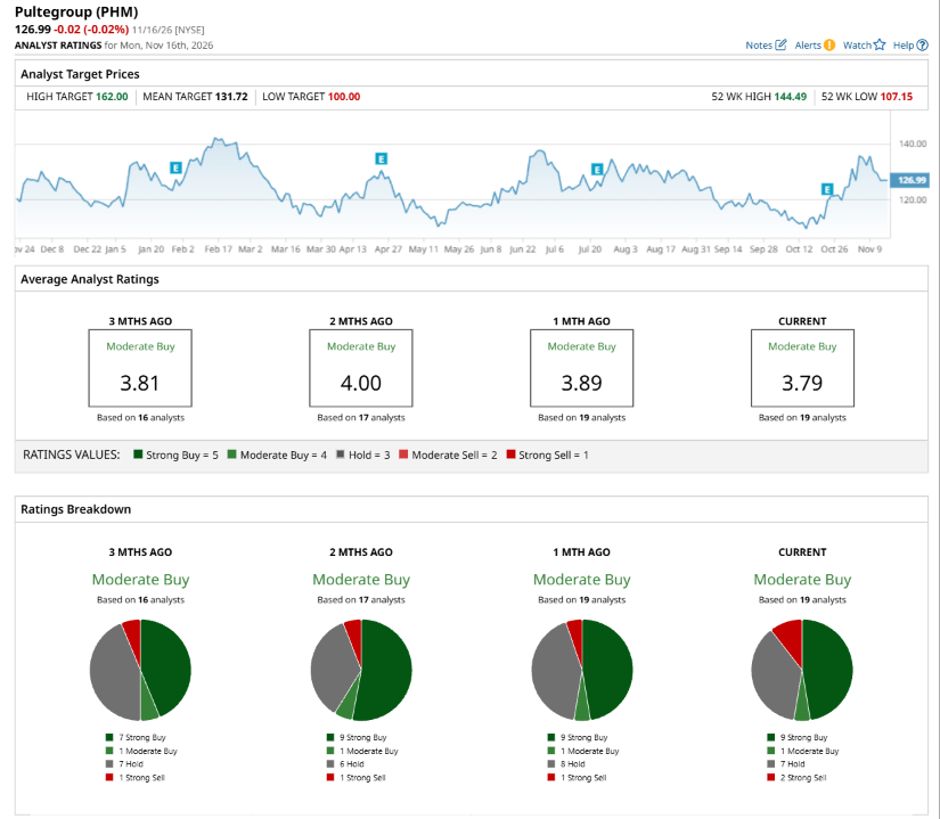
Among the 19 analysts covering PHM stock, the consensus is a “Moderate Buy.” That’s based on nine “Strong Buy” ratings, one “Moderate Buy,” seven “Holds,” and two “Strong Sells.”
 www.barchart.com
This configuration is less bearish than a month ago, with one analyst suggesting a “Strong Sell.”
On Nov. 3, Morgan Stanley (MS) analyst Adam Kramer kept an “Equal Weight” rating on PHM and lowered the price target to $120.
The mean price target of $131.72 represents a 3.7% premium to PHM’s current price levels. The Street-high price target of $162 suggests a notable upside potential of 27.6%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘You Don’t Want Rogue Agents’: Jamie Dimon Shuts Meta’s Muse AI Agent Out of JPMorgan. What It Means for META Stock. Why Dan Ives Believes the Anthropic IPO Will Be an 'Important Step' for AI Investment -- And What It Means for a Future OpenAI IPO ‘We’re Still Slightly Bigger’: Palo Alto CEO Jabs CrowdStrike. Here’s How to Play PANW and CRWD Stock Before Earnings. Dear Nvidia Stock Fans, Mark Your Calendars for December 3