

Carnival Corp. (CCL) put options with a strike price below today's price and expiring in about 5 months saw unusually high volume today. That may signal that some investors believe CCL is cheap by shorting these out-of-the-money (OTM) puts. It also lets them collect a high yield upfront.
CCL is trading at $28.68 in early trading today, but these puts have a $26.00 strike price. Moreover, CCL is off its recent peak of $31.32 on Nov. 4, but up from a recent trough of $26.11 on Oct. 23.
Can’t Get Enough Options?: Join the list for Barchart’s daily unusual options report, delivered free.
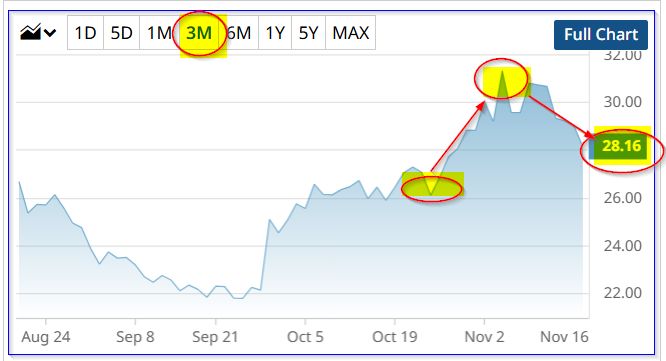 CCL stock - last 3 months - Barchart - Nov. 18, 2026
There are good reasons to believe CCL could be undervalued. Along with the high premium available to short-sellers, this may be why there is such huge volume in these OTM puts.
Unusual CCL Put Volume
Today's Barchart Unusual Stock Options Activity Report today shows this heavy put volume. The report shows that puts expiring April 16, 2027, at the $26.00 strike price have traded over 5,200 puts. That is over 40 times the prior number of puts outstanding at that price and expiry period.
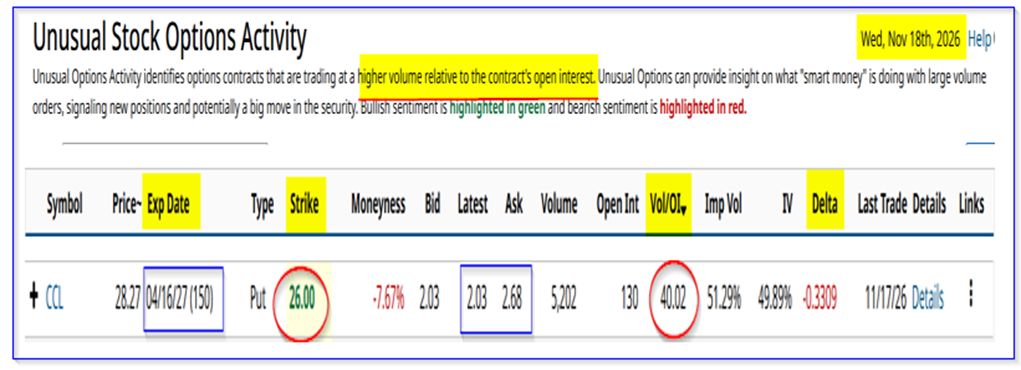 CCL puts expiring April 16, 2027 - Barchart Unusual Stock Options Activity Report - Nov. 18, 2026
Moreover, the premium was $2.03, which represents a short-put yield of 7.808% (i.e., $2.03/$26.00) over 5 months. However, the midpoint is $2.34, a 9.0% expected yield.
In other words, short-sellers are able to make a monthly yield between 1.562% and 1.80%. Those are very attractive to institutional investors, especially those that already own CCL shares.
For example, it would allow them to potentially buy more shares at a lower price ($23.66 to $23.97), if CCL drops to $26.00 at any point before April 16, 2027.
Put Credit Spread Trade
It's also possible some investors are investing in a put credit spread, i.e., shorting the $26.00 put and buying a lower strike price put such as at $20.00. For example, the 4/16/27 $20.00 put today has a $0.45 midpoint.
Therefore, the spread income is $2.36 - $0.45, or $1.91. However, the brokerage will require only $6,000 in collateral (i.e., ($26.00 - $20.00) x 100) , not $26,000 required to short the $26.00 put. This means there is just $1,809 at risk, so the expected return is:
$191/$1,809= 10.558%
That is higher than the $9.0% short-put yield with a higher $26,000 collateral requirement. As long as CCL stays over $24.09, the breakeven point (i.e., $26.00 - $1.91), or 15.89% below today's price, the investor won't begin to lose money.
Will that happen? In other words, is CCL undervalued here? Let's look at that.
What Carnival Corp May Be Worth
First of all, analysts think CCL is worth more. The average price target (PT) of 30 analysts is $33.56 per share, or +17% higher. The same goes for Barchart ($33.81) and AnaChart ($34.57 from 22 analysts).
Second, using a forward Price/Earnings (P/E) metric, CCL looks cheap. For example, the average forward P/E over the last 5 years, taken from Morningstar data, is 13.62x.
Today, CCL is at 10.92x, and the 2027 earnings per share (EPS) estimate is $2.58. As a result, 13.62 x $2.58 results in a price target of $35.14, or +22.8% above today's price.
Third, on a free cash flow (FCF) basis, using an FCF yield metric, CCL looks undervalued. For example, analysts forecast revenue will rise by over 3.1% next year to $28.6 billion. Using its last 12-month (LTM) FCF margin of 11.51% (taken from Stock Analysis data), its FCF could hit $3.29 billion.
As a result, using its historical 8.0% FCF yield metric, Carnival could be worth $41.1 billion (i.e., $3.29b/0.08). That's +8.56% higher than today's market cap of $37.86 billion. This implies a FCF-based PT of $31.14.
Summary and Conclusion
Using analysts' price targets (PTs), CCL is worth 17.0% more, and using forward P/E metrics, it's worth 22.8% more. Moreover, with an FCF margin and FCF yield model, it's worth 8.56% more. So, on average, the PT is 16.1% higher, or $33.30 per share.
That could why there is heavy out-of-the-money (OTM) put option activity at the $26.00 price expiring April 16, 2027. By then, the market will have a clearer forecast of 2027 earnings and better insight on how undervalued the stock is by then.
After all, these short-sellers are able to make a good monthly yield, 1.80%, while waiting to potentially buy in at this lower strike price. Moreover, put credit spread investors make a good return by hedging the downside (buying a lower strike price put), with significantly less collateral required.
On the date of publication, Mark R. Hake, CFA did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play NKE Stock as Nike Risks Becoming a Forever Turnaround Story Michael Burry Is Doubling Down on Adobe Stock. Here's Why. Trump’s ‘National Champion’ Stocks Include Nvidia, Amazon, and Microsoft, Says WSJ. Will the Designation Really Matter? You Likely Haven’t Heard of This Hot Stock, But Its Roots Date Back to 1816