

Shares of Onfolio Holdings Inc. ONFO have lost 53.2% since reporting results for the second quarter of 2026. This compares with the S&P 500 index’s 0.2% return over the same time frame. Over the past month, ONFO shares have fallen 53.8% and the S&P 500 has declined 0.8%.
Onfolio reported second-quarter revenues of $1.50 million, down 52% from $3.15 million a year earlier. Services revenues, primarily from the B2B segment, fell 41% to $1.22 million, while product sales, primarily from B2C, dropped 74% to $279,000.
The company posted a loss of $35.57 per common share compared with a loss of $6.49 a year ago. Net loss attributable to Onfolio widened to $4.54 million from $570,000, while net loss to common shareholders increased to $4.67 million from $666,000.
Onfolio Holdings Inc. Price, Consensus and EPS Surprise
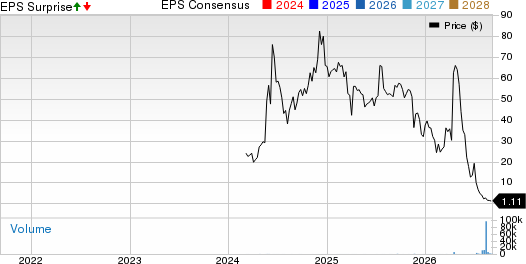
Onfolio Holdings Inc. price-consensus-eps-surprise-chart | Onfolio Holdings Inc. Quote
Other Key Business Metrics
Gross profit fell to $732,000 from $1.94 million, and the gross margin declined to about 49% from 62%. Operating expenses declined 31% to $1.70 million from $2.44 million, helped by a 45% reduction in SG&A, although professional fees rose 60% because of financing arrangements, Nasdaq compliance work and strategic transaction activity. The operating loss widened to $966,000 from $507,000. Adjusted EBITDA was negative $776,000, versus negative $151,000 a year earlier.
As of June 30, cash stood at $251,000, down from $2.17 million as of 2025-end, while digital assets were valued at $1.33 million. B2B recorded an operating loss of about $103,000 versus operating income of $70,000, while B2C operating income fell to about $43,000 from $150,000.
Management Commentary
CEO Dominic Wells said that the portfolio did not turn the corner in the quarter as originally expected. He pointed to cash constraints at the parent company and softer-than-planned portfolio cash generation, which limited resources available for growth.
Eastern Standard, Onfolio’s largest agency, faced slower new sales as customers questioned traditional agency pricing amid wider adoption of AI tools. RevenueZen, however, continued to improve under Eastern Standard’s management, while Proofread Anywhere remained profitable but was not growing after Onfolio reduced paid customer-acquisition spending to protect unit economics.
Factors Behind Headline Numbers
The sharp revenue decline reflected weaker new sales at Eastern Standard, lower revenues at several other agency businesses and reduced advertising at Proofread Anywhere. The mix also shifted toward lower-margin B2B services as higher-margin B2C revenues contracted faster, keeping the gross margin near 49% rather than moving toward the mid-60% range previously discussed.
The reported net loss was also amplified by non-cash and financing-related items, including a $2.95-million loss from the change in fair value of a derivative liability, a $281,000 loss from changes in digital-asset values and higher interest expenses tied to the senior secured notes.
Outlook
Management reset several expectations. The gross margin is expected to remain near current levels until B2C revenues stabilize. Wells said that the company’s priorities for the rest of 2026 are to increase portfolio cash flow, reduce parent-company costs and resume accretive acquisitions.
Onfolio is targeting an Oct. 1 close for a seller-financed acquisition with roughly $4 million of trailing 12-month adjusted EBITDA, while another target with more than $1 million of trailing EBITDA had its upfront cash requirement renegotiated down to $1.3 million from $3.5 million. Management also expects third-quarter results to reflect the unwind of the derivative liability following settlement of the senior secured notes rather than additional losses against it.
Other Developments
Onfolio continued consolidating RevenueZen under Eastern Standard during the second quarter, an integration intended to align costs and operations across agency businesses. Management said that RevenueZen was a standout performer, with improved results partly offsetting Eastern Standard weakness. B2C revenues also reflected the absence of revenues from businesses divested during 2026. Separately, Onfolio launched SharePulse and Parlance through Onfolio Labs, adding an asset-light recurring-revenue software line alongside the acquisition portfolio.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Onfolio Holdings Inc. (ONFO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).