

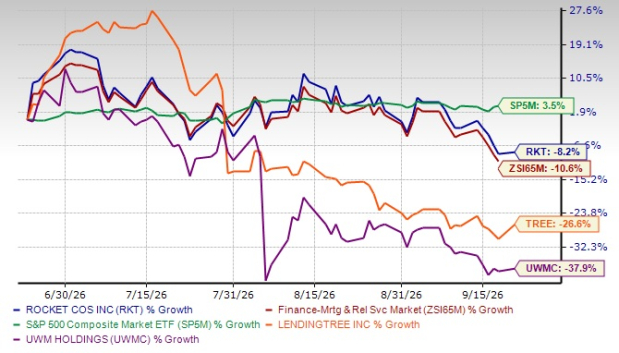
Shares of Rocket Companies RKT touched a new 52-week low of $12.13 yesterday to finally close at $12.36. Over the past three months, RKT shares have lost 8.2% compared with the industry’s 10.6% decline. In the same time frame, RKT’s peers LendingTree TREE and UWM Holdings UWMC have lost 26.6% and 37.9%, respectively.
3-Month Price Performance
Image Source: Zacks Investment Research
Continued concerns over a challenging U.S. mortgage and housing environment have been keeping investors on the sidelines. Mortgage rates have climbed back up, driven by elevated treasury yields, persistent inflation and the Federal Reserve’s recent rate hike, pressuring housing affordability, and potentially suppressing home-purchase and refinancing activity.
These concerns are particularly relevant for Rocket, as management has already indicated that the expected housing-market recovery in 2026 has not materialized and has guided third-quarter 2026 adjusted revenues of $2.5-$2.7 billion, below the second-quarter level, implying softer sequential mortgage activity.
Thus, despite strong second-quarter 2026 profitability, the combination of higher rates, weak housing affordability, subdued industry volumes and uncertainty over the pace of a housing recovery continues to weigh on investor sentiment.
Other Factors Impacting RKT’s Growth
Elevated Expenses & Integration Risk: Rocket has an elevated expense base and heavy interest burden, compounded by integration-related charges. Over the last six years (2019-2025), total expenses witnessed a compound annual growth rate (CAGR) of 8.8%, with the uptrend continuing in the first half of 2026.
Interest expenses increased significantly year over year to $374 million in the second quarter, reflecting a heavier funding burden. The company is simultaneously integrating the Redfin and Mr. Cooper acquisitions, adding execution and timing risk even as early indicators appear constructive.
Management targets $400 million in Mr. Cooper expense synergies by 2026 end and expects another $100 million in annualized synergies in the first half of 2027. However, the pace of capture remains important because the third-quarter expense guidance includes acquisition-related costs, stock-based compensation and amortization of acquired intangibles. In the absence of a stronger rate-driven volume tailwind, rising expenses are likely to delay meaningful profitability improvement.
Competition & Regulation Concerns: Mortgage origination and servicing remain rule-bound, and changes in requirements can increase compliance costs, slow cycle times or restrict marketing and product flexibility. Competition remains intense across direct-to-consumer lenders, brokers, banks and fintech platforms, with pricing and promotions used to win share. These factors remain a meaningful overhang for Rocket.
In the aftermath of the 2008 financial crisis, regulators strengthened capital standards, including increasing the cost of holding certain mortgage-related assets, under the global Basel frameworks to enhance financial stability. Hence, banks’ share of mortgage originations declined significantly, while non-bank lenders like Rocket gained dominance. Any change in regulatory treatment of MSRs could reverse the trend, and elevated competitive intensity could compress gain-on-sale margins and reduce recapture.
Analyzing RKT’s Valuation & Analyst Sentiments
Despite the recent slide in price, RKT shares are trading at a premium to the industry. At present, the company has a forward 12-month price-to-earnings (P/E) of 15.39X, which is above the industry average of 14.94X.
P/E F12M
Image Source: Zacks Investment Research
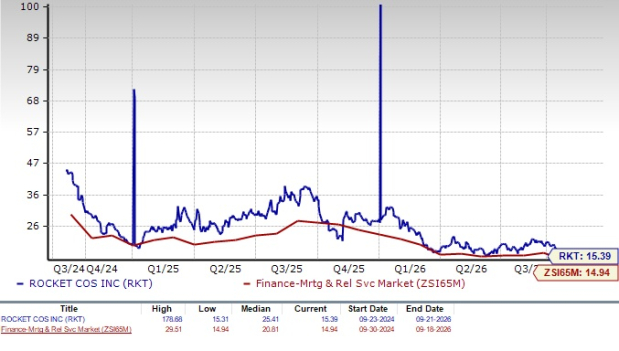
Then again, LendingTree and UWM Holdings are trading at a discount to RKT. Currently, TREE and UWMC have forward 12-month P/E of 4.33X and 5.31X, respectively.
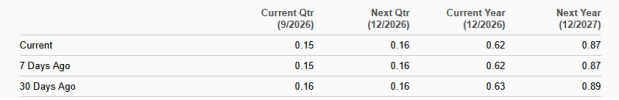
Analysts are not optimistic regarding Rocket’s earnings growth prospects. The Zacks Consensus Estimate for the company’s 2026 and 2027 earnings has been revised lower over the past 30 days.
Estimate Revision Trend
Image Source: Zacks Investment Research
RKT’s Long-Term Story Still Remains Intact
Rocket's long-term story is not without merit. Its end-to-end housing platform is positioned to benefit from improving mortgage demand and capture further market share. The Redfin and Mr. Cooper integrations have expanded its reach across home search, origination, servicing and client retention.
In the first half of 2026, Rocket continued to gain purchase and refinance share, supported by a servicing portfolio of $2 trillion in unpaid principal balance and 9.1 million clients. The portfolio provides recurring fee income, and a large pool of refinance and purchase leads.
Rocket continues to embed AI across prospecting, underwriting and client workflows to scale volume without proportional staffing. In the first half of 2026, AI tools helped loan officers serve more clients, reduced prospecting time and improved conversion. AI Voice also handled more than 1 million servicing calls while cutting task-resolution time by 25%.
These efficiencies have enabled Rocket to operate with several hundred fewer production employees, while management estimates its AI-enabled platform can support up to $300 billion in mortgage originations.
Parting Thoughts on Rocket
RKT’s recent slide reflects more than short-term volatility. Near-term pressure from elevated mortgage rates, weak housing affordability, muted refinancing activity and intense competition are keeping buyers cautious. Its premium valuation leaves limited room for disappointment until earnings visibility improves.
That said, Rocket’s scale, expanded servicing base, AI-led efficiencies, and acquisitions of Redfin and Mr. Cooper support its long-term growth prospects. However, before making any investment decision, investors should wait for clearer signs of mortgage demand recovery, lower rates or stronger execution. Those who already own the RKT stock should hold on to it, because the company is less likely to disappoint in the long run.
At present, Rocket carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Rocket Companies, Inc. (RKT): Free Stock Analysis Report
LendingTree, Inc. (TREE): Free Stock Analysis Report
UWM Holdings Corporation (UWMC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).