

Howmet Aerospace Inc. HWM and Textron Inc. TXT are two prominent names operating in the aerospace and defense industry. As rivals, both companies are engaged in producing highly engineered aircraft components for commercial and military aircraft in the United States and internationally.
Both companies are poised to benefit from significant growth opportunities in the aerospace and defense space on account of healthy air traffic trends and the robust U.S. budgetary policy over the past few years. But which company is better positioned to deliver upside in 2026? Let’s compare their fundamentals, growth prospects and challenges to see which stock stands out now.
The Case for Howmet
Howmet is benefiting from persistent strength in its commercial aerospace market. Revenues from the commercial aerospace market increased 28% year over year in the second quarter of 2026, constituting 53% of its business. The top-line growth was driven by solid demand for engine spares and a record backlog for new, more fuel-efficient aircraft with reduced carbon emissions. Going forward, demand for Howmet’s aerospace products is expected to remain strong, backed by the healthy build rates at Airbus for A320 (narrowbody) and A350 (widebody) aircraft and production recovery of the Boeing 737 MAX aircraft.
Expanding defense budget remains another growth catalyst for the company. HWM continues to see strong demand for engine replacement parts tied to the F-35 program, along with components for other legacy fighters like F-15 and F-16. In the second quarter, revenues from the defense aerospace market surged 11% year over year, constituting 15% of the company’s revenues.
The company is also stepping up its focus on emerging programs, especially those involving drones and collaborative combat aircraft. Strong demand for industrial gas turbines is driving the performance of the gas turbines market, which grew 38% in the quarter.
Driven by strength across its businesses, Howmet raised its 2026 revenue outlook to $10.00-$10.10 billion. Adjusted EBITDA is anticipated between $3.21 billion and $3.25 billion, with adjusted earnings projected at $5.23-$5.31 per share.
In April 2026, HWM completed its $1.8 billion buyout of Consolidated Aerospace Manufacturing LLC (“CAM”), a business unit of Stanley Black & Decker SWK. The acquisition enhanced HWM’s aerospace fastening solutions portfolio by adding CAM’s established brands, engineering capabilities and long-standing customer relationships.
HWM’s shareholder-rewarding policies are also encouraging. In the first six months of 2026, the company paid dividends of $97 million, and in July 2026, it hiked its dividend by 17% to 14 cents per share (annually: 56 cents). Additionally, through July, the company had repurchased $800 million worth of shares year to date.
The Case for Textron
Commercial aircraft demand and aftermarket activity continue to support Textron’s Aviation business unit. In the second quarter of 2026, Textron Aviation unit’s revenues increased 1% year over year to $1.54 billion. The company has been witnessing strong order activity, which resulted in a backlog of about $8 billion for the Aviation segment. Such a robust backlog count strengthens Textron’s revenue-generating capacity in the coming quarters.
Besides its strong presence in the commercial aerospace market, Textron enjoys solid demand for its defense products as well. Revenues from the Bell segment increased 6% year over year to $1.1 billion in the second quarter, driven largely by higher H-1 and MV-75 volume, while commercial helicopter deliveries rose to 36 from 32.
Textron Systems also posted a 7% increase in revenues, driven by armored vehicles and ATAC services, while segment profit advanced 10%. Exiting the second quarter, Bell and Systems reported backlogs of $7.5 billion and $3.3 billion, respectively, providing support for visibility beyond near-term deliveries.
The company’s strong liquidity position also adds to its strength. Its cash and cash equivalents amounted to $1.4 billion at the end of the second quarter. While Textron’s long-term debt totaled $3.1 billion, its current debt was $355 million. Although the long-term debt value is higher, its current debt remains much lower than the cash reserve. It seems that the company boasts a solid solvency position, at least in the short term.
In the second quarter, the company also bought back $209 million worth of shares, bringing total repurchases for the first half of 2026 to $377 million. As a result, common shares outstanding declined to 171.9 million from 174.3 million at the end of 2025.
However, persistence of supply-chain issues arising out of component shortages and delays is expected to result in production delays for some of Textron’s products. For instance, in second-quarter 2026, Textron Aviation segment’s profit declined despite revenue growth, reflecting manufacturing inefficiencies and lower aircraft volume and mix.
Bell’s MV-75 program continues to face uncertainty over the timing of an additional $350 million funding request for 2026. Management’s full-year financial guidance assumes the receipt of the funding. Without additional funding, management anticipates adjusted earnings per share (EPS) could decline by 20-30 cents, while manufacturing cash flow could fall by $150-$250 million.
Price Performance
Image Source: Zacks Investment Research
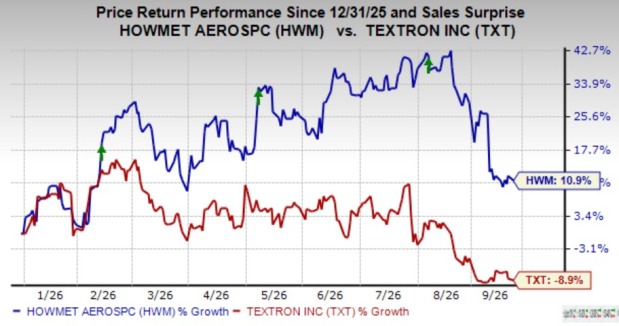
In the year-to-date period, Howmet shares have gained 10.9%, while Textron stock has lost 8.9%.
The Zacks Consensus Estimate for HWM & TXT
Image Source: Zacks Investment Research
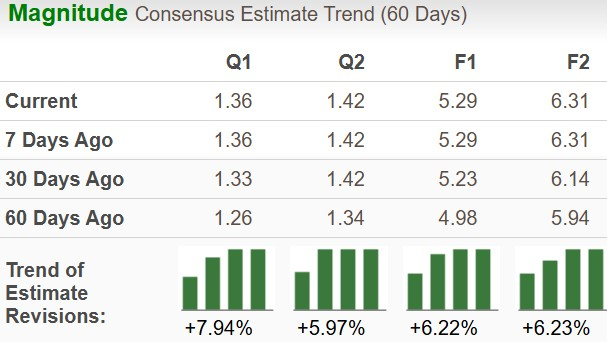
The Zacks Consensus Estimate for HWM’s 2026 sales and EPS implies year-over-year growth of 22.6% and 40.3%, respectively. HWM’s EPS estimates for both 2026 and 2027 have increased 6.2% over the past 60 days.
Image Source: Zacks Investment Research
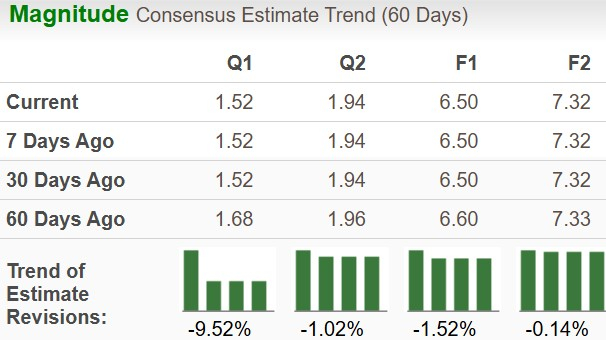
The Zacks Consensus Estimate for TXT’s 2026 sales and EPS implies year-over-year growth of 4.9% and 6.6%, respectively. However, TXT’s EPS estimates for 2025 and 2026 have declined 1.5% and 0.1%, respectively, over the past 60 days.
TXT’s Valuation More Attractive Than Howmet
Image Source: Zacks Investment Research
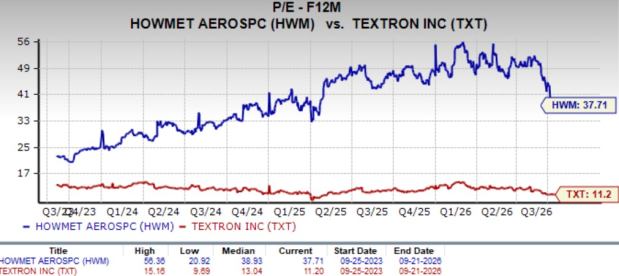
TXT is trading at a forward 12-month price-to-earnings ratio of 11.20X, below its median of 13.04X over the last three years. Howmet’s forward earnings multiple sits at 37.71X, close to its median of 38.93X over the same time frame.
Final Take on HWM & TXT
Textron’s strong momentum in the commercial and defense aerospace markets, along with its robust pipeline of projects, favors well for its growth in the quarters ahead. A strong liquidity position in the short run is an added strength. However, this has been marred by supply-chain challenges and additional funding uncertainty for its Bell’s MV-75 program, which might affect its near-term performance.
In contrast, Howmet’s market leadership position and persistent strength in both commercial and defense aerospace markets provide it with a competitive advantage to leverage the long-term demand prospects in the aerospace market. Despite its steeper valuation, HWM seems to be a better pick than TXT currently due to strong estimates, stock price appreciation and better prospects for sales and profit growth.
While HWM carries a Zacks Rank #2 (Buy), TXT currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Textron Inc. (TXT): Free Stock Analysis Report
Howmet Aerospace Inc. (HWM): Free Stock Analysis Report
Stanley Black & Decker, Inc. (SWK): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).