

S&P Global Ratings (S&P) upgraded the issuer credit rating of Rithm Capital Corp. RITM to ‘B+’ from ‘B’, while maintaining a stable outlook. S&P also raised the rating on Rithm Capital’s senior unsecured notes to ‘B’ from ‘B-’.
The upgrade reflects RITM's continued efforts to scale and diversify its earnings streams through its asset management, residential transitional lending (RTL) and commercial real estate businesses. Meanwhile, the company's mortgage finance subsidiary, Newrez, has maintained stable earnings despite a challenging macroeconomic environment, supporting the rating action.
Why S&P Upgraded RITM's Rating
Diversification Supports Earnings: Rithm Capital has continued to expand its nonmortgage finance businesses, increasing their contribution to the company’s overall business mix. As of June 30, 2026, asset management, RTLs and commercial real estate accounted for nearly 33% of the company’s stockholders’ equity and total revenues compared with 9% and 13%, respectively, for nonmortgage finance operations at 2022-end.
S&P expects continued growth in these businesses to drive higher contributions from management fees, net interest income and rental revenue. This is expected to reduce RITM’s reliance on mortgage finance operations and further diversify its earnings base.
Expanding Asset Management and RTL Businesses: The company’s asset management platform continued to expand, with assets under management (AUM) reaching approximately $61 billion as of June 30, 2026, up from $34 billion at 2024-end. Growth was supported by the acquisition of Crestline and organic expansion. While the platform’s earnings contribution remains modest due to its high-cost base, S&P expects higher AUM to improve operating leverage and support margin expansion.
Its Genesis platform, acquired in December 2021, also continued to expand its RTL business. The RTL loan portfolio increased to $3.8 billion as of June 30, 2026, from $2.7 billion at 2025-end. The business generated $60 million in pretax income in the first half of 2026, up from $41 million in the prior-year period, reflecting continued demand from institutional sponsors in the single-family and multifamily markets.
Its asset quality also remains stable, with past-due loans accounting for 2.5% of total unpaid principal balance as of June 30, 2026, compared with 3.7% at 2025-end. Going forward, S&P expects Rithm Capital to increasingly use third-party capital to fund originations, allowing the company to expand its asset management platform while reducing capital intensity.
Newrez Provides Stable Earnings: The company’s mortgage finance subsidiary, Newrez, continues to support its earnings profile despite challenging economic conditions. In the first half of 2026, Newrez generated approximately $581 million in pretax income, excluding mortgage servicing rights mark-to-market and hedging results, up 7% from the same period in 2025.
The improvement was driven by higher origination volumes and stable servicing revenue. Although Newrez incurred significant hedging losses in the second quarter of 2026 amid elevated interest-rate volatility, S&P expects some of these losses to reverse in the third quarter.
Looking ahead, high mortgage rates could continue to pressure mortgage origination volumes, particularly in the refinance market, while intensifying competition across the industry. Nevertheless, S&P expects Newrez to maintain relatively stable earnings through the interest-rate cycle, supported by disciplined origination pricing, favorable economics from its low-coupon servicing portfolio and ongoing cost-reduction initiatives.
Healthy Leverage and Liquidity Position: The company’s leverage remains within S&P’s expected range of 4.5X-6.5X on a sustained basis, with the debt-to-adjusted total equity (ATE) ratio at 5.7X as of June 30, 2026, up from 5.4X at 2025-end. The increase was primarily driven by higher asset-backed securities debt as the company expanded its securitization activities.
Meanwhile, liquidity remains adequate, with approximately $1.7 billion of cash and cash equivalents and another $400 million of available committed funding capacity as of June 30, 2026. S&P noted that RITM remains in compliance with its financial covenants and regulatory liquidity and net worth requirements, with adequate cushions. The company also has no unsecured debt maturities until 2029, providing additional funding flexibility.
Factors Influencing Future Ratings of RITM
The stable outlook reflects S&P's expectation that Rithm Capital will continue to increase its scale and business diversification while maintaining stable earnings and adequate liquidity. The agency expects debt to ATE to remain within the 4.5X-6.5X range.
However, rating pressure could emerge if RITM faces difficulty renewing funding facilities, increases its reliance on secured funding, allows debt-to-ATE to rise above 6.5X or shifts toward materially riskier assets. Conversely, an upgrade could become possible if it maintains access to funding, reduces reliance on secured financing, keeps debt-to-ATE below 4.5X and maintains a diversified asset mix, along with stable earnings and adequate liquidity.
RITM’s Price Performance & Zacks Rank
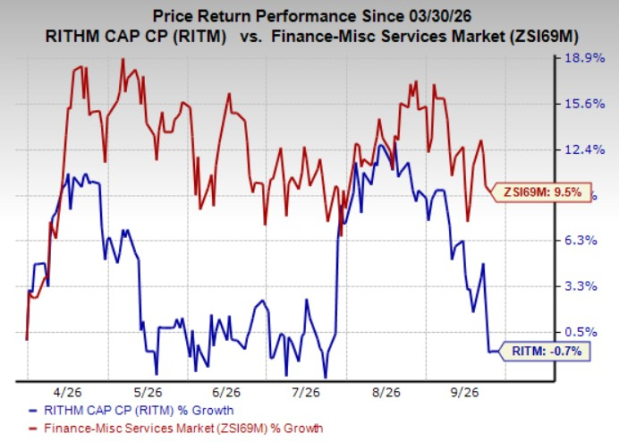
RITM shares have lost 0.7% in the past six months against the industry’s growth of 9.5%.
Image Source: Zacks Investment Research
At present, RITM carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Rating Action on Other Banks
Similar to RITM, in September 2026, S&P Global Ratings also upgraded the long-term issuer credit rating of Capital One Financial Corp. COF to ‘BBB+’ from ‘BBB’, while maintaining a stable outlook. S&P also raised the long-term issuer credit rating of Capital One N.A. to ‘A-’ from ‘BBB+’ and affirmed its short-term issuer credit rating at ‘A-2’.
The upgrade reflects COF’s stronger franchise and progress in integrating Discover. S&P expects the acquisition to support card purchase volumes, fee income and revenue stability, while its auto-lending and corporate finance businesses provide additional diversification.
In the same month, Citizens Financial Group, Inc. CFG announced that Fitch Ratings upgraded its and Citizens Bank N.A.'s long-term issuer default ratings (IDRs) to ‘A-’ from ‘BBB+’, while maintaining a stable outlook. Fitch also upgraded the companies’ viability ratings to ‘a-’ from ‘bbb+’ and affirmed their short-term IDRs at ‘F1’.
The upgrade reflects sustained improvements in earnings and profitability, supported by asset repricing, stable credit costs and growth in fee-generating businesses. Fitch also cited CFG’s diversified business model, strong deposit franchise, adequate capital and stable asset quality.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Rithm Capital Corp. (RITM): Free Stock Analysis Report
Capital One Financial Corporation (COF): Free Stock Analysis Report
Citizens Financial Group, Inc. (CFG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).