

Delta Air Lines DAL reported third-quarter 2026 earnings (excluding 57 cents from non-recurring items) of $1.72 per share, missing the Zacks Consensus Estimate of $1.80 by 4.44%. Earnings increased year over year despite sharply higher fuel costs and rising non-fuel expenses.
Adjusted revenues climbed 16% year over year to $17.59 billion but missed the consensus estimate of $17.74 billion by 0.9%. Broad demand strength and healthy yields lifted adjusted total revenue per available seat mile, or TRASM, 15%, while premium and diversified revenue streams continued to expand.
DAL Benefits From Broad-Based Passenger Revenue Growth
Passenger revenues increased 15% year over year to $15.53 billion. Premium-product ticket revenues climbed 18% to $6.82 billion, while main-cabin ticket revenues rose 12% to $6.80 billion. Loyalty travel awards and travel-related services revenues grew 18% and 14%, respectively.
Premium products and diversified revenue streams generated $10.78 billion, accounting for 61% of adjusted operating revenues. Management cited strong demand, healthy yield growth and disciplined capacity management as key contributors. Main-cabin unit revenues increased 17% despite a low-single-digit reduction in seats.
Delta Air Lines Price, Consensus and EPS Surprise
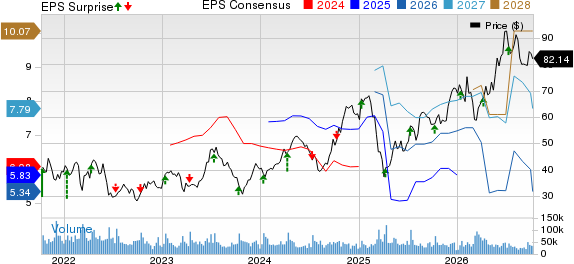
Delta Air Lines price-consensus-eps-surprise-chart | Delta Air Lines Quote
Delta Records Revenues Rise Across Key Markets
Domestic revenues advanced 16% year over year to $10.59 billion, supported by 16%-unit revenue growth and a 15% increase in yield. Atlantic revenues rose 11% to $3.32 billion, with unit revenues climbing 11% on relatively flat capacity.
Latin American revenues increased 14% to $867 million despite a 6% capacity reduction, reflecting 22%-unit revenue growth and a 20% improvement in yield. Pacific revenues grew 13% to $756 million as capacity expanded 8%. Corporate sales increased at a double-digit rate across all sectors, led by Banking, Technology and Energy.
Revenue passenger miles (a measure of air traffic) increased 1% to 68.13 billion. Capacity, measured in available seat miles, remained relatively flat at 79.29 billion. Consolidated passenger load factor (% of seats filled by passengers) remained unchanged at 86%.
DAL Sees Continued Strength in Diversified Revenues
Cargo revenues increased 29% year over year to $301 million, supported by roughly equal contributions from volume and yield growth. Maintenance, repair and overhaul revenues climbed 28% to $296 million, bringing year-to-date revenues to $990 million.
Loyalty and related revenues rose 19% to $1.35 billion. American Express remuneration increased 15%, supported by double-digit growth in co-brand card acquisitions and the eighth consecutive quarter of double-digit cardholder spending growth. Travel products and non-air partnership revenues advanced 25%.
Delta's Higher Fuel Expenses Pressure Profitability
Adjusted operating expenses increased 18% year over year to $15.92 billion. Adjusted fuel expenses surged 62% to $4.14 billion as the adjusted average fuel price climbed 60% to $3.61 per gallon. Fuel consumption edged up 1% to 1.15 billion gallons.
Adjusted operating income declined 2% to $1.66 billion, while the adjusted operating margin contracted 170 basis points to 9.4%. Non-fuel costs increased 8% to $11.13 billion, and non-fuel unit costs rose 7.3% to 14.03 cents, primarily reflecting higher crew and revenue-related expenses.
DAL Generates Cash Flow and Strengthens Balance Sheet
Adjusted operating cash flow totaled $1.72 billion in the September quarter, declining 6% year over year. Gross capital expenditures increased 27% to $1.41 billion, leaving free cash flow of $463 million compared with $833 million a year earlier.
Adjusted net debt stood at $13.35 billion at quarter-end, down $950 million from the end of 2025 and $2.24 billion year over year. Delta ended the quarter with $3.79 billion in cash and cash equivalents and $6.9 billion in liquidity, including $3.1 billion in undrawn revolving credit capacity.
Delta Expects Strong Revenue Growth in Q4
For the fourth quarter of 2026, Delta expects adjusted earnings of $1.15-$1.65 per share. The Zacks Consensus Estimate for fourth-quarter earnings per share is currently pegged at $1.60 (above the midpoint of the guided range). The company projects an adjusted operating margin of 7-9% and approximately 20% year-over-year revenue growth.
Management expects continued improvement in unit revenues across domestic and international markets. Non-fuel unit cost growth is projected to improve sequentially by 1-2 percentage points, while the all-in fuel price is estimated at approximately $4.25 per gallon.
DAL Cuts Full-Year 2026 Earnings Outlook
Delta now expects full-year adjusted earnings of $5.10-$5.60 per share (earlier expectation was in the range of $6.50-$7.50). The Zacks Consensus Estimate is currently pegged at $5.34 per share. Free cash flow is expected to be approximately $2.5 billion. The company anticipates pre-tax profit of roughly $4.5 billion despite absorbing a $6 billion increase in fuel costs.
Management plans to repay more than $2 billion of debt during 2026 and expects gross leverage of approximately 2.2 times by year-end. The company also projects a double-digit return on invested capital.
DAL’s Zacks Rank
Currently, DAL carries a Zacks Rank #5 (Strong Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Upcoming Earnings Release of Other Transportation Companies
J.B. Hunt Transport Services JBHT is scheduled to report third-quarter 2026 earnings on Oct. 15. The Zacks Consensus Estimate for third-quarter 2026 earnings has been revised 10.4% downward over the past 60 days. JBHT’s earnings beat the Zacks Consensus Estimate in each of the preceding four quarters, the average surprise being 9.8%.
Union Pacific UNP is scheduled to report third-quarter 2026 earnings on Oct. 22.
The Zacks Consensus Estimate for third-quarter 2026 earnings has been revised 0.9% upward over the past 60 days. UNP’s earnings beat the Zacks Consensus Estimate in three of the preceding four quarters (missing the mark on the other occasion). The average beat is 2.8%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Delta Air Lines, Inc. (DAL): Free Stock Analysis Report
Union Pacific Corporation (UNP): Free Stock Analysis Report
J.B. Hunt Transport Services, Inc. (JBHT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).