

Ciena Corporation CIEN is benefiting from strong demand for optical networking solutions as artificial intelligence (AI), expanding data centers and rising network traffic drive investments in connectivity infrastructure. The company delivered record financial results in the third quarter of fiscal 2026, with revenues rising 37% year over year to $1.67 billion. Adjusted gross margin increased 450 basis points to 46.4%, while adjusted operating margin reached a record 22.5%, more than doubling from the year-ago quarter. Cost management, favorable product mix and pricing discipline supported the improvement.
Ciena's expanding optical networking and data center connectivity businesses are strengthening its growth and profitability prospects. Revenue from combined optical networks, including interconnects, grew more than 45% year over year. Routing and Switching and Waveserver systems each recorded growth of more than 55%, while interconnect revenue more than doubled. Direct cloud provider revenue increased more than 80%. The growing contribution of these offerings is supporting profitability, while next-generation products such as Hyper-Rail are expected to provide additional margin benefits as deployments scale.
The company is also strengthening its supply chain to address rising component demand. The company has secured long-term agreements for critical components through 2029, including incremental capacity to support growing customer requirements. It is expanding its supplier base and exploring alternative technologies to improve supply resilience. Although component availability remains a constraint on order fulfillment, these investments should help Ciena increase output and capitalize on its substantial backlog. Management expects supply and demand constraints to persist into 2028.
Pricing actions provide another potential source of margin support. Ciena has made progress in customer discussions on price increases across product lines, alongside payment terms, delivery commitments and capacity requirements. These measures aim to align customer demand with available supply while supporting profitability.
Ciena's long-term targets reinforce management's confidence in sustained growth and margin expansion. Recently, the company outlined fiscal 2029 targets, including approximately 30% revenue compound annual growth from fiscal 2026 through fiscal 2029, adjusted gross margin of approximately 50%, adjusted operating margin of 32-35% and free cash flow margin of approximately 20%.
However, achieving these targets will depend on securing sufficient component supplies and managing the investments required to expand capacity. Overall, strong demand, favorable product mix, pricing discipline and supply chain investments position Ciena to pursue further margin gains despite ongoing component constraints.
Taking a Look at CIEN’s Competitors
Corning Incorporated GLW is expanding its solar manufacturing footprint, but execution risks remain as operations scale. Growing AI infrastructure exposure supports growth but increases dependence on a few large customers. U.S.-China trade restrictions, tariffs and supply-chain disruptions could pressure margins, production efficiency and demand. For the third quarter, Corning expects core sales of $4.9-$5 billion, up approximately 16% year over year, and core earnings of 85-89 cents per share, reflecting roughly 28% growth. Under its upgraded Springboard Plan, the company targets a $20 billion annualized sales run rate by year-end 2026, $30 billion by 2028 and $40 billion by 2030.
Nokia NOK continues to benefit from its broad portfolio spanning mobile networks, optical transport, IP routing, fixed broadband, software and services. The company continues to execute its long-term strategy while balancing attractive growth opportunities against persistent industry risks. AI and cloud demand are emerging as key growth drivers, especially in Network Infrastructure, while strong licensing performance and disciplined capital allocation continue to support its long-term growth. For 2026, Nokia expects comparable operating profit in the range of €2.1-€2.6 billion, reflecting a technical revision from the previous range following the reclassification of two businesses as discontinued operations.
CIEN Price Performance, Valuation and Estimates
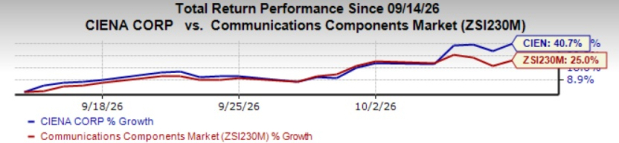
Shares of CIEN have gained 40.7% in the past month compared with the Communications - Components industry’s surge of 25%.
Image Source: Zacks Investment Research
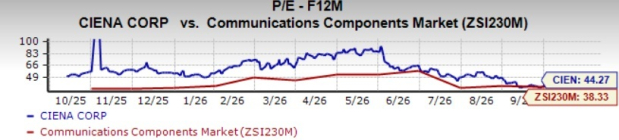
CIEN trades at a forward 12-month price-to-earnings (P/E) ratio of 44.27, above the industry’s 38.33.
Image Source: Zacks Investment Research
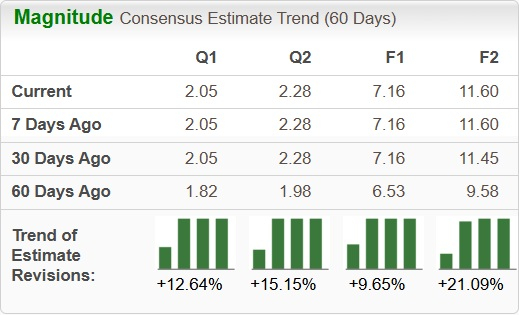
The Zacks Consensus Estimate for CIEN’s earnings for fiscal 2026 has been revised upward over the past 60 days.
Image Source: Zacks Investment Research
Ciena currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Ciena Corporation (CIEN): Free Stock Analysis Report
Nokia Corporation (NOK): Free Stock Analysis Report
Corning Incorporated (GLW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).