

Generac Holdings GNRC is benefiting from strong momentum in its Commercial & Industrial (C&I) segment, especially as data center operators expand artificial intelligence (AI) infrastructure.
While the company’s growing exposure to data centers and multiyear hyperscale agreements improves revenue visibility, rising contributions from lower-margin C&I products challenge profitability.
Data Center Growth Boosts Generac's Revenue Mix
C&I revenues totaled $556 million in the second quarter of 2026, up 29% year over year, driven by data center demand, mobile product strength and international growth. Data center product sales contributed more than $100 million in the second quarter, while orders from domestic industrial distributors reached a record high, buoyed by demand across traditional C&I markets.
On the last earnings call, management said that C&I segment net sales are expected to increase in the low 30% range in 2026, up from the prior mid-to-high 20% outlook.
Management expects data centers to remain a significant long-term growth opportunity amid accelerating infrastructure investments and AI adoption.
On the last earnings call, Generac noted that the data center backlog reached $1.6 billion as of July 2026, including roughly $1 billion of new orders received in the prior 90 days, while excluding expected orders from the second hyperscale agreement. Management also raised its 2026 data center revenue expectation to roughly $450 million, underscoring the rapid scaling of this business. Since then, Generac has finalized a long-term supply agreement with Amazon, with initial backup-generator deliveries expected to total $2.4 billion across 2027 and 2028.
Continued demand from data centers, mobile equipment and C&I energy storage systems supports a broader growth profile beyond a single end market.
The Profitability Troubles
Excluding tariff refunds, management expects 2026 gross margin near the low end of the prior 38.5% to 39.5% range due to higher C&I mix. C&I products generally carry lower margins than residential offerings.
In the second quarter of 2026, consolidated gross margin reached 44.5% from 39.3%. Tariff refunds added roughly 6% to gross margin growth. Also, favorable pricing partly offset unfavorable sales mix and higher input costs.
Despite these pressures, management maintained its 2026 adjusted EBITDA margin guidance of 18.5-19.5%, excluding tariff refunds. Significant operating leverage is expected to cushion EBITDA margins in the fourth quarter.
Margin Profile for Competitors
Cummins CMI is also rapidly expanding its data center footprint. The company is developing a 130-liter natural gas genset for prime power and supplying Circe Energy with QSK60 and HSK78 generators with microgrid technology for a prime power solution supporting a high-performance computing data center in Texas. In August, Cummins was selected to supply battery energy storage systems (“BESS”) for a large U.S. data center project, which would represent its largest BESS deployment to date.
Second-quarter 2026 Power Systems revenues rose 19% to $2.3 billion and the segment's EBITDA margin expanded to 24.5% from 22.8%, driven primarily by higher global power generation demand. Cummins expects Power Systems revenues to grow 14-19% in 2026, with EBITDA margins of 25-25.75%.
Caterpillar CAT is also expanding aggressively in data-center power, increasing competitive pressure. Second-quarter 2026 Power & Energy revenues increased 17% year over year to $8.2 billion, while segment operating margin expanded 250 basis points to 24.6%, aided by higher volumes and favorable pricing. Caterpillar expects Power & Energy margins to improve year over year in the third quarter, supported by higher sales volumes and favorable pricing, partially offset by higher manufacturing costs and capacity expansion expenses.
With shipments expected to commence in the fourth quarter, Caterpillar is adding capacity, including restarting a 10-MW medium-speed gas reciprocating platform with about 1.5 GW of planned capacity.
GNRC Price Performance, Valuation and Estimates
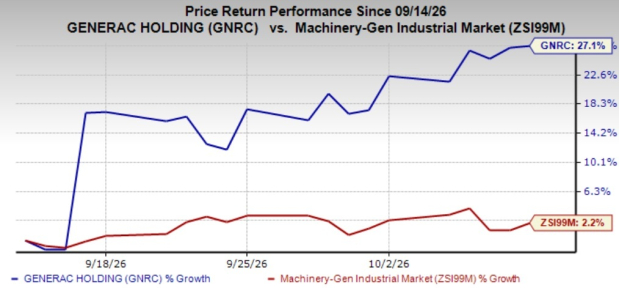
GNRC’s shares are up 27.1% in the past month while the Manufacturing-General Industrial sector has inched up 2.2%.
Image Source: Zacks Investment Research
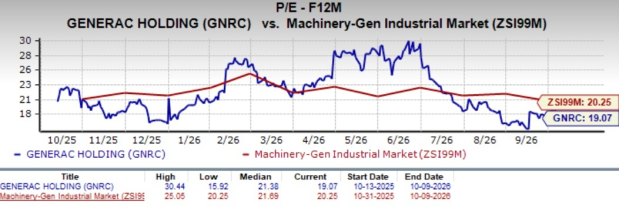
Generac is trading at a forward 12-month price/earnings ratio of 19.07X, lower than the sector’s multiple of 20.25X.
Image Source: Zacks Investment Research
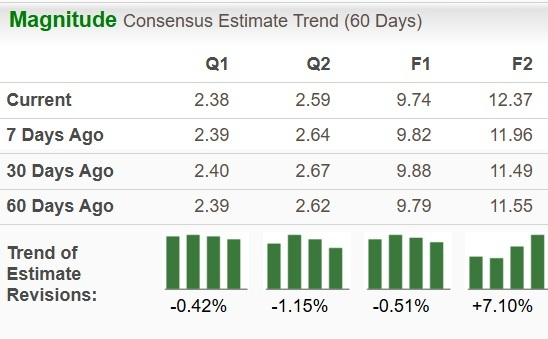
The Zacks Consensus Estimate for GNRC earnings for 2026 has seen a marginal downward revision over the past 60 days.
Image Source: Zacks Investment Research
GNRC currently has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Generac Holdings Inc. (GNRC): Free Stock Analysis Report
Caterpillar Inc. (CAT): Free Stock Analysis Report
Cummins Inc. (CMI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).