

AMN Healthcare Services, Inc. AMN is well positioned for growth in the coming quarters, courtesy of its broad array of services. The optimism is led by rising healthcare staffing demand, expanding technology-enabled workforce solutions and growth opportunities in higher-margin technology and language services. However, persistent pricing competition, weakness in its physician and technology businesses, and earnings normalization and execution risks may weigh on its performance.
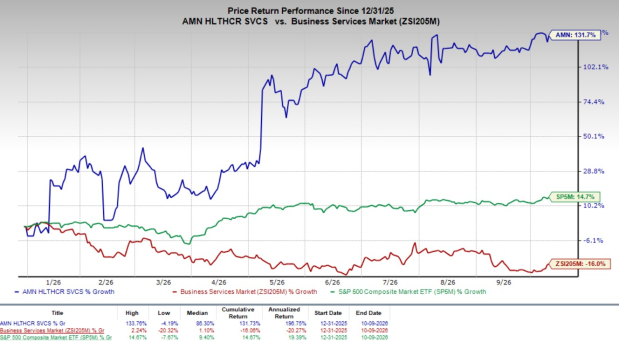
Shares of this Zacks Rank #3 (Hold) company have surged 131.7% year to date, outperforming the industry's 16% decline and the S&P 500’s 14.7% rise.
This renowned player in the healthcare total talent services space has a market capitalization of $1.41 billion. The company projects 144.1% year-over-year earnings growth for 2026 and expects to witness continued improvements in its business. AMN Healthcare surpassed the Zacks Consensus Estimate in the trailing four quarters, delivering an average earnings surprise of 96.63%.
Image Source: Zacks Investment Research
Factors Favoring AMN Stock
Rising Healthcare Staffing Demand: AMN Healthcare is positioned to benefit from persistent healthcare workforce shortages, supported by an aging population, rising chronic disease prevalence and physician supply constraints. The projected shortage of up to 86,000 physicians by 2036 highlights the need for flexible staffing solutions. AMN's second-quarter 2026 Nurse and Allied Solutions revenues grew 11% year over year to $422 million. Travel nurse and allied volumes increased 6% and 7%, respectively, marking their highest growth rates in four years. Management expects both categories to deliver volume growth exceeding 10% in the third quarter, supporting continued momentum.
Expanding Technology-Enabled Workforce Solutions: AMN's investments in automation, artificial intelligence and workforce analytics strengthen its competitive positioning. Its Passport application surpassed 400,000 users in the second quarter of 2026, increasing 33% year over year, while monthly active users rose more than 50%. The acquisition of Jaide Health expands AI-enabled language interpretation services, while WorkWise enhancements improve workforce optimization capabilities. Furthermore, AMN's research covering more than 2,000 hospitals found that 11 of 12 digital investment measures were associated with better patient experiences. These developments reinforce the company's ability to address evolving healthcare workforce needs through integrated technology and staffing services.
Expanding Higher-Margin Technology and Language Services: AMN can strengthen its competitive positioning by expanding specialized services beyond traditional staffing, particularly language interpretation and workforce management solutions. These offerings help hospitals address communication barriers, streamline staffing processes and improve operational efficiency. As healthcare providers increasingly prioritize coordinated workforce management and patient experience, AMN's integrated service portfolio could support deeper client relationships, diversify revenue sources and improve its business mix. Recent acquisitions of Jaide Health and ESSENTIAL Leadership Assessment further expand its AI-enabled language access and leadership advisory capabilities, creating opportunities to deepen client relationships and capture demand for specialized workforce solutions.
Downsides of AMN Stock
Persistent Pricing Competition: Intense competition across healthcare staffing and workforce technology markets continues to constrain pricing opportunities. Despite rising travel nurse demand, AMN has not experienced sustained bill-rate increases. Management noted that a larger supplier base is limiting pricing recovery. Language services pricing declined 8% year over year in the second quarter of 2026, contributing to an 8% revenue decline despite stable volumes. Management expects pricing compression to continue through the remainder of 2026, limiting revenue growth and profitability.
Weakness in Physician and Technology Businesses: Uneven performance across AMN's operating segments remains a concern. Physician and Leadership Solutions revenues declined 6% year over year to $165 million in the second quarter of 2026, reflecting an 8% contraction in locum tenens revenues. Technology and Workforce Solutions revenues fell 15% to $87 million, while vendor management system revenues declined 20%. Management projects third-quarter revenue declines of 5%-7% and 11%-13% for these segments, respectively. Continued weakness could offset growth in Nurse and Allied Solutions and constrain consolidated performance.
Earnings Normalization and Execution Risks: AMN's second-quarter 2026 profitability benefited from approximately $27 million in favorable revenue adjustments, which added 370 basis points to adjusted EBITDA margin. These benefits are not expected to recur in the third quarter. Management projects an adjusted EBITDA margin of 6.5%-7%, compared with 10.9% in the second quarter. International nurse growth also faces visa interview delays, potentially limiting expansion in 2027. The competitive renewal process for its Kaiser contract, which expires at the end of 2026, creates additional uncertainty surrounding future revenues and contract terms.
AMN Healthcare Services Inc Price
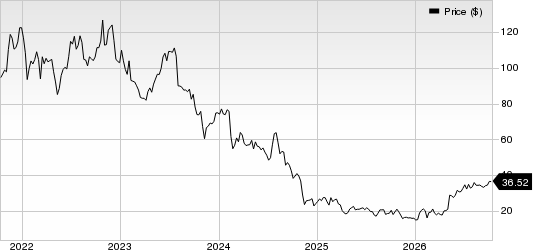
AMN Healthcare Services Inc price | AMN Healthcare Services Inc Quote
Estimate Trend
AMN Healthcare has been witnessing a positive estimate revision trend for 2026. Over the past 60 days, the Zacks Consensus Estimate for its earnings per share has improved 7.1% to $3.32.
The Zacks Consensus Estimate for third-quarter 2026 revenues and earnings per share is pegged at $648 million and 22 cents, respectively, suggesting 2.1% growth and a 43.6% decline from the year-ago reported numbers.
Key Picks
Some better-ranked stocks from the broader medical space are OPKO Health OPK, Globus Medical GMED and Merit Medical Systems MMSI.
OPKO Health, currently flaunting a Zacks Rank #1 (Strong Buy), reported a second-quarter 2026 adjusted loss of 1 cent per share, which surpassed the Zacks Consensus Estimate by 87.5%. Revenues of $163.6 million beat the Zacks Consensus Estimate by 24.7%. You can see the complete list of today’s Zacks #1 Rank stocks here.
OPK has an estimated earnings growth rate of 23.3% for 2026. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 95.1%.
Globus Medical, currently carrying a Zacks Rank #2 (Buy), reported a second-quarter 2026 adjusted EPS of $1.34, which surpassed the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million beat the Zacks Consensus Estimate by 0.4%.
GMED has an estimated long-term earnings growth rate of 12.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 27.9%.
Merit Medical Systems, carrying a Zacks Rank #2 at present, reported second-quarter 2026 adjusted EPS of $1.19, which beat the Zacks Consensus Estimate by 23.9%. Revenues of $418.8 million surpassed the Zacks Consensus Estimate by 3.5%.
MMSI has an estimated long-term earnings growth rate of 10.4%. MMSI’s earnings surpassed estimates in the trailing four quarters, the average surprise being 14.1%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
AMN Healthcare Services Inc (AMN): Free Stock Analysis Report
Merit Medical Systems, Inc. (MMSI): Free Stock Analysis Report
OPKO Health, Inc. (OPK): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).