

Quanta Services, Inc. PWR has delivered impressive stock market performance in 2026, supported by accelerating investments in electric infrastructure, power generation, data centers and grid modernization. Strong project demand, record backlog and improving profitability have strengthened investor confidence. However, following its substantial rally, the stock's elevated valuation raises questions about the sustainability of further gains.
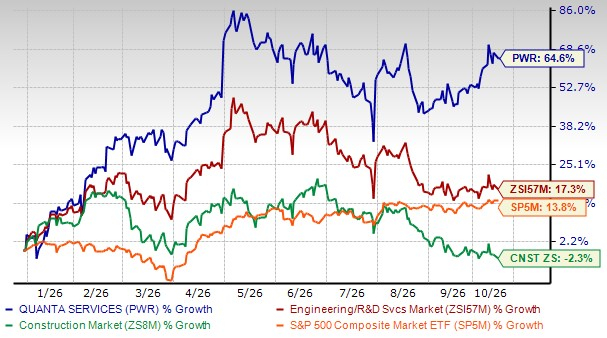
Quanta's shares have surged 64.6% year to date (YTD), significantly outperforming the Zacks Engineering - R and D Services industry's 17.3% growth. The stock has also outpaced the Zacks Construction sector, which declined 2.3%, and the S&P 500 Index, which advanced 13.8% during the same period.
PWR Stock’s YTD Price Performance
Image Source: Zacks Investment Research
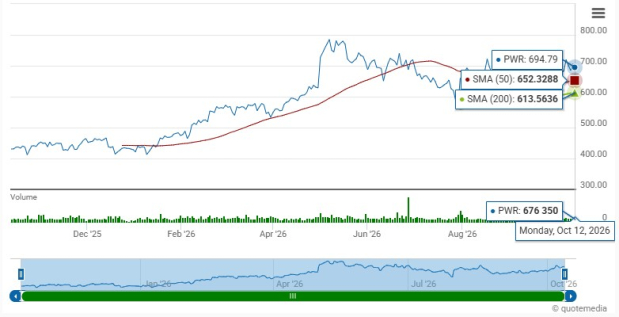
PWR is trading above its 50-day and 200-day moving averages, indicating sustained positive momentum. The rally reflects improving earnings expectations and confidence in Quanta's ability to capitalize on expanding infrastructure spending.
PWR Trades Above 50-Day, Above 200-Day SMAs
Image Source: Zacks Investment Research
Infrastructure Investment Strengthens Quanta's Growth Prospects
Quanta continues to benefit from increasing electricity demand, aging transmission infrastructure and investments in grid reliability. Utilities are expanding generation capacity, upgrading transmission networks and investing in grid modernization to accommodate electrification and growing power requirements.
Demand from artificial intelligence (AI), hyperscale data centers and advanced manufacturing facilities is creating additional opportunities. These projects require extensive electrical, mechanical and power infrastructure, supporting Quanta's expanding presence in technology and large-load markets.
The company's Electric Infrastructure Solutions segment reported 44% year-over-year revenue growth in second-quarter 2026, with operating margin reaching 11.5%. Its Underground Utility and Infrastructure Solutions segment recorded 31% revenue growth, with operating margin improving to 9.1%. These results highlight strong demand and operational execution.
Quanta's total backlog reached a record $53.4 billion at June 2026-end, including $32.3 billion scheduled within 12 months. Electric Infrastructure backlog stood at $43.8 billion, strengthening visibility into future revenues. The company also expects substantial opportunities from multi-year utility and power generation programs.
Acquisitions and Operating Strength Support Further Expansion
Strategic acquisitions are another important growth driver. During the second quarter and July 2026, Quanta acquired Phalcon, Enerfab, Percheron and PSD, strengthening its electrical, mechanical, fabrication and engineering capabilities.
These businesses broaden Quanta's geographic presence and improve its ability to execute complex infrastructure projects. Management expects the acquisitions to contribute approximately $1.2-$1.4 billion in revenues and $120-$140 million in adjusted EBITDA during 2026.
Quanta's self-performing workforce provides additional advantages by improving project execution, resource utilization and scheduling reliability. Its growing manufacturing capabilities, including the Hyosung HICO joint venture for high-voltage circuit breakers, should also strengthen supply-chain support.
Strong second-quarter performance prompted management to raise its full-year 2026 revenue guidance to $39.3-$39.7 billion and adjusted earnings per share (EPS) expectations to $16.45-$16.95. Free cash flow guidance is expected to be between $2 and $2.5 billion, providing financial flexibility for continued expansion.
Higher Earnings Estimates Reinforce PWR's Outlook
Analysts have become increasingly optimistic about Quanta's earnings prospects. Over the past 60 days, the Zacks Consensus Estimate for 2026 EPS has increased to $16.70 from $16.43, while the 2027 estimate rose to $19.41 from $19.23.
PWR’s EPS Estimate Revision Trend
Image Source: Zacks Investment Research
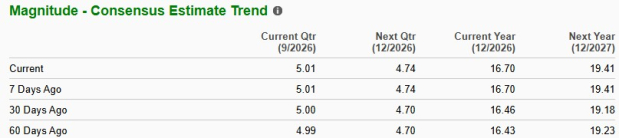
The revised estimates imply year-over-year earnings growth of 55.4% in 2026 and 16.2% in 2027. The Zacks Consensus Estimate for revenue indicates growth of 38.4% and 14.8% for 2026 and 2027, respectively. Importantly, the absence of downward EPS revisions during this period indicates improving confidence in the company's growth trajectory.
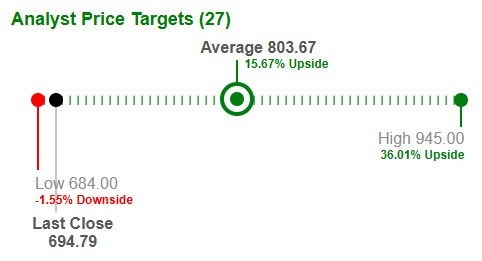
Wall Street sentiment remains favorable. Quanta has an average brokerage recommendation of 1.29, with 24 of 28 brokerage firms assigning Strong Buy recommendations. The average price target of $803.67 indicates potential upside of 15.7% from the last closing price.
Image Source: Zacks Investment Research
Premium Valuation and Execution Risks Warrant Caution
Despite these favorable developments, Quanta's substantial share price appreciation has pushed its valuation to elevated levels.
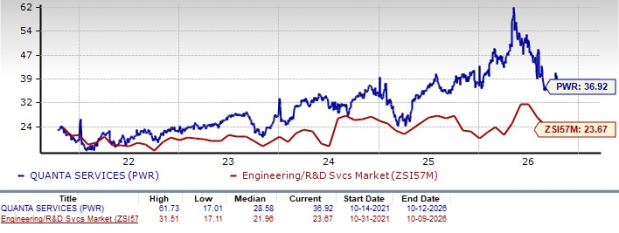
PWR currently trades at 36.92X forward 12-month earnings, considerably above the industry's 23.67X multiple and its five-year median of 28.58X. Although the valuation remains within its five-year range of 17.01X-61.73X, the premium suggests that investors have already priced in considerable earnings growth.
PWR Valuation vs Industry - P/E (F12M)
Image Source: Zacks Investment Research
The company also faces execution-related challenges. Large infrastructure projects involve regulatory approvals, permitting requirements, weather disruptions and potential supply-chain constraints. Skilled labor shortages, wage inflation and higher material costs could pressure margins.
Furthermore, acquisition integration and the growing complexity of large-scale projects introduce operational risks. Management expects seasonal moderation in Electric Infrastructure margins during the fourth quarter, highlighting potential quarterly variability.
How Does Quanta Compare With Its Competitors?
Quanta competes with MasTec MTZ, MYR Group MYRG and Primoris Services PRIM across several infrastructure markets.
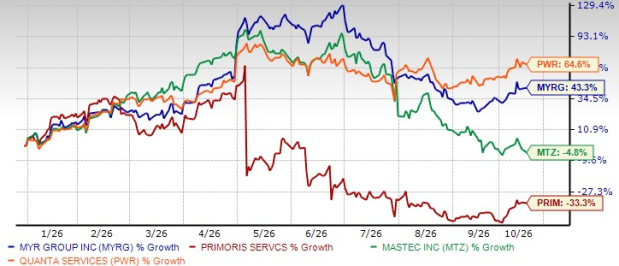
MasTec provides electric transmission, renewable energy and communications infrastructure services. MasTec shares have lost 4.8% YTD, significantly underperforming Quanta. MasTec trades at 17.33X forward earnings, indicating a substantial valuation discount.
MYR Group specializes in electrical construction, transmission, distribution and substation projects. MYR Group shares have gained 43.3% YTD, reflecting favorable utility infrastructure demand. However, MYR Group has trailed Quanta's rally. MYR Group trades at 22.88X forward earnings, below Quanta's multiple.
Primoris Services operates across power delivery, utility infrastructure, renewable energy and pipeline construction. Primoris Services shares have plunged 33.3% YTD, indicating weaker stock performance. Primoris Services trades at 18.75X forward earnings, also considerably below Quanta.
While Quanta has delivered stronger shareholder returns, its valuation premium relative to all three competitors increases the importance of sustained earnings growth.
PWR vs Peer Price Performance (YTD)
Image Source: Zacks Investment Research
Should Investors Hold PWR Stock After Its Rally?
Quanta remains well-positioned to benefit from sustained infrastructure investment, expanding electricity requirements and growing data center demand. Record backlog, strategic acquisitions, improving earnings estimates and strong project execution support its medium-term growth outlook.
However, the stock's elevated valuation, substantial YTD gains and exposure to execution risks limit its near-term risk-reward appeal. Although favorable infrastructure demand could support additional upside, much of the expected growth appears reflected in the share price.
Given these competing factors, Quanta's Zacks Rank #3 (Hold) supports maintaining existing positions rather than aggressively pursuing the stock following its sharp rally. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Quanta Services, Inc. (PWR): Free Stock Analysis Report
MYR Group, Inc. (MYRG): Free Stock Analysis Report
Primoris Services Corporation (PRIM): Free Stock Analysis Report
MasTec, Inc. (MTZ): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).