

Norfolk Southern Corporation NSC is scheduled to release third-quarter 2026 results on Oct. 22, before market open.
The railroad exits the September-end quarter amid inflationary cost pressure, network-efficiency challenges and uncertainty surrounding parts of the freight market. Higher wages, competitive pressure following the merger announcement and softer international intermodal trends might have weighed on profitability despite strength in select end markets.
The Zacks Consensus Estimate for NSC’s third-quarter 2026 earnings has been revised downward by 0.57% over the past 60 days to $3.48 per share. The consensus mark for earnings implies a 5.45% rise from the year-ago actuals. The Zacks Consensus Estimate for NSC's third-quarter 2026 revenues is pegged at $3.46 billion, indicating an increase of 11.6% year over year.
Norfolk Southern has an encouraging earnings surprise history. The company’s earnings outpaced the Zacks Consensus Estimate in each of the trailing four quarters, delivering an average beat of 8.54%.
Norfolk Southern Corporation Price and EPS Surprise
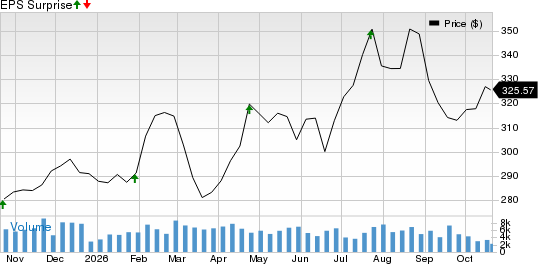
Norfolk Southern Corporation price-eps-surprise | Norfolk Southern Corporation Quote
Factors Likely to Have Influenced NSC’s Q3 Performance
Higher Labor Costs: Wage inflation is likely to have pressured Norfolk Southern’s third-quarter expenses. Management indicated that an approximately 4% wage increase took effect in July, which was expected to temper some of the sequential cost benefits entering the quarter.
Competitive Volume Pressure: The competitive environment associated with Norfolk Southern’s proposed merger is likely to have remained a headwind. The company specifically noted that the enhanced competitive environment following the merger announcement was expected to adversely affect volumes in the short and medium term. Management also acknowledged that earlier share losses affected intermodal growth, creating another difficult comparison for the business.
International Intermodal Uncertainty: Tariff and trade uncertainty might have constrained international intermodal volumes. While domestic intermodal demand benefited from tighter trucking capacity, management noted that trade-related uncertainty continued to weigh on international volumes.
Network and Cost Challenges: Higher volumes and network disruptions had previously placed pressure on crew resources and network fluidity. Although operating metrics were improving entering the third quarter, management was still focused on reducing terminal dwell, improving train velocity and addressing resource constraints.
Inflationary pressure also remained evident across compensation, purchased services and materials, which could have limited margin improvement.
What Our Model Says About NSC
Our proven model does not conclusively predict an earnings beat for Norfolk Southern this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. But that is not the case here.
Norfolk Southern has an Earnings ESP of -0.10% and a Zacks Rank #3 at present. You can uncover the best stocks to buy or sell before they're reported with our Earnings ESP Filter.
NSC’s Q2 Highlights
Norfolk Southern reported adjusted second-quarter 2026 earnings of $3.52 per share, which increased 7% year over year and surpassed the Zacks Consensus Estimate of $3.23 by 9%. Railway operating revenues rose 11% to a record $3.47 billion, beating the consensus mark of $3.32 billion by 4.4%.
The top-line gain reflected 4% volume growth, stronger revenue per unit and higher fuel surcharges. Total units reached 1.86 million, while adjusted income from railway operations increased 5% to $1.20 billion.
Stocks to Consider
Here are a few stocks from the broader Zacks Transportation sector that investors may consider, as our model shows that they have the right combination of elements to beat on earnings this reporting cycle.
Old Dominion Freight Line ODFL has an Earnings ESP of +0.25% and a Zacks Rank #2 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
ODFL is scheduled to report third-quarter 2026 earnings on Oct. 28. The Zacks Consensus Estimate for third-quarter 2026 earnings has been revised upward by 0.63% over the past 60 days. ODFL’s earnings beat the Zacks Consensus Estimate in each of the preceding four quarters, with the average beat being 6.71%.
Kirby Corporation KEX has an Earnings ESP of +1.87% and a Zacks Rank #3 at present. KEX is scheduled to report third-quarter 2026 earnings on Oct. 28.
The Zacks Consensus Estimate for third-quarter 2026 earnings has been revised upward by 0.51% to $1.96 per share over the past 60 days. KEX’s earnings beat the Zacks Consensus Estimate in three of the preceding four quarters and missed the mark on the other occasion. The average beat is 2.86%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Norfolk Southern Corporation (NSC): Free Stock Analysis Report
Old Dominion Freight Line, Inc. (ODFL): Free Stock Analysis Report
Kirby Corporation (KEX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).