

Alaska Air Group, Inc. ALK reported third-quarter 2026 adjusted earnings of 36 cents per share, excluding certain tax impacts, beating the Zacks Consensus Estimate of 35 cents by 2.9%. The company had reported adjusted earnings of $1.05 per share a year earlier. Higher fuel expenses weighed on profitability despite strong revenue momentum.
Operating revenues increased 14.4% year over year to $4.30 billion but missed the consensus mark of $4.31 billion marginally by 0.1%. Revenue per available seat mile or RASM, rose 11.7%, supported by strong yields, premium demand and loyalty revenues.
Alaska Air Group, Inc. Price, Consensus and EPS Surprise
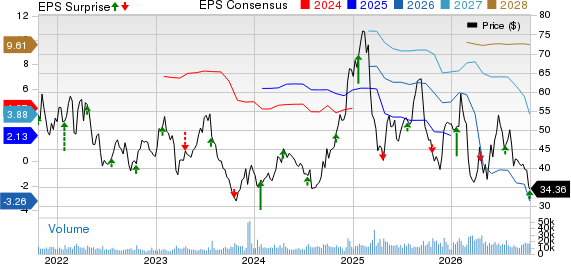
Alaska Air Group, Inc. price-consensus-eps-surprise-chart | Alaska Air Group, Inc. Quote
ALK Benefits From Diversified Revenue Growth
Passenger revenues increased 13.5% year over year to $3.89 billion. Loyalty program other revenues rose 31.5% year over year to $263 million, while cargo and other revenues advanced 12.7% to $160 million.
Premium revenues grew approximately 25% year over year, representing more than 36% of total revenues. Loyalty program cash remuneration increased 21% to $721 million, while managed corporate revenues jumped 30% year over year. Diversified revenues, representing revenues outside the main cabin, accounted for 54% of the company's total revenues.
Alaska Air Sees Strong Yields Despite Softer Traffic
Consolidated traffic, measured in revenue passenger miles, remained essentially flat year over year, while capacity increased 2.4%. With capacity growth outpacing traffic, the consolidated load factor declined 2 percentage points to 82.8%.
Passenger volumes decreased 1.1% year over year to 15.7 million. However, yield increased 13.4% to 18.73 cents, while passenger revenue per available seat mile rose 10.9% year over year to 15.52 cents.
Revenue performance reflected improving pricing trends, with September yield increasing approximately 17% year over year. The gains came despite headwinds in Hawaii, investments in strategic growth markets and rapid international expansion.
ALK Faces a Sharp Increase in Fuel Expenses
Total operating expenses increased 16.8% year over year to $4.23 billion, outpacing revenue growth. Aircraft fuel expenses rose 59.5% year over year to $1.21 billion as economic fuel cost climbed 57% to $3.94 per gallon from $2.51. Fuel consumption increased 1.7%.
Wages and benefits rose 5% year over year to $1.29 billion, while landing fees and other rentals increased 9%. Aircraft maintenance expenses climbed 8% year over year, while selling expenses and food and beverage service costs each advanced 10%.
Other operating expenses increased 16% year over year, further pressuring profitability. These increases more than offset a decline in special-item costs.
Alaska Air Keeps Non-Fuel Unit Costs in Check
Cost per available seat mile excluding fuel, freighter costs, performance-based pay and special items increased 4.4% to 11.46 cents from 10.98 cents a year ago.
The increase was within management's prior expectation for low-to-mid-single-digit growth. Adjusted operating expenses, excluding these items, rose to $2.87 billion from $2.68 billion.
ALK's Profitability Weakens Under Fuel Pressure
Adjusted pretax income declined to $49 million from $173 million a year earlier. Adjusted pretax margin contracted to 1.1% from 4.6%. Adjusted net loss totaled $35 million compared to adjusted net income of $123 million in the prior-year quarter.
On a reported basis, operating income declined 44.6% year over year to $82 million. GAAP net loss totaled $147 million or $1.32 per share compared to net income of $73 million or 62 cents per share, a year ago.
A cumulative tax adjustment related to previously recognized first-half losses reduced third-quarter adjusted earnings by 67 cents per share.
Alaska Air Maintains Liquidity Amid Rising Leverage
Operating cash flow totaled $149 million during the third quarter and $755 million for the first nine months of 2026. The company ended September with $3.3 billion in available liquidity.
Cash and cash equivalents were $835 million, while marketable securities totaled $1.40 billion. Long-term debt and finance leases, including current maturities, reached $6.16 billion.
Adjusted net debt to EBITDAR increased to 5.5 times from 2.9 times at year-end 2025, while debt to capitalization rose to 66% from 59%.
ALK Projects a Fourth-Quarter Loss on Higher Fuel Costs
For the fourth quarter of 2026, Alaska Air expects an adjusted loss of $2-$2.50 per share. Capacity is projected to increase 1-1.5%, with growth concentrated in international operations.
Unit revenues are expected to rise in the low double digits, while non-fuel unit costs are projected to increase in the mid-single digits. The outlook assumes an economic fuel cost of $4.65-$4.85 per gallon.
For full-year 2026, management anticipates an adjusted loss of $5-$5.50 per share, reflecting $1.8 billion in fuel expenses above its initial plan.
Currently, ALK has a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Q3 Performance of Other Transportation Companies
Delta Air Lines DAL reported third-quarter 2026 earnings (excluding 57 cents from non-recurring items) of $1.72 per share, missing the Zacks Consensus Estimate of $1.80 by 4.44%. Earnings increased year over year despite sharply higher fuel costs and rising non-fuel expenses.
Adjusted revenues climbed 16% year over year to $17.59 billion but missed the consensus estimate of $17.74 billion by 0.9%. Broad demand strength and healthy yields lifted adjusted total revenue per available seat mile or TRASM, 15%, while premium and diversified revenue streams continued to expand.
J.B. Hunt Transport Services, Inc. JBHT reported third-quarter 2026 earnings of $1.82 per share, up 3.4% from $1.76 a year ago. The figure beat the Zacks Consensus Estimate of $1.81 by 0.6%.
Operating revenues climbed 20.4% year over year to $3.68 billion and surpassed the consensus mark of $3.56 billion by 3.2%. Stronger pricing, an 8% increase in Intermodal loads and higher brokerage volumes supported growth. However, elevated driver-related expenses, fuel costs and insurance claims pressured profitability.
United Airlines Holdings, Inc. UAL reported third-quarter 2026 adjusted earnings of $2.54 per share, down 8.6% year over year and below the Zacks Consensus Estimate of $2.60 by 2.3%. Higher fuel expenses weighed on profitability despite strong revenue growth.
Operating revenues rose 17.4% to $17.88 billion but missed the consensus mark of $17.91 billion by 0.2%. A 15.9% increase in total revenue per available seat mile or TRASM, supported the top line, driven by strength across premium, loyalty and contracted business revenues.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Alaska Air Group, Inc. (ALK): Free Stock Analysis Report
Delta Air Lines, Inc. (DAL): Free Stock Analysis Report
United Airlines Holdings Inc (UAL): Free Stock Analysis Report
J.B. Hunt Transport Services, Inc. (JBHT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).