

Knight-Swift Transportation Holdings Inc. KNX reported impressive third-quarter 2026 results, wherein both earnings and revenues surpassed the Zacks Consensus Estimate. Stronger truckload pricing and improved network efficiency supported earnings growth.
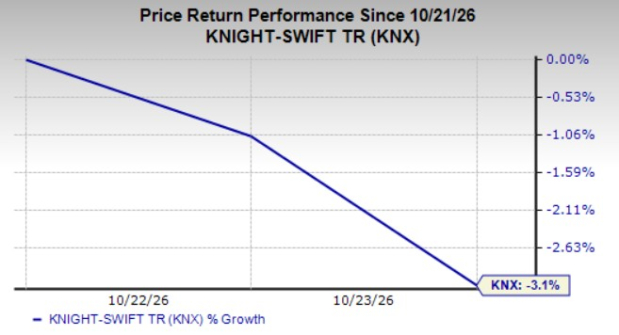
However, the better-than-expected results failed to impress the market, as the stock has declined 3.1% since its earnings release on Oct. 21.
Image Source: Zacks Investment Research
Adjusted earnings of 83 cents per share beat the Zacks Consensus Estimate of 75 cents by 10.7% and surged 159.4% year over year. Total revenues of $2.20 billion surpassed the consensus estimate of $2.14 billion by 2.9% and increased 14.2% year over year. Truckload revenue per loaded mile, excluding fuel surcharge and intersegment transactions, increased 9.7%.
Knight-Swift Transportation Holdings Inc. Price, Consensus and EPS Surprise
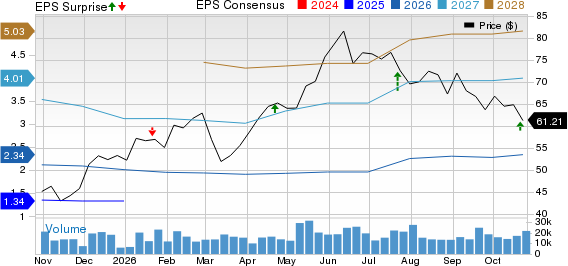
Knight-Swift Transportation Holdings Inc. price-consensus-eps-surprise-chart | Knight-Swift Transportation Holdings Inc. Quote
KNX's Consolidated Profitability Improves
Revenues, excluding truckload and less-than-truckload (LTL) fuel surcharge, increased 7.7% year over year to $1.85 billion. Operating income surged 255.1% to $178.71 million, while adjusted operating income advanced 87.4% to $198.55 million.
The consolidated operating ratio (operating expenses as a percentage of revenues) improved 550 basis points to 91.9%. The adjusted operating ratio improved 450 basis points to 89.3%, reflecting pricing and network efficiency gains. Adjusted net income increased 164.9% to $135.87 million.
Knight-Swift's Truckload Margins Expand
Truckload total revenues increased 14% year over year to $1.41 billion. Revenues, excluding fuel surcharge and intersegment transactions, rose 6.5% to $1.15 billion, despite a 3% decline in loaded miles.
Adjusted operating income surged 202.3% to $124.63 million. The adjusted operating ratio improved 700 basis points to 89.2%, benefiting from stronger pricing, improved loaded miles per tractor and a 170-basis-point reduction in empty miles.
Average revenue per tractor increased 10.9% to $56,419, while average tractor count declined 4% to 20,470. Revenues per total mile, excluding fuel surcharge, increased 12.2%, outpacing the 3.8% rise in adjusted cost per mile.
U.S. Xpress continued improving profitability, with its over-the-road division achieving a mid-90s adjusted operating ratio.
KNX's LTL Revenues Rise, Margins Face Pressure
LTL total revenues increased 10.1% year over year to $434.52 million. Revenues, excluding fuel surcharge, edged up 0.4% to $341.70 million, supported by a 4% increase in revenue per shipment, partially offset by a 1.4% decline in daily shipments.
Daily tonnage increased 3.3%, while weight per shipment and length of haul rose 4.8% and 6.2%, respectively, reflecting improvements in freight mix.
Adjusted operating income declined 8.4% to $29.37 million, primarily owing to lower gains on asset sales. The adjusted operating ratio deteriorated 80 basis points to 91.4%.
Knight-Swift's Logistics and Intermodal Performance
Logistics revenues declined 1% year over year to $138.97 million. Revenue per load jumped 46.7%, offset by a 32.6% decline in load count. Adjusted operating income grew 19.6% to $9.57 million, while the adjusted operating ratio improved 120 basis points to 93.1%.
Logistics gross margin expanded 110 basis points year over year and 350 basis points sequentially to 18.9%, benefiting from contractual pricing improvements and easing capacity costs.
Intermodal revenues climbed 30.6% to $122.88 million, supported by a 13.3% increase in load count and a 15.2% rise in revenue per load.
The segment generated adjusted operating income of $2.76 million compared with $0.16 million a year ago. Its adjusted operating ratio improved 200 basis points to 97.8%.
KNX's Other Businesses Deliver Strong Growth
All Other Segments' revenues increased 41.8% year over year to $126 million, driven by growth in warehousing and independent contractor support services.
Operating income rose 68.4% to $19.50 million. The improvement reflected revenue growth and a more favorable comparison with the prior-year loss contingency, partially offset by accounts receivable securitization costs.
Knight-Swift's Liquidity and Cash Flow Improve
Knight-Swift exited September with $1.7 billion in unrestricted cash and available liquidity. Net debt stood at $2.1 billion, while stockholders' equity totaled $7.1 billion.
Operating cash flow for the first nine months of 2026 increased to $799.88 million from $543.43 million a year ago. Free cash flow reached $373.2 million after net capital expenditures of $426.7 million.
KNX's Fourth-Quarter Outlook Signals Growth
For fourth-quarter 2026, KNX expects adjusted earnings of 78-84 cents per share. Truckload revenues, excluding fuel surcharge, are projected to increase by a low-double-digit percentage, with the adjusted operating ratio improving 650-750 basis points year over year.
LTL revenues, excluding fuel surcharge, are expected to grow by a high-single-digit to low-double-digit percentage. Intermodal revenues are projected to increase 25-30%, while Logistics revenues are expected to remain flat.
Management narrowed its full-year 2026 net cash capital expenditure forecast to $600-$625 million from $600-$650 million.
Currently, KNX carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Q3 Performance of Other Transportation Companies
Alaska Air Group, Inc. ALK reported third-quarter 2026 adjusted earnings of 36 cents per share, excluding certain tax impacts, beating the Zacks Consensus Estimate of 35 cents by 2.9%. The company had reported adjusted earnings of $1.05 per share a year earlier. Higher fuel expenses weighed on profitability despite strong revenue momentum.
Operating revenues increased 14.4% year over year to $4.30 billion but missed the consensus mark of $4.31 billion marginally by 0.1%.
Wabtec Corporation WAB reported mixed third-quarter 2026 results, wherein earnings surpassed the Zacks Consensus Estimate, but revenues missed the same.
Quarterly earnings (excluding 41 cents from non-recurring items) of $2.83 per share beat the Zacks Consensus Estimate of $2.72 by 4.04% and increased 22% year over year. Revenues climbed 8.1% year over year to $3.12 billion but missed the consensus mark of $3.18 billion by 2%. The 12-month backlog increased 8.8% to $8.99 billion.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Knight-Swift Transportation Holdings Inc. (KNX): Free Stock Analysis Report
Alaska Air Group, Inc. (ALK): Free Stock Analysis Report
Wabtec (WAB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).