

Cameco Corporation CCJ raised its 2026 consolidated revenue outlook even as recent results showed weaker earnings, cash generation and production reliability. Stronger uranium pricing improves the top-line setup, but the revised guidance now places greater weight on execution through the rest of the year.
The key question is whether production recovery, purchased-material costs and a stronger Westinghouse finish can support the higher revenue range without leaving profitability and cash flow exposed to the same volatility seen in the first half.
Cameco Raises Its 2026 Revenue Expectations
Management raised 2026 consolidated revenue guidance to C$3.32-C$3.57 billion from C$3.13-C$3.37 billion. Uranium revenue guidance stands at C$2.7-C$2.9 billion, based on an expected average realized uranium price of C$91-C$96 per pound.
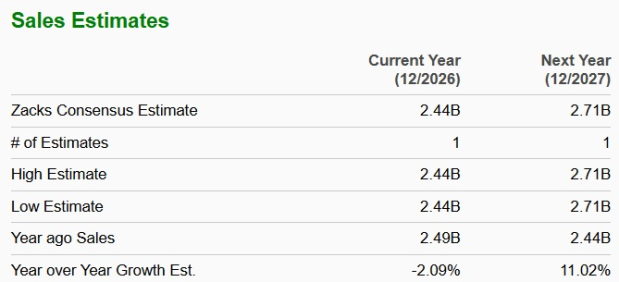
The Zacks Consensus Estimate for revenues for 2026 is currently pegged at $2.44 billion, suggesting a 2.1% year over year decline.
Image Source: Zacks Investment Research
Uranium deliveries remain projected at 29-32 million pounds. At the midpoint, uranium revenues would still decline about 2% from 2025 because of lower delivery volumes, so higher realized pricing is doing much of the work behind the revised outlook.
CCJ Needs Production Recovery to Support Guidance
Cameco maintained attributable uranium production guidance of 19.5-21.5 million pounds for 2026 despite operational disruptions at McArthur River, Key Lake and Cigar Lake. Second-quarter attributable uranium production fell 15% year over year to 3.9 million pounds.
Execution therefore remains central to the guidance. Key Lake has an extended maintenance shutdown planned for infrastructure installations and repairs, while reliable transportation and mine performance are necessary to keep production and delivery schedules on track.
Cameco’s Costs Could Dilute Stronger Pricing
The company raised its expected uranium average unit cost of sales to C$63-C$67.50 per pound from C$61.50-C$65. Higher purchased-material costs and the stronger U.S. dollar were among the factors behind the revised cost outlook.
Cameco also plans up to 3 million pounds of market purchases during 2026. That exposure matters because some market-related sales contracts have pricing ceilings while purchased uranium remains sensitive to prevailing market prices, potentially limiting the earnings benefit from stronger uranium prices.
CCJ Is Counting on a Stronger Westinghouse Finish
Cameco’s share of Westinghouse results fell 36% to C$284 million in the first half of 2026, reflecting the absence of the prior-year Dukovany project contribution. Management expects stronger Westinghouse performance and cash flows in the fourth quarter, making project milestones and timing important to the full-year result.
The broader nuclear investment backdrop remains active. Constellation Energy Corporation CEG recently received a conditional U.S. Department of Energy loan commitment of up to $5 billion to support potential nuclear uprates. Centrus Energy Corp. LEU is expanding uranium-enrichment capacity and signed a $900 million Department of Energy award tied to commercial-scale high-assay, low-enriched uranium production. These developments reinforce the industry demand theme surrounding Cameco’s uranium and reactor exposure.
CCJ’s Mixed Scores Raise the Bar for Execution
The raised revenue outlook improves the top-line picture, but it does not remove the need for consistent production, cost control and cash conversion. First-half operating cash flow fell 81% year over year to C$109 million, underscoring how timing and operating performance can diverge from revenue expectations.
CCJ currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Its VGM Score of F includes a Value Score of D, Growth Score of F and Momentum Score of B. The Zacks Rank points to a neutral near-term earnings-revision signal, while the Style Scores show stronger momentum than value or growth characteristics. Together, those signals support a measured view as investors watch whether execution catches up with the higher revenue outlook.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Cameco Corporation (CCJ): Free Stock Analysis Report
Constellation Energy Corporation (CEG): Free Stock Analysis Report
Centrus Energy Corp. (LEU): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).