

T-Mobile US, Inc. TMUS reported third-quarter 2026 earnings of $3.22 per share, which beat the Zacks Consensus Estimate of $2.86 by 12.59%. Earnings increased 33.6% year over year. Total revenues of $23.58 billion surpassed the consensus mark of $23.31 billion by 1.17% and rose 7.4% year over year.
The strong performance reflected continued service revenue growth, higher postpaid average revenue per account (ARPA) and solid customer additions. Postpaid ARPA increased 4.2% year over year to $155.73, highlighting improved customer monetization and growing adoption of premium rate plans.
TMUS Benefits From Strong Service Revenue Growth
T-Mobile generated total service revenues of $19.38 billion in the third quarter, up 6.2% from the year-ago period. Postpaid service revenues climbed 9.3% year over year to $16.27 billion, supported by higher average postpaid accounts following the UScellular and Metronet acquisitions and improved ARPA.
Equipment revenues increased 13.4% year over year to $3.93 billion, driven by higher average revenue per device sold, a richer mix of premium smartphones and increased manufacturer pricing. Higher device liquidation revenues also contributed to growth, partially offset by lower device sales volumes.
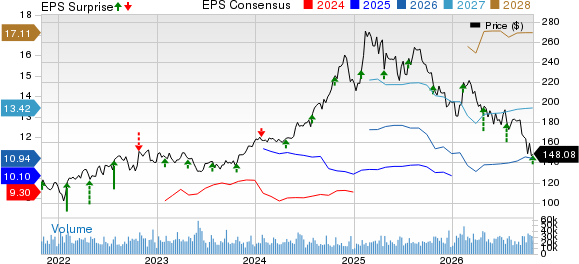
T-Mobile US, Inc. Price, Consensus and EPS Surprise
T-Mobile US, Inc. price-consensus-eps-surprise-chart | T-Mobile US, Inc. Quote
T-Mobile Expands Postpaid Accounts Amid Higher Churn
TMUS reported postpaid net account additions of 274,000 during the quarter compared with 396,000 a year ago. Total postpaid accounts increased to 34.97 million from 33.98 million in the prior-year quarter, reflecting continued customer base expansion despite slower net additions.
Postpaid account churn increased to 1.09% from 0.97% a year earlier, primarily due to a higher proportion of broadband-only accounts and the temporary impact of rate plan modernization. Meanwhile, ARPA benefited from higher fee revenues, increased customers per account and broader adoption of tax- and fee-exclusive plans.
TMUS Faces Higher Operating Expenses
T-Mobile's total operating expenses increased 2.8% year over year to $17.92 billion. Cost of services rose 4.7% to $3.01 billion, primarily reflecting higher wholesale network access costs, customer installation fee amortization and increased network maintenance expenses.
Cost of equipment sales increased 12.2% to $5.44 billion, reflecting higher device costs and a greater proportion of premium smartphones. Selling, general and administrative expenses remained relatively flat at $6.02 billion. Despite these pressures, operating income increased 25% year over year to $5.66 billion, supported by higher revenues and improved operating leverage.
T-Mobile Delivers Strong Profitability and Cash Flow
Core adjusted EBITDA increased 10.8% year over year to $9.62 billion, primarily driven by higher service revenues and equipment revenues, partially offset by increased equipment and service costs. Net income rose 27.3% to $3.46 billion, benefiting from improved operating performance.
Net cash provided by operating activities declined 1.6% year over year to $7.34 billion, reflecting higher working capital outflows. However, adjusted free cash flow increased 5.3% to $5.07 billion as cash capital expenditures declined 14% to $2.27 billion. During the quarter, T-Mobile returned approximately $3.5 billion to shareholders through $2.4 billion in share repurchases and $1.1 billion in dividends.
TMUS Strengthens Its Balance Sheet Position
T-Mobile ended the third quarter with total assets of $213.10 billion and cash and cash equivalents of $5.62 billion. Long-term debt declined to $77.32 billion from $79.65 billion at the end of 2025, reflecting debt reduction alongside continued investments in network infrastructure and spectrum.
Net debt, excluding tower obligations, stood at $80.3 billion at quarter-end. The net debt to trailing 12-month core adjusted EBITDA ratio improved to 2.2 times from 2.5 times in the year-ago quarter. Management continues to prioritize network investments, spectrum opportunities and shareholder returns in its capital allocation strategy.
T-Mobile Raises Profitability Outlook for 2026
Management now expects approximately one million postpaid net account additions for 2026. Core adjusted EBITDA guidance was narrowed and raised at the midpoint to $37.35-$37.45 billion from the previous range of $37.1-$37.5 billion, reflecting sustained service revenue growth and operating efficiency.
T-Mobile also raised its outlook for net cash provided by operating activities to $28.7-$28.8 billion from $28.4-$28.8 billion. Adjusted free cash flow guidance increased to $18.7-$18.8 billion from $18.4-$18.8 billion. Capital expenditure expectations remained unchanged at approximately $10 billion, while management increased its full-year postpaid ARPA growth expectation to approximately 3.5% from 2.5-3%.
Zacks Rank
T-Mobile currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Upcoming Releases
Arista Networks Inc. ANET is scheduled to release third-quarter 2026 earnings on Nov. 3. The Zacks Consensus Estimate for earnings is pegged at $1.08 per share, suggesting growth of 44% from the year-ago reported figure.
Arista has a long-term earnings growth expectation of 22.75%. The company delivered an average earnings surprise of 8.88% in the last four reported quarters.
Motorola Solutions, Inc. MSI is set to release third-quarter 2026 earnings Nov. 4. The Zacks Consensus Estimate for earnings is pegged at $4.41 per share, implying growth of 8.62% from the year-ago reported figure.
Motorola has a long-term earnings growth expectation of 10.55%. The company delivered an average earnings surprise of 7.17% in the last four reported quarters.
HubSpot, Inc. HUBS is scheduled to release third-quarter 2026 earnings on Nov. 4. The Zacks Consensus Estimate for earnings is pegged at $3.28 per share, suggesting growth of 23.31% from the year-ago reported figure.
HubSpot has a long-term earnings growth expectation of 21.25%. The company delivered an average earnings surprise of 6.13% in the last four reported quarters.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
T-Mobile US, Inc. (TMUS): Free Stock Analysis Report
Motorola Solutions, Inc. (MSI): Free Stock Analysis Report
Arista Networks, Inc. (ANET): Free Stock Analysis Report
HubSpot, Inc. (HUBS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).