

PTC Inc. PTC is scheduled to report fourth-quarter fiscal 2026 results on Nov. 4, after market close.
For the fiscal fourth quarter, PTC estimates revenues in the $630-$690 million band. Non-GAAP EPS is projected in the range of $1.63 to $2.21.
The Zacks Consensus Estimate for revenues is pegged at $657.6 million, down 26.4% from the year-ago reported number. The consensus estimate for earnings is pegged at $2.00 per share, down 42.4% from a year ago.
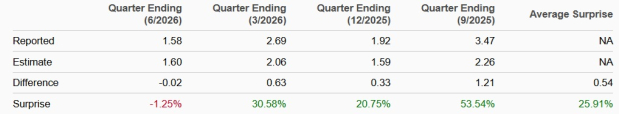
The company’s earnings beat the Zacks Consensus Estimate in three of the trailing four quarters, while missing once, with the average earnings surprise being 25.9%.
Image Source: Zacks Investment Research
Key Factors to Watch in PTC's Fiscal Q4 Earnings
PTC’s fiscal fourth-quarter performance is likely to have been aided by recurring revenue growth, demand for product lifecycle management (PLM) and computer-aided design (CAD) software, AI-related opportunities and cash flow momentum.
In October, PTC announced that it had entered into a definitive agreement to be acquired by Schneider Electric for $205 per share in cash, valuing PTC’s equity at approximately $22.6 billion. The transaction is expected to create a scaled industrial software and AI platform, with Schneider Electric targeting €250 million in annual cost synergies and approximately €800 million in revenue synergies. Following this development, PTC suspended its quarterly earnings conference calls and stopped providing quarterly and annual financial guidance.
PTC continues to see solid demand across its go-to-market initiatives and encouraging early traction for its AI offerings. Supported by strong momentum and promising growth opportunities, the company is likely to have entered the fiscal fourth quarter on solid footing and raised the midpoint of its full-year ARR growth guidance to 9.25%, reflecting confidence in its ability to deliver a strong finish to the year. PTC raised and narrowed its full-year ARR guidance, with the midpoint implying $214 million in net new ARR, reflecting strong go-to-market execution and improved pipeline visibility. It expects a boost in the fiscal fourth quarter, supported by healthy demand generation and the conversion of deferred ARR, with net new ARR (excluding Kepware and ThingWorx) projected at $79-$92 million.
AI remains a long-term growth opportunity for PTC. Manufacturers increasingly need reliable product data, engineering systems and connected workflows to deploy AI across product design, development, manufacturing and servicing. PTC's Intelligent Product Lifecycle strategy aims to combine its core CAD, PLM, ALM and SLM software with AI capabilities. Management highlighted increasing customer interest in AI and the need to modernize product-data foundations before businesses can effectively deploy AI applications.
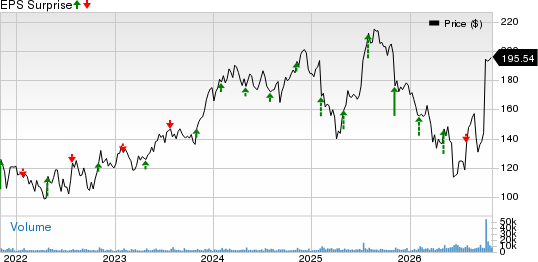
PTC Inc. Price and EPS Surprise
PTC Inc. price-eps-surprise | PTC Inc. Quote
Cash flow is another key metric for evaluating PTC's business quality. In the fiscal third quarter, operating cash flow increased 7% year over year to $261 million, while free cash flow rose 3% to $249 million. However, PTC expects fiscal fourth quarter free cash flow of approximately $15 million, down year over year, primarily due to capital gains tax payments related to the Kepware and ThingWorx divestitures, which are expected to occur during the quarter.
Furthermore, PTC accelerated share repurchases in the fiscal third quarter, reflecting management's view that the stock was undervalued. After completing a $375 million accelerated share repurchase program and an additional $525 million of open market buybacks, the company now expects to buy back about $1.63 billion of shares in fiscal 2026. This is expected to reduce fully diluted shares outstanding from roughly 121 million to 116 million, supporting EPS growth and signaling confidence in PTC's long-term outlook.
Nonetheless, PTC faces strong competition across CAD, PLM and ALM markets as rivals target similar modernization and AI opportunities. Also, PTC needs $79-$92 million in sequential net new ARR in fiscal fourth quarter, up from $60 million in fiscal third quarter, to meet its full-year growth target. Delayed expansions and AI adoption timelines could hinder execution. Meanwhile, $525 million in share repurchases reduced cash to $351 million and increased debt to $1.42 billion, limiting financial flexibility if conversions are delayed.
What Our Model Uncovers About PTC
Our proven model does not predict an earnings beat for PTC this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy), or 3 (Hold) increases the odds of an earnings beat. This is not the case here.
PTC has an Earnings ESP of -1.75% and a Zacks Rank #2. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Stocks With the Favorable Combination
Here are three stocks you may want to consider, as our model shows that these have the right elements to post an earnings beat in this reporting cycle.
The Allstate Corporation ALL has an Earnings ESP of +5.25% and a Zacks Rank #3 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
ALL is scheduled to report quarterly earnings on Nov. 4. The Zacks Consensus Estimate for third-quarter 2026 earnings is pegged at $7.03, indicating a year-over-year decrease of 37.1%. ALL’s earnings beat estimates in each of the last four reported quarters.
Advanced Micro Devices, Inc. AMD has an Earnings ESP of +3.49% and a Zacks Rank #3 at present. AMD is scheduled to report quarterly figures on Nov. 3. The Zacks Consensus Estimate for AMD’s to-be-reported quarter’s earnings and revenues is pegged at $1.94 per share and $13.12 billion, respectively. Shares of AMD have skyrocketed 94.4% in the past year.
AMETEK AME has an Earnings ESP of +0.37% and a Zacks Rank #1. AMETEK is set to report third-quarter 2026 results on Nov. 3. The Zacks Consensus Estimate for AME’s to-be-reported quarter’s earnings and revenues is pegged at $2.12 per share and $2.16 billion, respectively. AMETEK shares have gained 17.4% year-to-date.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
PTC Inc. (PTC): Free Stock Analysis Report
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
The Allstate Corporation (ALL): Free Stock Analysis Report
AMETEK, Inc. (AME): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).