

Amkor Technology AMKR is gaining traction in advanced semiconductor packaging for artificial intelligence (AI), high-performance computing and automotive electronics. However, its valuation premium, recent share-price weakness and falling earnings estimates suggest investors should resist chasing the stock. While its long-term growth opportunities support retaining existing positions, near-term execution risks and substantial capital requirements warrant a measured approach.
AMKR’s Premium Valuation Warrants Patience
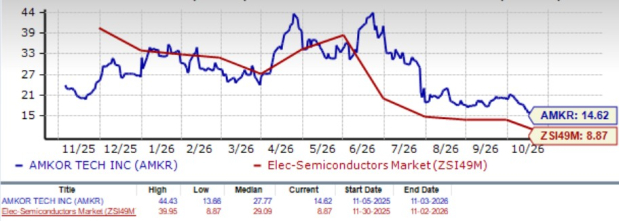
Amkor trades at 14.62X forward 12-month earnings compared with 8.87X for the Zacks Electronics - Semiconductors industry, a premium of approximately 62%. Although the stock remains below its one-year median P/E of 27.77X, its current valuation already reflects optimism surrounding advanced packaging and AI-related demand. Nevertheless, downward earnings estimate revisions and moderating growth expectations raise concerns about the sustainability of this premium. Its Value Score of A reflects favorable valuation metrics under the Zacks framework.
AMKR’s P/E F12M Ratio
Image Source: Zacks Investment Research
AMKR Stock Lags Industry and Key Peers
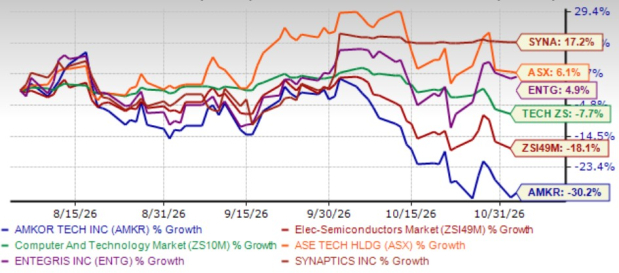
Over the past three months, AMKR’s shares declined 30.2%, underperforming the Zacks Electronics - Semiconductors industry’s 18.1% loss and the Computer and Technology sector’s 7.7% fall.
AMKR’s recent share-price performance also stands out against its peers, including ASE Technology Holding ASX, Entegris ENTG and Synaptics SYNA. Over the past three months, ASE Technology Holding’s shares gained 6.1%, Entegris returned 4.9% and Synaptics appreciated 17.2%. The stronger performance of ASE Technology Holding, Entegris and Synaptics, despite their different business models and semiconductor industry exposures, highlights relatively weaker investor sentiment toward Amkor.
Three-Months Price Comparison
Image Source: Zacks Investment Research
AI and Data Center Packaging Could Sustain Growth
Third-quarter 2026 Computing revenues increased 37% year over year and 25% sequentially to a record, helped by the ramp of Amkor's flagship high-density fan-out (HDFO) CPU program. Another hyperscaler HDFO CPU program began ramping in the quarter, while two 2.5D networking and data center programs were expected to come online in the fourth quarter. Management anticipates more than 50% year-over-year Computing growth in the fourth quarter.
Management also indicated that Computing revenues could grow more than 30% in 2026, with a similar or higher growth rate possible in 2027. These programs broaden Amkor's AI infrastructure opportunity and provide a potential multiyear growth driver. Its expanding HDFO and 2.5D capabilities could also strengthen its competitive positioning against companies such as ASE Technology Holding. Growing demand for advanced packaging could enable Amkor to capture a larger share of AI infrastructure spending and diversify its revenue base.
Richer Product Mix Is Improving Profitability
Third-quarter net sales were nearly flat year over year at $1.99 billion, but earnings rose to 76 cents from 51 cents per share. Gross margin expanded 400 basis points to 18.3%, while operating margin improved to 11.3% from 8% a year earlier. Management attributed gross margin expansion primarily to a richer mix of high-value advanced packaging, including products with lower material content.
Automotive and Industrial revenues advanced 37% year over year, supported by demand for advanced driver-assistance systems (ADAS), in-car computing and industrial products. This mix shift supports earnings resilience even as Communications remains exposed to smartphone demand. Communications accounted for 37% of quarterly sales, down from 51% a year earlier, while Computing increased its contribution to 26% from 19%.
The improving contribution from Computing and Automotive and Industrial provides evidence that Amkor is gradually diversifying beyond its traditional Communications exposure. A richer advanced-packaging mix and stronger contributions from higher-growth end markets could support further margin improvement. Nevertheless, component shortages and changes in customer production schedules remain potential constraints.
Customer Commitments Support Capacity Expansion
Amkor's long-term customer relationships and advance-payment arrangements provide greater visibility into future demand and help support its capacity expansion. Management stated that the company had executed advance-payment arrangements with a dozen customers since 2025, primarily supporting advanced-packaging capacity in Korea and Arizona.
Additionally, an October 2026 customer agreement is expected to provide approximately $1.3 billion in advance payments during 2027. These arrangements should help fund planned investments and reduce some of the near-term financing burden.
Phase 1 of the Arizona advanced-packaging and test campus is scheduled for completion by the end of 2027, while Phase 2 is expected to break ground in late 2027. Together, the two phases represent an estimated investment of $12 billion. The expansion, alongside ongoing investments in Korea and Vietnam, should strengthen Amkor's geographic footprint and ability to serve customers seeking advanced packaging and test capabilities.
Near-Term Outlook and Spending Remain Challenging
For fourth-quarter 2026, Amkor expects revenues of $1.9-$2 billion, gross margin of 18%-19% and earnings of 65-75 cents per share. Communications weakness, component shortages and the system-in-package migration from South Korea to Vietnam remain headwinds. Full-year capital expenditures are projected near $2.5 billion, with higher spending expected in 2027. Free cash flow was negative $319 million in the first nine months of 2026, versus negative $13 million a year earlier. At September-end, cash and short-term investments of $2.4 billion roughly matched total debt of $2.5 billion, while the top 10 customers accounted for 66% of third-quarter sales. This concentration makes disciplined execution important.
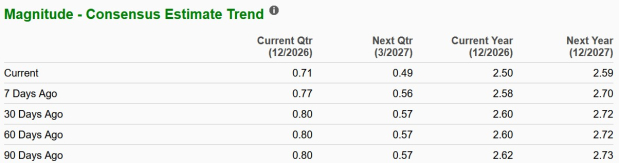
The Zacks Consensus Estimate for fourth-quarter 2026 earnings per share (EPS) fell to 71 cents from 80 cents over the past 30 days. The first-quarter 2027 EPS estimate fell to 49 cents from 57 cents. The full-year 2026 EPS estimate declined to $2.50 from $2.60, while the 2027 estimate slipped to $2.59 from $2.72.
Image Source: Zacks Investment Research
Conclusion
Amkor's expanding advanced-packaging pipeline, improving product mix and longer-term customer commitments provide sound reasons for existing investors to stay invested rather than sell after the pullback. However, the premium forward P/E, negative free cash flow, smartphone exposure and downward earnings revisions limit the case for aggressive buying.
Investors can hold AMKR while monitoring HDFO and 2.5D program execution, capacity utilization and a recovery in earnings estimates. A sustained improvement in free cash flow and evidence that new capacity can generate attractive returns would further strengthen the investment case. New buyers may prefer clearer evidence that heavy investments will translate into sustainable cash generation.
AMKR currently has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Amkor Technology, Inc. (AMKR): Free Stock Analysis Report
Entegris, Inc. (ENTG): Free Stock Analysis Report
Synaptics Incorporated (SYNA): Free Stock Analysis Report
ASE Technology Holding Co., Ltd. (ASX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).