

Sterling Infrastructure, Inc. STRL raised its 2026 revenue, earnings and EBITDA guidance after a third quarter that delivered large consensus beats and rapid E-Infrastructure expansion. The higher outlook extends the growth story but also raises the execution bar as the company scales.
The question is whether the revised targets mark a durable step higher in earnings power or leave less room for setbacks from margin mix, project timing and working-capital demands.
STRL's Q3 Beat Reset 2026 Expectations Higher
Third-quarter adjusted earnings reached $7.58 per share, up 118% year over year and 24.9% above the Zacks Consensus Estimate. Revenues surged 127% to $1.56 billion and exceeded the consensus mark by 33.8%, showing how quickly E-Infrastructure activity accelerated.
Sterling Infrastructure, Inc. Price and Consensus
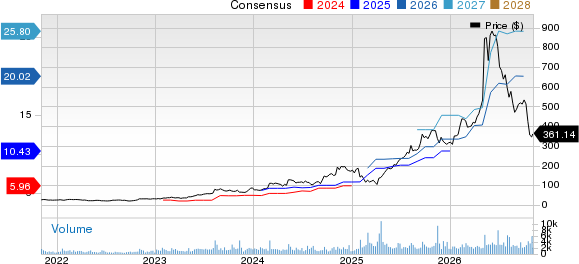
Sterling Infrastructure, Inc. price-consensus-chart | Sterling Infrastructure, Inc. Quote
Operating income more than doubled to $306.8 million, while operating margin improved 140 basis points to 19.6%. Gross margin narrowed modestly, but the stronger operating result provided a clear foundation for management to lift its full-year expectations.
Sterling's Raised Guidance Extends the Growth Story
Sterling raised 2026 revenue guidance to $4.63-$4.73 billion from $4-$4.15 billion. Adjusted earnings guidance increased to $21.70-$21.96 per share from $19.70-$20.30, while adjusted EBITDA guidance moved to $970-$981 million from $891-$916 million.
The revisions reflect stronger execution and visibility into year-end demand, particularly across E-Infrastructure. A comparable infrastructure contractor, Quanta Services, Inc. PWR, also raised its 2026 financial expectations after reporting record third-quarter backlog, reinforcing the broader strength in large-scale infrastructure spending.
STRL's Backlog Adds Multi-Year Revenue Visibility
Combined backlog reached $6.14 billion at September-end, up 78% year over year. Including about $1.7 billion of next phases in design, total scoped work approached $8 billion, up roughly 90% from a year earlier, with mission-critical projects representing about 95% of E-Infrastructure opportunities.
Management has also identified permitted and powered land at existing campuses that could provide more than five years of additional work beyond currently scoped projects. Primoris Services Corporation PRIM, another infrastructure contractor, reported record total backlog of $14.1 billion in its latest quarter, highlighting the scale of demand across utility and energy infrastructure markets.
Sterling's Execution Risks Could Limit Upside
Sterling's growth is changing its margin mix. CEC's rising contribution reduced E-Infrastructure operating margin to 22.6% from 25.6% a year earlier because electrical work carries a greater material component and structurally lower margins than site development, even as CEC's own profitability improves.
Execution demands are also increasing. Continued expansion requires sustained hiring and workforce deployment, while fourth-quarter seasonality and weather can affect project timing. Building Solutions remains pressured by housing affordability, and higher accounts receivable and working-capital requirements could keep cash conversion uneven as E-Infrastructure grows.
STRL's Ratings Support the Near-Term Setup
The raised outlook, backlog visibility and earnings momentum support a constructive near-term case, but the higher targets also make continued execution important. Margin improvement at CEC, project timing and cash conversion will help determine whether the 2026 step-up carries cleanly into the next phase of growth.
STRL currently carries a Zacks Rank #2 (Buy). Its Momentum Score of A and VGM Score of A complement the favorable short-term earnings-revision setup, while the Growth Score of B fits the company's expanding earnings profile. The Value Score of C is less decisive, keeping execution against the higher outlook central to the investment case.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Sterling Infrastructure, Inc. (STRL): Free Stock Analysis Report
Quanta Services, Inc. (PWR): Free Stock Analysis Report
Primoris Services Corporation (PRIM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).