

Edwards Lifesciences Corporation EW reported third-quarter 2026 adjusted earnings per share (EPS) of 80 cents, up 19% year over year. The metric beat the Zacks Consensus Estimate by 9.6%.
Revenues rose 10.5% year over year to $1.72 billion, increasing 11.2% at constant currency. The figure topped the consensus mark by 2.4%.
Following the announcement yesterday, EW shares jumped nearly 2.2% in after-hours trading.
EW's Segment Sales Reflect Broad-Based Growth
Transcatheter Aortic Valve Replacement (“TAVR”) sales totaled $1.24 billion, increasing 8% year over year on a reported basis and 8.8% at constant currency. Growth was similar in the United States and international markets, supported by procedural growth, clinical evidence favoring proactive treatment of severe aortic stenosis and continued adoption of the SAPIEN 3 Ultra RESILIA platform. Edwards' competitive position improved modestly year over year in the United States and Europe, while continued adoption of SAPIEN technology and new dedicated reimbursement contributed to strong performance in Japan.
Transcatheter Mitral and Tricuspid Therapies (“TMTT”) sales reached $207 million, rising 44% year over year and 45.6% at constant currency. Performance was driven by double-digit growth in mitral and tricuspid procedure volumes, increasing adoption of the PASCAL system, continued strong uptake of EVOQUE and robust demand for SAPIEN M3. Growth was strong globally, with the expanding U.S. business becoming a more significant contributor.
Edwards Lifesciences Corporation Price, Consensus and EPS Surprise
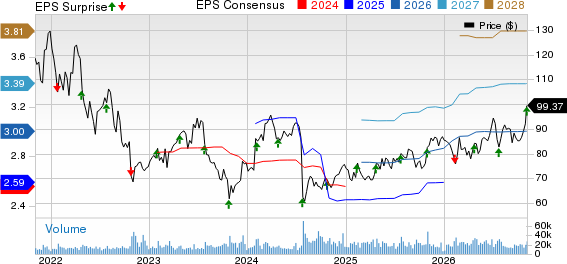
Edwards Lifesciences Corporation price-consensus-eps-surprise-chart | Edwards Lifesciences Corporation Quote
Surgical sales totaled $264 million, increasing 2.5% year over year on a reported basis and 2.8% at constant currency. Growth was driven by continued adoption of the company's RESILIA-based surgical therapies.
Edwards' Margins Reflect Operating Leverage
Adjusted gross margin expanded 80 basis points (bps) year over year to 78.7% from 77.9%. Manufacturing efficiencies and favorable foreign exchange more than offset the impact of scaling newer therapies. Currency movements provided a 50-bps benefit to gross margin.
SG&A expenses increased to $561 million from $515 million, although they declined to 32.7% of sales from 33.1%. R&D expenses remained approximately $281 million, representing 16.4% of sales compared with 18.1% a year ago.
Adjusted operating income rose 22% year over year to $520.5 million. Adjusted operating margin expanded 280 bps to 30.3%, reflecting strong revenue growth and the planned timing of investments.
Edwards Maintains Financial Flexibility
As of Sept. 30, 2026, the company had approximately $3.10 billion in cash and cash equivalents. Total debt was about $600 million, leaving Edwards with substantial liquidity to support organic investment, manufacturing expansion and external opportunities in structural heart therapies.
The company repurchased approximately $700 million worth of shares through the first nine months of 2026 and had roughly $1.30 billion remaining under its share-repurchase authorization.
Edwards Raises 2026 Sales and Earnings Outlook
Edwards increased its 2026 constant-currency sales growth guidance to approximately 11.5% from the earlier 10-11%. TAVR growth guidance was raised to 9-9.5% from 8-9%, while the TMTT sales outlook increased to $780-$790 million from $760-$780 million. Surgical sales are still expected to grow at a mid-single-digit rate. The Zacks Consensus Estimate for 2026 revenues currently stands at $6.76 billion, implying 11.4% growth over 2025.
The company raised its adjusted EPS guidance to $2.97-$3.05 from $2.95-$3.05. The Zacks Consensus Estimate for the same is pegged at $3.00.
For the fourth quarter of 2026, Edwards projects revenues of $1.67-$1.75 billion and adjusted earnings of 61-69 cents per share. The consensus mark for fourth-quarter revenues and EPS is projected at $1.70 billion and 71 cents, respectively.
Our Take
Edwards exited the third quarter of 2026 with both earnings and revenues surpassing estimates. Performance reflected broad-based strength across its structural heart portfolio, supported by healthy TAVR procedure volumes, strong adoption of mitral and tricuspid therapies and favorable contributions from international markets.
Within TAVR, Edwards' competitive position remained strong, supported by continued adoption of the SAPIEN 3 Ultra RESILIA platform. The encouraging results from the PROGRESS trial and the updated national coverage determination for TAVR represent significant developments that could support earlier intervention and broader patient access. TMTT benefited from increasing uptake of PASCAL, EVOQUE and SAPIEN M3, alongside recent U.S. approvals for PASCAL Precision in tricuspid repair and PASCAL Ace with Capture Clarity in mitral repair.
The expansion of adjusted operating margin is also encouraging. The upward revision to full-year sales and earnings guidance reflects management's confidence in the company's underlying business momentum.
EW’s Zacks Rank and Key Picks
Edwards currently carries a Zacks Rank #3 (Hold).
Some better-ranked stocks from the broader medical space are Bausch + Lomb BLCO, Medpace MEDP and Intuitive Surgical ISRG
Bausch + Lomb,sporting a Zacks Rank #1 (Strong Buy) at present, posted third-quarter 2026 adjusted EPS of 34 cents, exceeding the Zacks Consensus Estimate by 61.91%. Revenues of $1.28 billion topped the Zacks Consensus Estimate by 0.14%. You can see the complete list of today’s Zacks #1 Rank stocks here.
BLCO has an estimated long-term earnings growth rate of 40.1% compared with the industry’s 13.5% growth. The company’s earnings outpaced estimates in three of the trailing four quarters and missed on one occasion, the average surprise being 21.67%.
Medpace, carrying a Zacks Rank #2 (Buy), reported third-quarter 2026 adjusted EPS of $4.84, which surpassed the Zacks Consensus Estimate by 8.76%. Revenues of $716 million beat the Zacks Consensus Estimate by 1.02%.
MEDP has an estimated long-term earnings growth rate of 14.3% compared with the industry’s 13.2% growth. The company outperformed earnings estimates in each of the trailing four quarters, the average surprise being 9.77%.
Intuitive Surgical, carrying a Zacks Rank #2 at present, posted third-quarter 2026 adjusted EPS of $3.00, exceeding the Zacks Consensus Estimate by 14.94%. Revenues of $3.05 billion topped the Zacks Consensus Estimate by 5.84%.
ISRG has an earnings yield of 2.5% against the industry’s negative 2.1% yield. The company’s earnings outpaced estimates in each of the trailing four quarters, the average surprise being 15.12%.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Edwards Lifesciences Corporation (EW): Free Stock Analysis Report
Intuitive Surgical, Inc. (ISRG): Free Stock Analysis Report
Medpace Holdings, Inc. (MEDP): Free Stock Analysis Report
Bausch + Lomb Corporation (BLCO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).