

Mastercard Incorporated MA just delivered the kind of quarter investors usually celebrate: earnings grew faster than revenues, margins widened and its services business outpaced the payments network. Yet the real story is not simply another earnings beat. With customer incentives climbing, regulatory pressure growing and some international spending slowing, can the payments giant keep turning transaction growth into even stronger profits?
How Strong Was Mastercard's Q3 Performance?
Adjusted earnings rose 21.2% year over year to $5.31 per share, beating the Zacks Consensus Estimate of $5.14 by 3.3%. Net revenues advanced 14% to $9.81 billion, topping expectations by 1.8%. Adjusted operating income increased 15% to $5.94 billion, while adjusted operating margin expanded 70 basis points to 60.5%.
Adjusted operating expenses increased 12%, slower than revenues, showing that higher transaction activity and services sales can lift profits without a matching rise in costs. Still, the EPS growth figure needs context. Share repurchases contributed 16 cents per share, and the adjusted tax rate fell to 20.1% from 21.4%. Those tailwinds helped, although stronger operating earnings remained the main driver.
Why Is the Services Business So Important?
Value-added services and solutions generated $4.06 billion in revenues, up 19%, outpacing the payment network's 11% increase. Services supplied approximately $635 million of Mastercard's $1.21 billion year-over-year revenue increase. In other words, a business representing about 41% of total sales delivered more than half of incremental growth.
Demand came from cybersecurity, digital authentication, consumer engagement and business insights. These offerings help banks and merchants combat fraud, win customers and improve transactions. They also give Mastercard ways to earn revenue beyond processing a payment.
Management estimates that roughly 60% of services are linked to its network. That creates a reinforcing cycle: more transactions create demand for fraud protection and data tools, while better services make Mastercard's network harder for partners to replace. Continued cross-selling could support growth even when spending volumes normalize.
The Core Network Still Has Momentum
Mastercard processed 49.3 billion switched transactions, up 9%, while purchase volume also grew 9%. Domestic assessments climbed 13%, outpacing the 7% growth in gross dollar volume to roughly $3 trillion, supported by pricing and transaction mix. Similarly, cross-border assessments advanced 16% against an 11% increase in cross-border volume, benefiting from travel and online commerce. The faster growth in assessments relative to underlying volumes highlights Mastercard's ability to improve revenue generation through favorable transaction mix and pricing.
The company also had 3.8 billion Mastercard and Maestro cards issued worldwide. Contactless payments represented 81% of in-person switched purchase transactions, five percentage points higher than a year ago.
U.S. credit volume rose 10%, though debit growth was just 1% amid the Capital One migration. Outside the United States, debit volume climbed 10%, a healthier signal of payment adoption beyond the domestic market.
Can AI and Stablecoins Add Another Growth Layer?
Mastercard is pushing beyond traditional card transactions through agentic commerce and digital assets. Its Global Money Platform, introduced following the BVNK acquisition, combines conventional currencies and stablecoins, connecting with Mastercard Move's 17 billion endpoints. The aim is to help financial institutions handle different forms of money without building separate systems.
Meanwhile, Mastercard is developing capabilities for transactions initiated by AI agents, with authentication and security playing central roles. Such innovations could position the company to capture emerging payment flows as digital commerce evolves. However, adoption remains at an early stage, and evolving regulations, implementation costs and uncertain monetization timelines could delay meaningful financial contributions. For now, these initiatives offer longer-term optionality rather than an immediate earnings catalyst.
Risks Investors Should Not Ignore
Winning business is getting expensive. Payment-network rebates and incentives jumped 18% to $6.37 billion, reflecting the costs of securing and retaining issuer relationships. Management expects incentives as a share of gross assessments to rise again in the fourth quarter. While these arrangements help Mastercard defend its competitive position and transaction volumes, sustained increases could dilute the revenue benefits of network expansion.
Cross-border spending is becoming less even. Growth in cross-border card-not-present transactions excluding travel slowed to 15% from 20% in the second quarter. Lower-yielding spending within Europe faced pressure from customs fees, retail promotion timing and tougher comparisons for cryptocurrency purchases. Middle East tensions have also affected travel. Nevertheless, higher-yielding cross-border activity remains resilient.
Regulatory developments add another layer of uncertainty to Mastercard's pricing flexibility. Scrutiny of interchange fees, merchant acceptance practices and competition in the United States and Europe could result in stricter operating requirements or unfavorable legal outcomes.
Estimates Remain Firm for MA
The Zacks Consensus Estimate for Mastercard’s 2026 EPS is pegged at $19.99, indicating 17.5% year-over-year growth. The estimate for 2027 stands at $23.08, suggesting a further 15.5% increase. Similarly, the consensus estimates for 2026 and 2027 revenues are pegged at $37.34 billion and $41.96 billion, implying year-over-year growth of 13.9% and 12.4%, respectively.
The company beat earnings estimates in each of the past four quarters, with an average surprise of 3.3%.
Mastercard Incorporated Price, Consensus and EPS Surprise
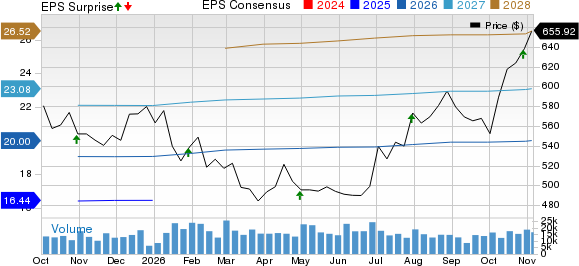
Mastercard Incorporated price-consensus-eps-surprise-chart | Mastercard Incorporated Quote
Mastercard’s Price Performance & Valuation
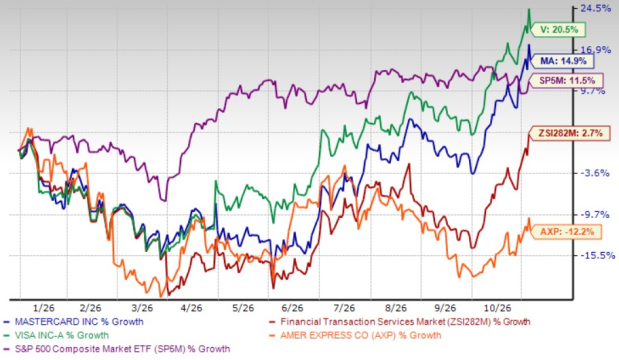
MA shares have gained 14.9% year to date, including a 7.5% advance since the company reported third-quarter results, outperforming the industry’s 2.7% rise and the S&P 500’s 11.5% increase. In comparison, Visa Inc. V has jumped 20.5%, while American Express Company AXP has declined 12.2%.
YTD Price Performance – MA, V, AXP, Industry & S&P 500
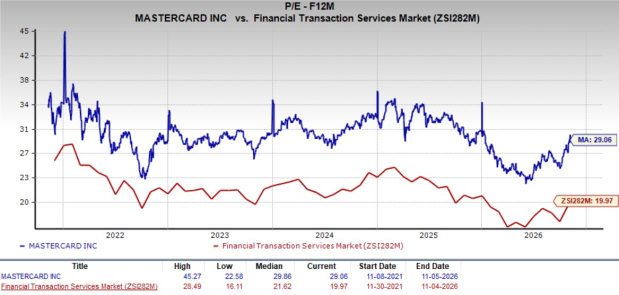
From a valuation standpoint, Mastercard trades at a forward P/E ratio of 29.06X, close to its five-year median of 29.86X but considerably above the industry average of 19.97X. Visa and American Express trade at 27.75X and 16.38X, respectively. Mastercard's premium reflects its strong profitability, scalable network and expanding services portfolio. However, with rising incentives and uneven cross-border spending trends, the valuation appears to factor in continued robust execution, leaving limited scope for earnings disappointments or a moderation in growth.
Conclusion
Mastercard's third-quarter performance reinforces its ability to capitalize on growing digital payment adoption while expanding its higher-growth services business. Its strong earnings trajectory and improving operating efficiency support a favorable long-term outlook. However, escalating customer incentives, regulatory uncertainties and uneven cross-border trends could constrain upside potential.
Moreover, the stock's premium valuation already reflects considerable optimism about future growth, making its risk-reward profile less compelling for fresh investments. Sustained earnings momentum supports holding existing positions. Mastercard currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Mastercard Incorporated (MA): Free Stock Analysis Report
Visa Inc. (V): Free Stock Analysis Report
American Express Company (AXP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).