

PPL Corporation’s PPL shares are currently trading at a premium to the Zacks Utility - Electric Power industry. The company's 12-month forward price-to-earnings ratio of 16.83X exceeds the industry average of 16.43X and the broader Zacks Utility sector's 16.36X.
PPL Corporation is poised to benefit from rising electricity demand, particularly from the rapid expansion of data centers in Pennsylvania and Kentucky. Increasing power requirements from these energy-intensive facilities are expected to drive long-term load growth and create additional investment opportunities.
However, intensifying competition in the transmission business could weigh on the company's growth prospects. Additionally, unexpected operational disruptions may adversely affect its financial performance and profitability.
Image Source: Zacks Investment Research
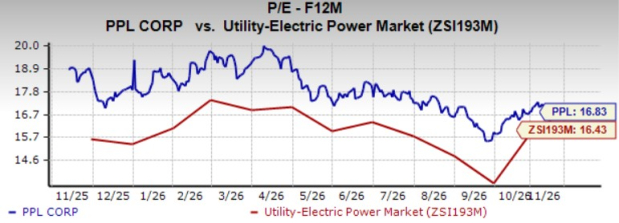
Other operators in this space, Exelon Corporation EXC and FirstEnergy Corporation FE, are trading at P/EF12M of 15.07X and 15.94X, respectively, a discount to the industry. Both these utilities are investing substantially to strengthen their infrastructure.
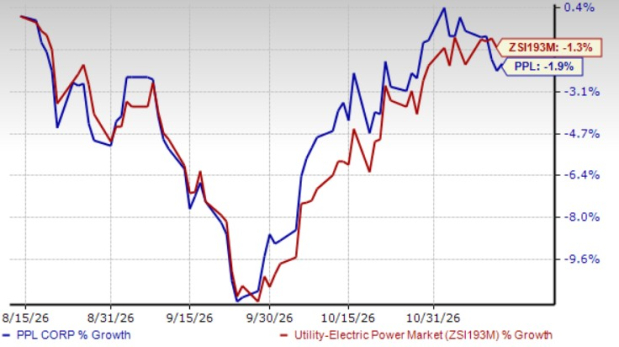
PPL’s shares have lost 1.9% in the past three months, wider than the Zacks Utility-Electric Power industry’s decrease of 1.3%.
Price Performance (Three Months)
Image Source: Zacks Investment Research
With PPL Corporation's share price experiencing recent weakness, investors may be wondering whether this presents an attractive buying opportunity. Let’s examine the key factors that could help determine if the stock deserves a place in investors’ portfolios at current levels.
Factors Driving PPL Corporation’s Long-Term Growth Potential
PPL continues to benefit from economic expansion and increasing data center demand across its service territories. In Pennsylvania, advanced-stage data center demand has risen to nearly 35.3 GW from 31.8 GW in the second quarter, while Kentucky’s economic development pipeline now points to potential load growth of 14.7 GW, including 12.8 GW from data centers.
To capitalize on these growth opportunities, PPL plans to invest nearly $25 billion between 2027 and 2030, supporting an average annual rate base growth of approximately 10% through 2030. Investments target transmission, distribution, reliability and generation capacity required by new demand.
More than 60% of PPL Corporation’s capital investment program is eligible for contemporaneous recovery, helping minimize regulatory lag and support timely cost recovery. This mechanism strengthens earnings visibility and financial flexibility, enabling the company to efficiently execute its long-term capital investment and growth plans.
PPL Corporation’s competitive service rates, which remain lower than those in comparable states, support customer retention and attract new customers, providing a stable foundation for sustained growth. Backed by these advantages, the company expects to achieve annual earnings growth of 7-9%.
Headwinds for PPL Stock
PPL Corporation faces challenges from substantial capital requirements, project execution risks and potential delays in regulatory cost recovery. Rising competition in Pennsylvania’s transmission market, weather-related demand fluctuations, cybersecurity threats, equipment failures and fuel supply disruptions could further pressure earnings and profitability.
PPL’s Earnings Estimate
The Zacks Consensus Estimate for PPL’s 2026 earnings per share remained the same over the past 60 days, while the same for 2027 indicates an increase of 0.47%.
Image Source: Zacks Investment Research
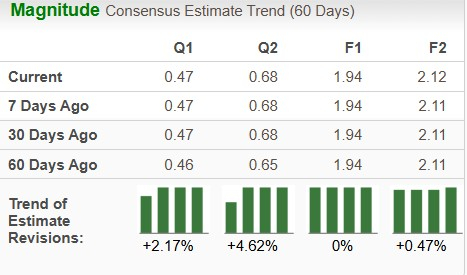
FirstEnergy is making a substantial investment to strengthen its infrastructure to provide reliable services to customers. The Zacks Consensus Estimate for FE’s 2026 earnings per share remained unchanged, but the same for 2027 declined 0.34% in the past 60 days.
PPL’s Long-Term Debt to Capital
Utility operations are capital-intensive and companies in this sector often need to borrow to fund long-term projects when internal resources are insufficient. The company is also borrowing funds to meet its capital requirements. The rising interest rates will increase the financing cost of the utilities, which have large-scale capital expenditure and a substantial amount is funded by borrowings.
PPL’s current debt to capital is 57.46% compared with its industry average of 62.13%. This shows the company is utilizing less debt than peers to run its operations.
Image Source: Zacks Investment Research
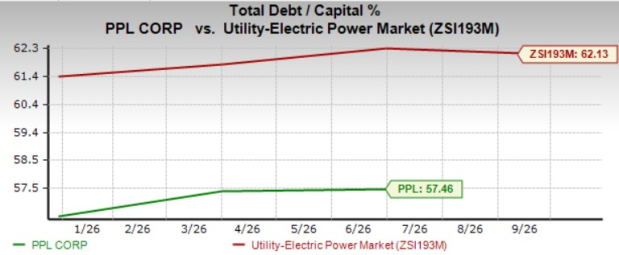
Like PPL, Exelon’s long-term debt on its balance sheet is more than the peers in the industry. EXC’s debt to capital is 63.84% compared with its industry average of 62.13%.
PPL’s Return Is Lower Than the Industry
Return on equity (“ROE”) is a financial ratio that measures how well a company uses its shareholders’ equity to generate profits. The current ROE of the company indicates that it is using shareholders’ funds more efficiently than peers.
PPL’s trailing 12-month ROE is 9.58%, lower than the industry average of 11.1%.
Image Source: Zacks Investment Research
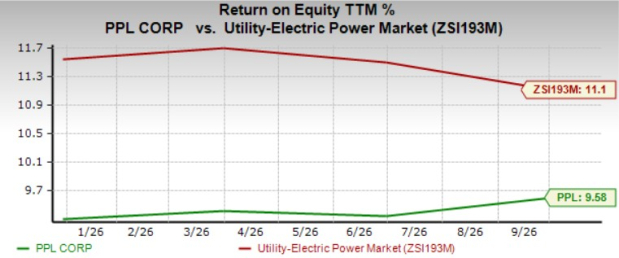
Like PPL, Exelon’s ROE of 9.75% and FE’s 11.07% are also lower than the industry they belong to.
Wrapping Up
PPL Corporation is benefiting from rising electricity demand from data centers and favorable regulatory recovery mechanisms that support its long-term growth plans. The company’s expanded $25 billion capital investment program, focused on infrastructure upgrades, grid reliability and IT modernization, is expected to strengthen operations and meet growing electricity demand across its service territories.
Despite trading at a premium valuation, PPL Corporation remains an attractive investment, supported by upward earnings estimate revisions, relatively low debt levels and consistent shareholder returns. The recent weakness in its share price could provide investors with an opportunity to add this Zacks Rank #2 (Buy) stock to their portfolios.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
PPL Corporation (PPL): Free Stock Analysis Report
Exelon Corporation (EXC): Free Stock Analysis Report
FirstEnergy Corporation (FE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).