

Leading memory chipmaker Micron Technology (MU) is all set to report its fiscal fourth-quarter earnings on Sept. 30, after the market closes. Wall Street is expecting another blockbuster quarterly showing from the Boise, ID-based company, with Citi analyst Atif Malik being particularly gung-ho.
Raising his price target to $1,300 from $1,150, and reiterating its “Buy” rating on the stock, Malik said in a note to clients, "We model F4Q26 sales/EPS of $51B/$31.45, above consensus of $50.8B/$31.43 and F1Q27 sales/EPS of $57B/$35.25, above consensus of $56.7B/$35.15. We raise near-term NAND/DRAM pricing assumptions on non-SCA contracted bits. We assume blended DRAM ASPs +20%/+13% Q/Q and blended NAND ASPs +34%/+15% in F4Q/F1QE, respectively. We expect Micron volume/bits to grow roughly in line with the industry in 2026. We model FY27 capex of $50B with shell spend in low $20s and remaining equipment."
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About Micron Technology
Founded in 1978 by raising funds from the local Idaho business community, Micron is a semiconductor company that designs and manufactures memory and storage solutions used across data centers, AI systems, PCs, smartphones, automobiles, and other electronics. Its key products include DRAM, NAND, and NOR memory, with its high-bandwidth memory (HBM) becoming increasingly important for AI accelerators such as Nvidia’s GPUs. Micron also produces SSDs and advanced memory modules for servers.
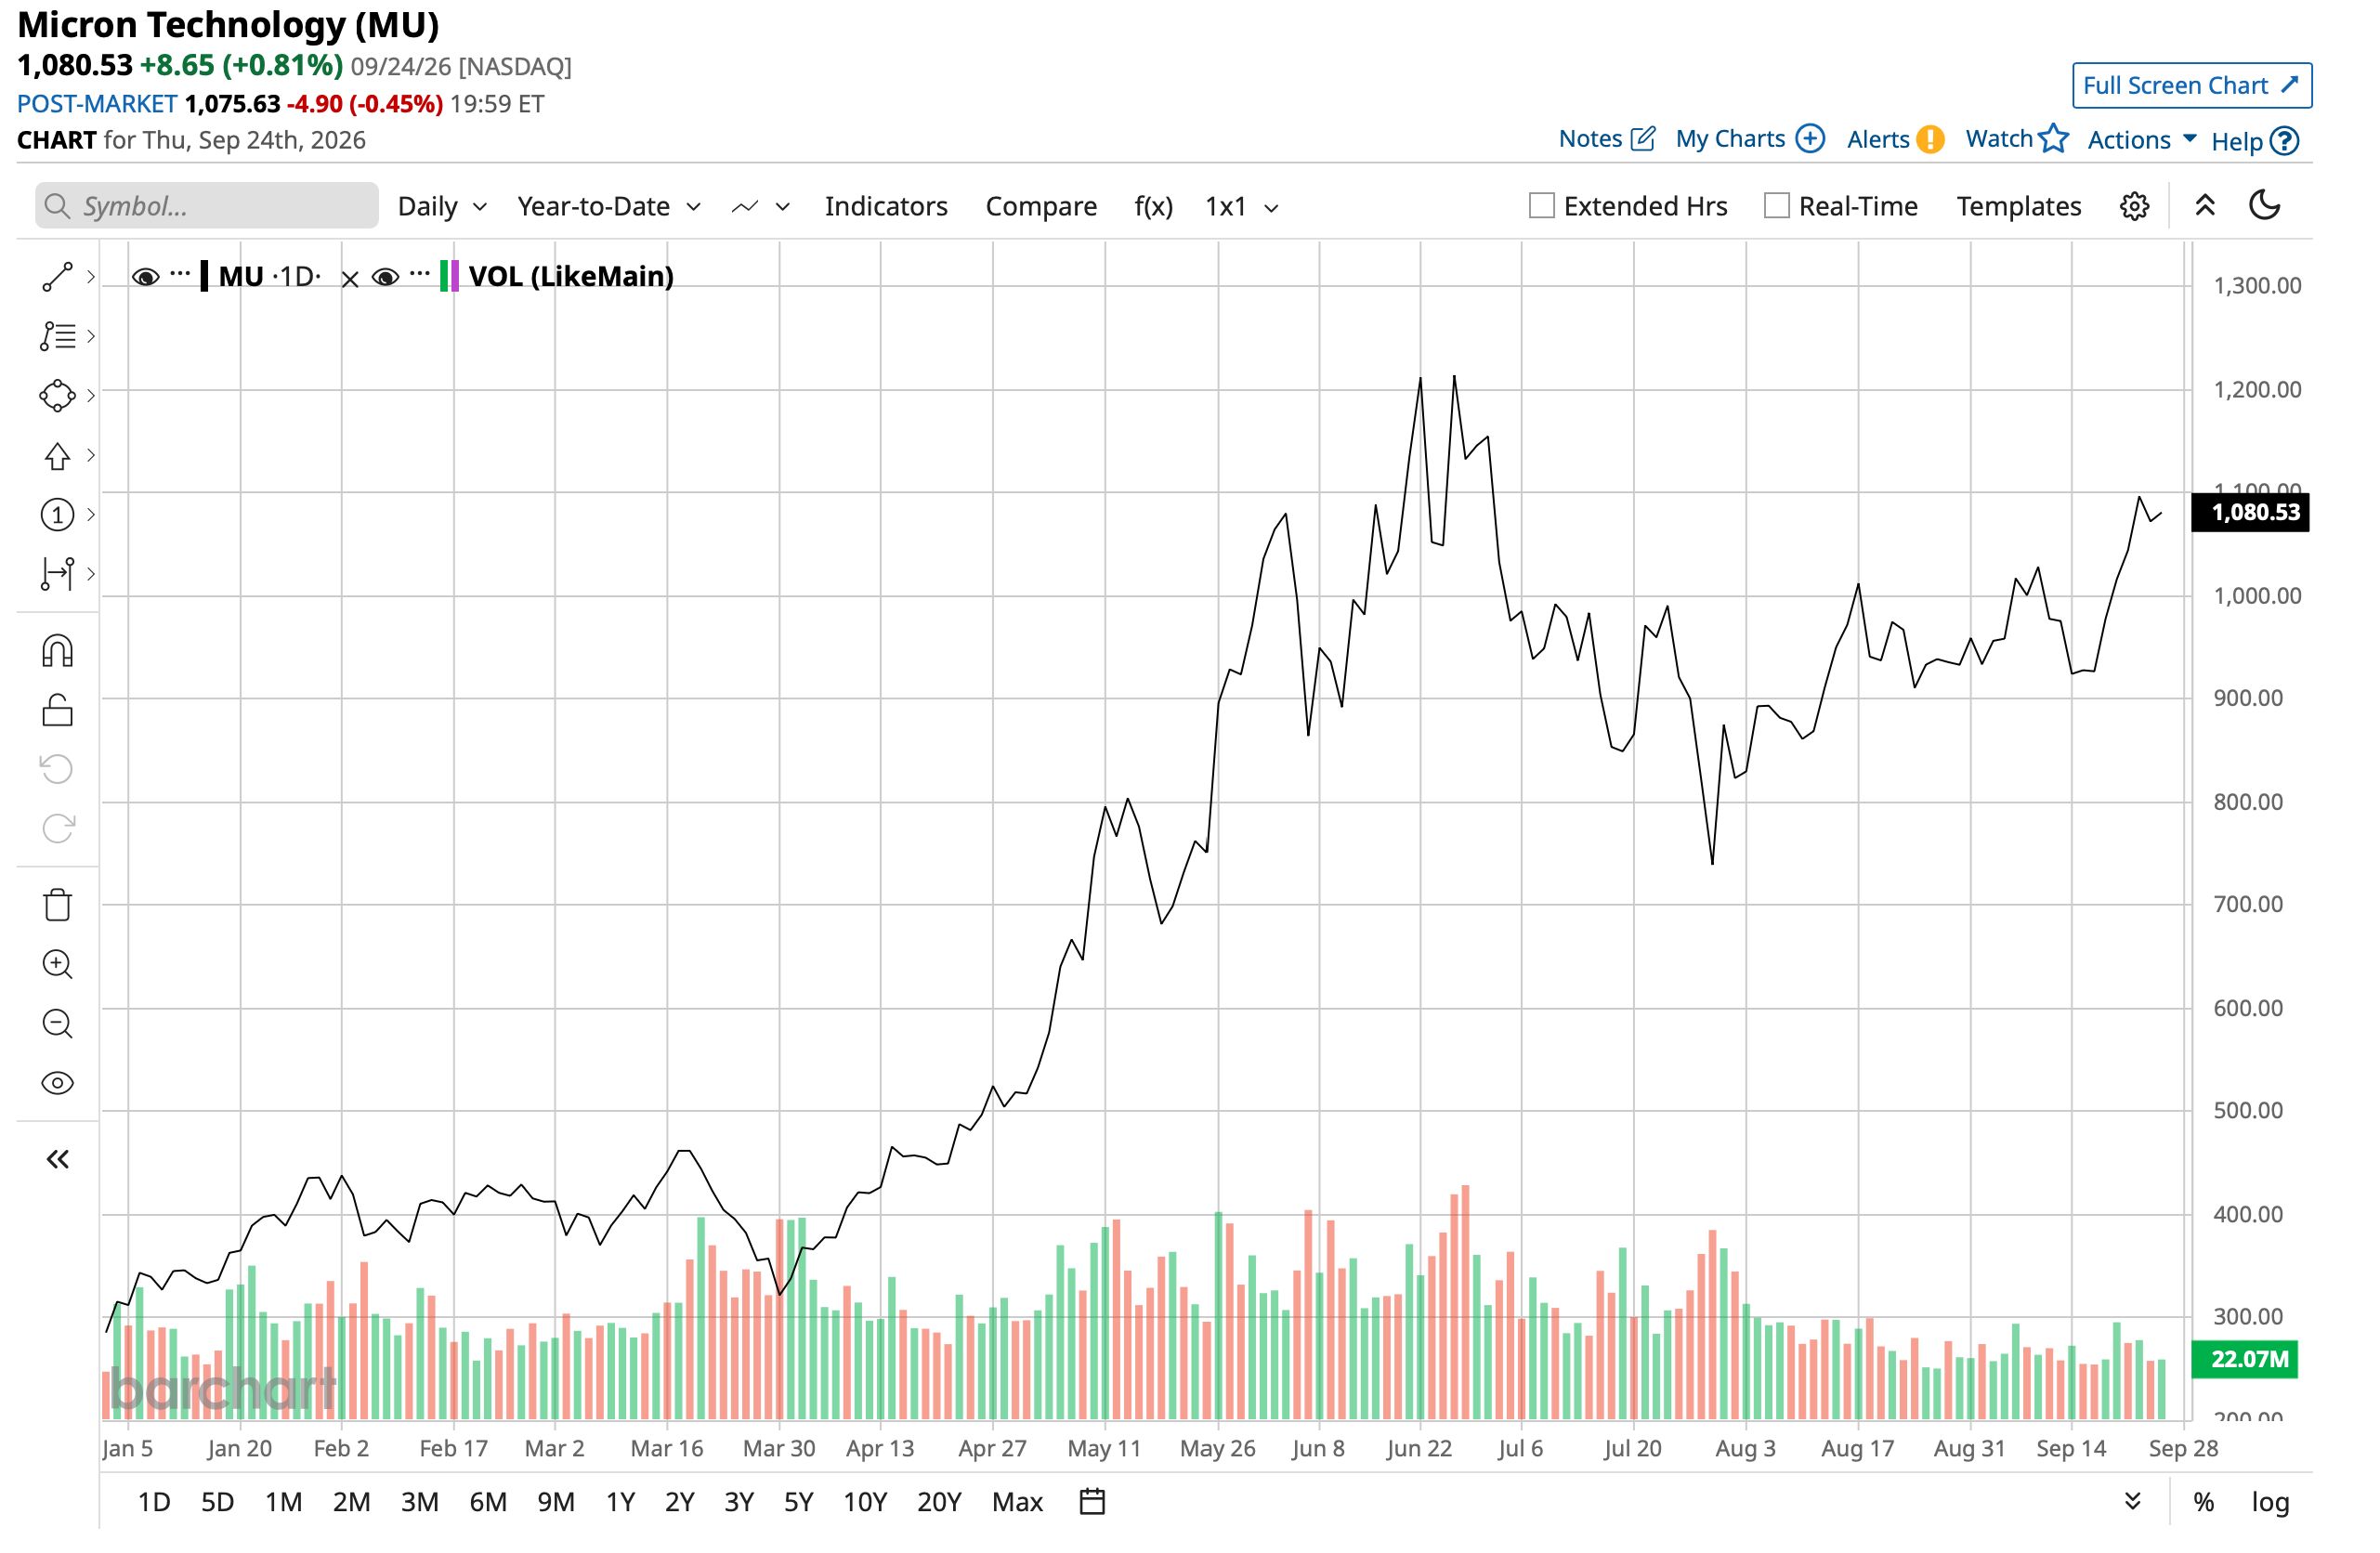
Valued at a market cap of $1.2 trillion, MU stock has flown off the charts this year by rallying 278.6% on a year-to-date (YTD) basis.
 www.barchart.com
So, can Micron continue to outperform? It seems so, and here's why.
Micron Is Going Places
As AI demand shows no signs of abating, demand for Micron's memory chips should not as well. This is because access to high-speed memory is critical for the AI chips to function with minimum latency and maximum efficiency. Moreover, while DRAM, and more specifically, high-bandwidth memory (HBM), hogs most of the limelight, NAND's place in the memory hierarchy is gaining prominence as agentic AI and inference increasingly gain pace.
Notably, Micron is not sitting on its laurels, as seen from its market share gains in the last quarter, mostly at the expense of SK Hynix (SKHY). As of Q2 2026, Micron now has a 24% market share in the DRAM market, up from 22% in Q1 2026 and Q2 2025. Moreover, the company is adding capacity to grow its share further and compete effectively with the likes of SK Hynix and the market leader, Samsung.
Micron’s Idaho fabrication facility is projected to begin initial DRAM production around the middle of 2027. By the middle of the year, the Tongluo plant in Taiwan and the HBM facility in Singapore are scheduled to start contributing output. The Singapore NAND plant is expected to enter production during the second half of 2028. Additional capacity is planned beyond these projects, including a second Idaho fabrication site targeted for late 2028, and Micron's up-to-$100 billion New York megafab project, which began construction in 2026 and is expected to provide supply from 2030 onward. The broader four-fab New York campus is planned to be built out over more than two decades, with the final fab's construction extending into 2041.
Thus, Q4 will not be all about the numbers, as more color on products and capacity expansion will be expected. As for the numbers, analysts are expecting the company to report revenue and earnings of $51.3 billion and $31.60 per share, respectively.
Strong Momentum Reflected In Q3 Numbers
Micron delivered exceptional results in the third quarter of fiscal 2026, with revenue rising to $41.46 billion. This represented a 346% increase from the year-earlier period. Gross margins expanded significantly to 84.9% from 39% in the prior-year quarter.
Strength was evident across every major segment. The cloud business generated $13.8 billion in revenue, up 306% year over year, with gross margins of 83%. The data center segment contributed $11.5 billion, advancing more than 650% with 87% margins. Mobile revenue also reached $11.5 billion, growing 254% with 87% margins, while the automotive segment produced $4.6 billion, rising 313% with 79% margins. Micron continues to demonstrate diversified momentum and is not overly reliant on any single area, even after implementing notable sequential price increases for DRAM and NAND products.
Non-GAAP earnings per share surged to $25.11 from $1.91 in the year-ago quarter, substantially exceeding the consensus estimate of $20.86 and marking the ninth consecutive quarter of beating profit forecasts.
For the fourth quarter, Micron projected revenue between $49 billion and $51 billion along with earnings per share in the range of $30 to $32.
A standout development in the third quarter was the execution of 16 strategic customer agreements across data center, consumer, and automotive markets. These deals include $22 billion in total commitments, backed by $18 billion in cash deposits. This provides coverage for more than 80% of the $27 billion in capital expenditures planned for fiscal 2026.
The company also highlighted progress on its HBM4E memory architecture built on the advanced 1 gamma process node, with volume production targeted for 2027. This platform is designed to deliver meaningful improvements in power efficiency and bandwidth, reinforcing Micron’s position as a key supplier to major hyperscale operators and artificial intelligence chip developers.
For the nine months ended May 28, 2026, net cash from operating activities increased sharply to $45.7 billion from $11.8 billion in the comparable prior-year period. Micron closed the third quarter with $25 billion in cash and minimal short-term debt of $582 million.
Despite a significant rally in the share price, MU stock continues to appear attractively valued. The forward P/E of 14.57 is below the sector median of 23.25. Meanwhile, the forward P/S and P/CF of 9.31 and 14.42 are not significantly higher than the sector medians of 3.47 and 19.81, respectively.
Analyst Opinion On MU Stock
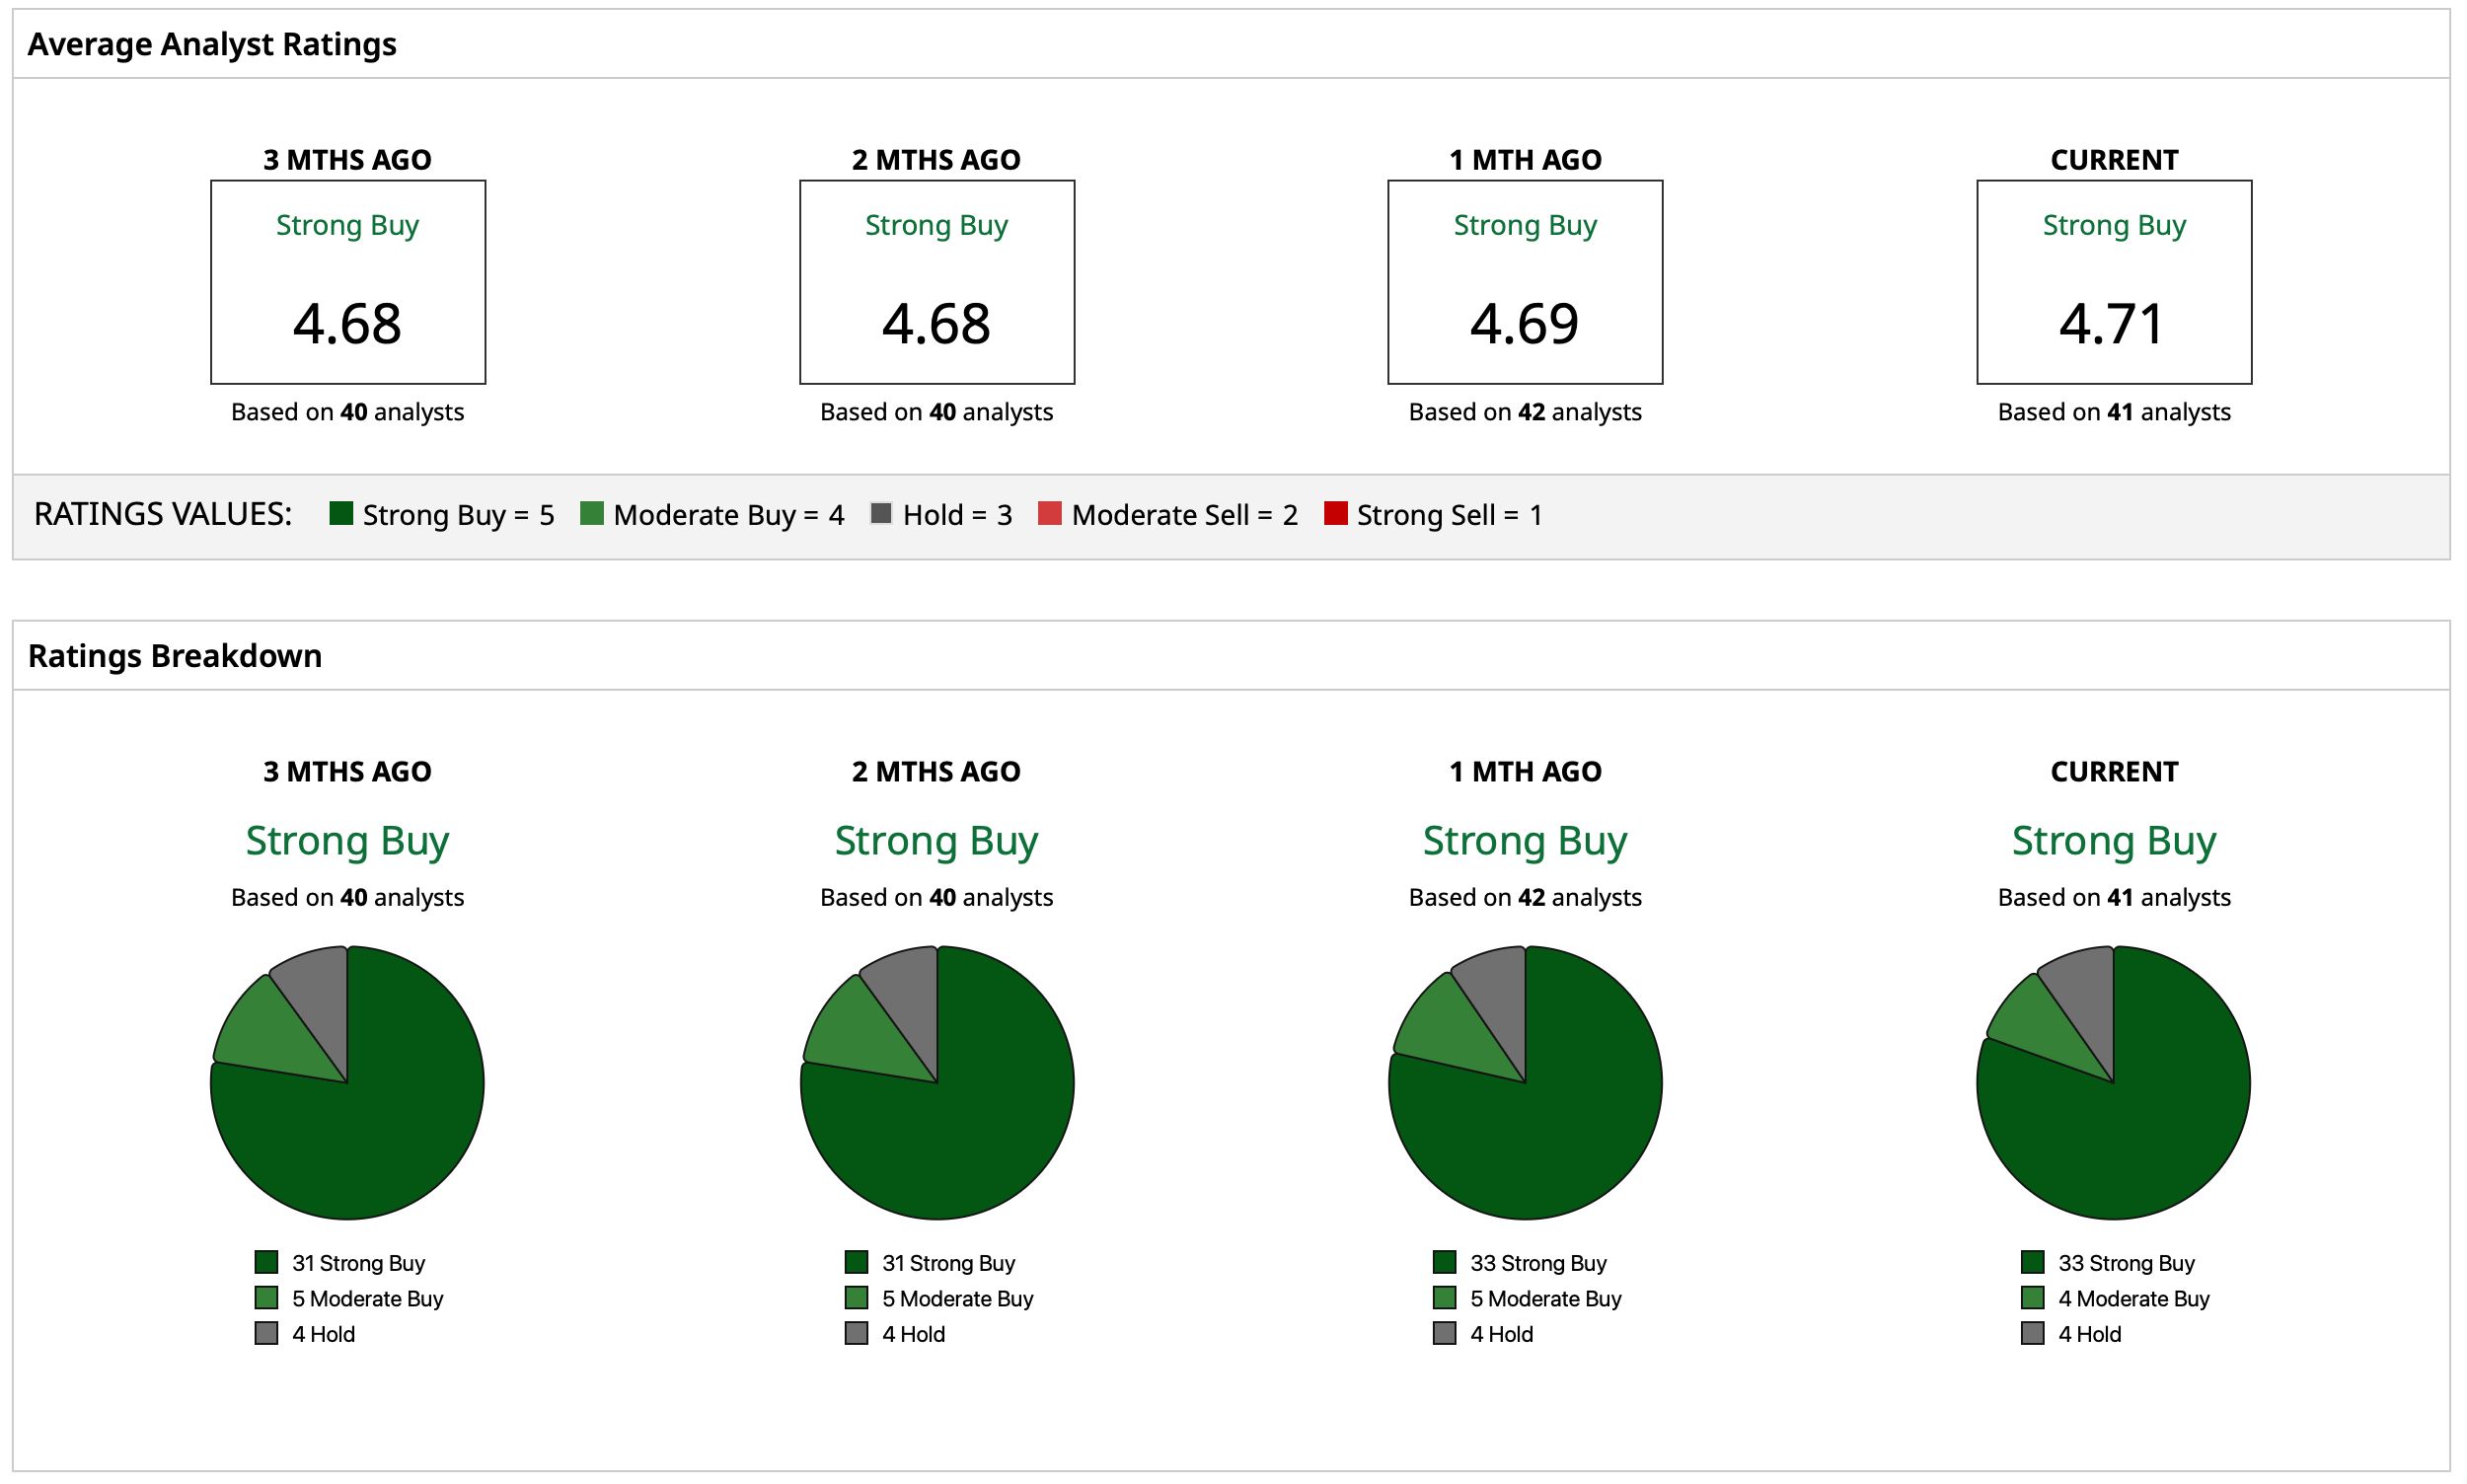
Taking all of this into account, analysts have assigned a “Strong Buy" rating for MU stock. The mean target price of $1,476.64 indicates potential upside potential of 36.7% from current levels. Out of the 41 analysts covering MU stock, 33 have a “Strong Buy” rating, four have a “Moderate Buy” rating, and four have a “Hold” rating.
 www.barchart.com
On the date of publication, Pathikrit Bose did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
As Cadence Strengthens Its Partnership With TSMC, Here's What It Could Mean for AI Stocks Citi Raises Estimates for Micron Ahead of Earnings. How to Play MU Stock Now. Options Action: Naked Put Trade Ideas for this Week UBS Started Coverage of CoreWeave With a ‘Buy’ Rating. What This Means for CRWV Stock.