

Chinese EV maker XPeng (XPEV) wants to sell its technology to other carmakers. According to Reuters, it plans to offer its systems, software, EV platform, and electric architecture to partners beyond Volkswagen. Volkswagen (VWAGY) already paid around $700 million for a 5% stake to gain access to that tech.
Now XPeng is opening the door to software developers, suppliers, and other automakers. The move is meant to fund XPeng’s bigger ambitions in robotaxis, humanoid robots, and AI. Those are expensive bets, and licensing its car technology brings in cash to chase them. On paper, it looks like a company expanding from a position of strength. But look closer, and the picture is more complicated.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The Numbers Behind the Move
XPeng’s car business is stalling. Vehicle sales grew just 1% last quarter, and vehicle margins slipped from 14.3% a year ago to 12.1%. Fierce price competition in China is pressuring every automaker, and that includes XPeng. The numbers behind the tech deals have looked quite different. Services revenue, driven mostly by the Volkswagen partnership, jumped 94% last quarter. That segment earns a margin above 75%, well above what selling cars brings in. So more than building cars, the company’s most profitable bet right now is the technology inside them.
And the vision goes even further. XPeng is also focused on robots. CEO He Xiaopeng says each IRON humanoid robot could eventually earn more over its lifetime than a car does. XPeng just raised over $900 million for its robotics arm to chase that goal. Nonetheless, its net loss widened last quarter, which shows that these bets still cost more than the core business brings in.
About XPeng Stock
XPeng Inc. is a Chinese technology company that develops artificial intelligence and uses it across a range of products. It designs its own AI chips, software, and AI models that power its technologies. The technology company is best known for its smart electric vehicles. It is also developing self-driving robotaxis and humanoid robots as the competition intensifies. Founded in 2015, the company is headquartered in Guangzhou, China.
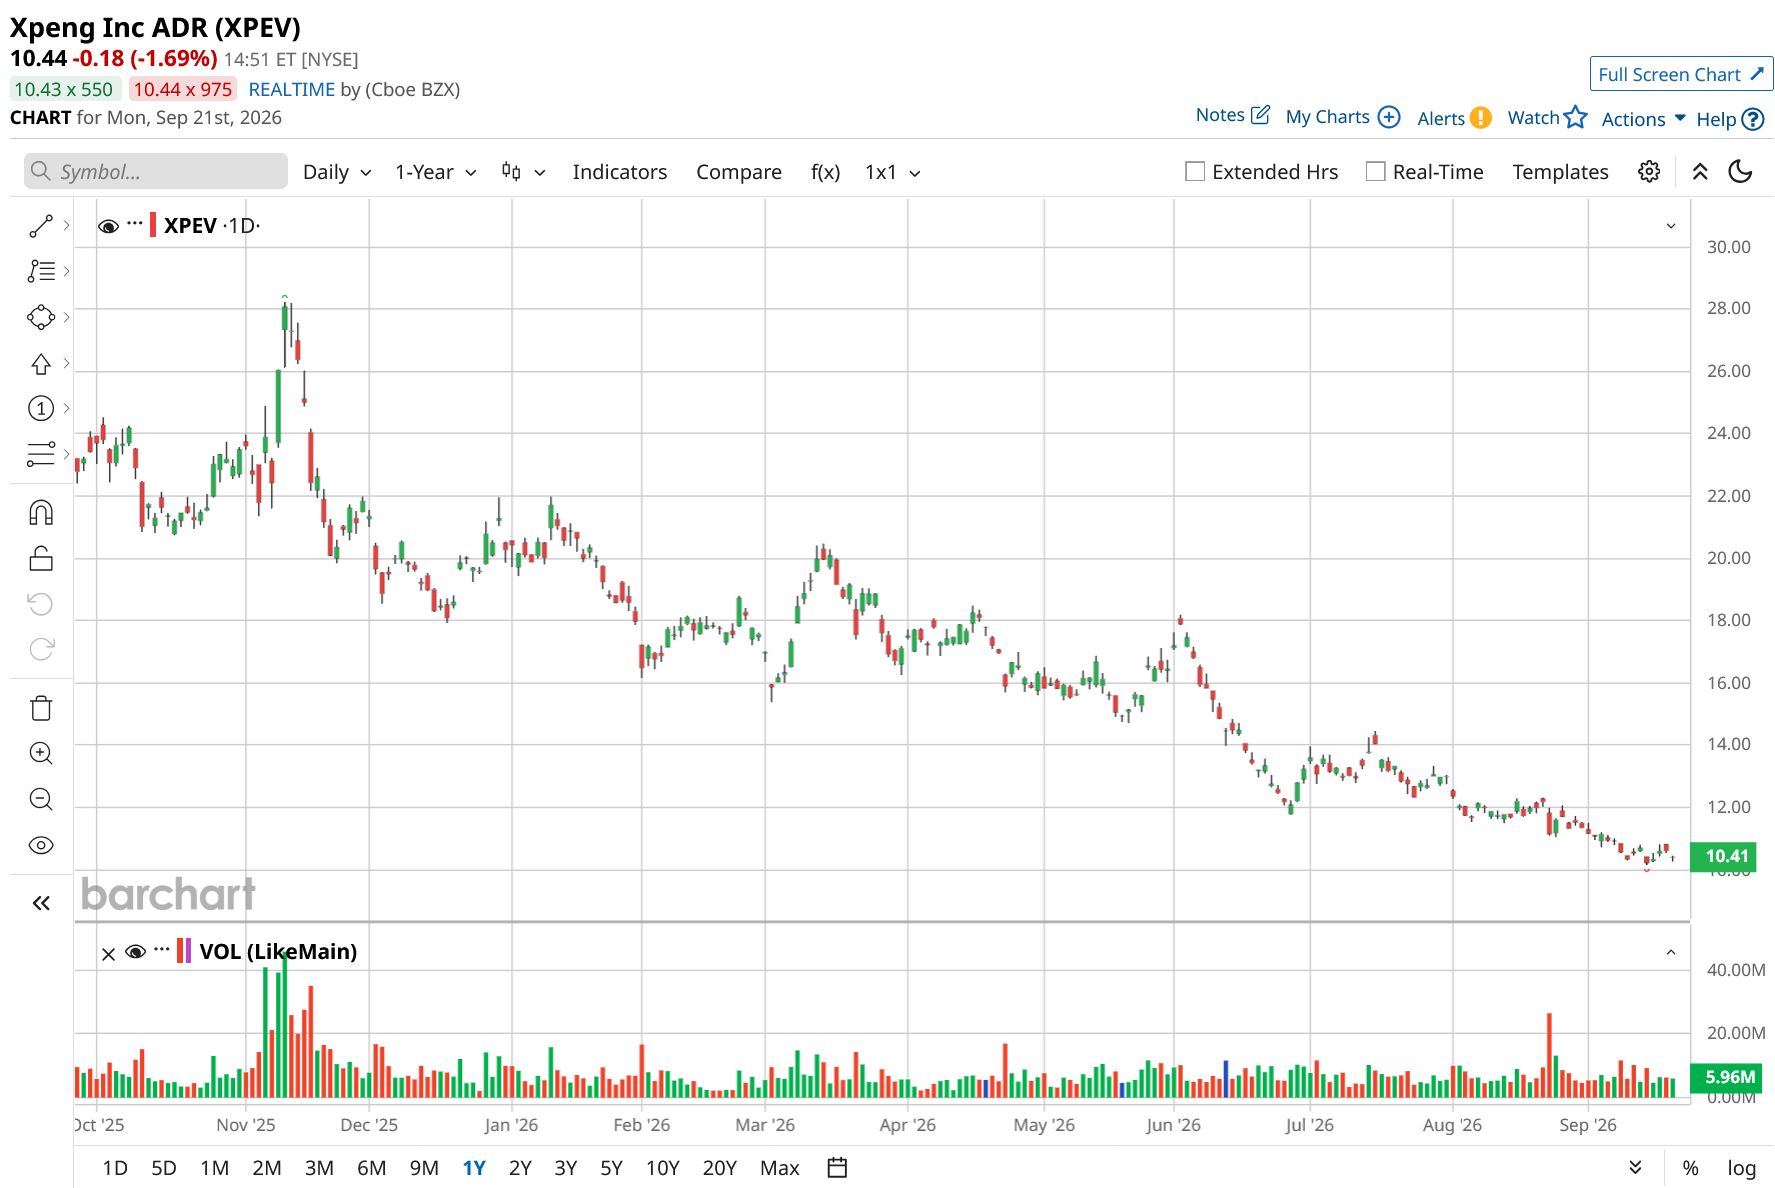
If we look at XPEV stock's performance, it isn’t that appealing. The shares have declined 52% over the past year, underperforming the KraneShares Electric Vehicles and Future Mobility ETF’s (KARS) modest gain of 0.56% during the same period. Since November 2025, the stock has been in a downtrend and has further declined from June 17, when it was trading at $17. It is now currently trading at $10. The decline appears to reflect a combination of weaker deliveries, ongoing losses, and concerns about slowing growth in China’s highly competitive EV market.
 www.barchart.com
XPeng isn’t profitable yet, so there’s no price-to-earnings (P/E) to work with. In terms of the price-to-sales (P/S) ratio, it looks fairly inexpensive. At 0.76x, it sits 75% below its 5-year average of 2.99x. That matches its current struggles. Investors are pricing it as a Chinese carmaker stuck in a brutal price war. The high-margin tech and robotics company it wants to become isn’t reflected in the price yet. The balance sheet gives it the funding to keep pursuing that shift, with $4.13 billion in cash against $3.96 billion in debt. If the licensing and robotics bets pay off, the stock looks cheap at these levels.
Can XPeng's Robotics Push Become Its Next Growth Driver? Q3 Outlook Suggests Confidence.
XPeng Inc. reported its second-quarter fiscal 2026 earnings on Aug. 24. It reported revenue of $2.91 billion, up 8% year-over-year (YoY). Vehicle sales revenue ended up at $2.51 billion, up 1% YoY. Gross margin for the quarter was 20.7%, while vehicle margin was 12.1%. The company saw higher operating costs in the second quarter. R&D expenses were approximately $429 million, and SG&A expenses were around $369 million. The operating loss was approximately $168 million, and the net loss was $200 million, wider than the year-earlier loss but better than the first quarter’s. The results suggest XPeng is growing fast, but it is still working to turn that growth into consistent profit. That tension remains central to the stock’s valuation.
Looking forward to the third quarter, XPeng guided for vehicle deliveries of 115,000 to 121,000 units and revenue of $3.20 billion to $3.45 billion. It doesn’t end here. Management ambition expands beyond Q3, as it believes XPeng’s deliveries will increase significantly in the fourth quarter, with monthly deliveries targeting more than 60,000 units. Moreover, the company is planning to further expand its footprint in robotics. The humanoid IRON robot is expected to enter scaled mass production by year-end 2026, with initial deployments in XPeng stores and campuses. Notably, the first IRON robot walked off the production line two weeks ago. XPeng is hopeful of getting European regulatory approval for its VLA 2.0 in the first half of 2027.
What Do Analysts Expect for XPEV Stock?
XPEV stock received a lot of coverage following its second-quarter earnings. Analysts updated their financial models and came up with new price targets for XPEV. DBS reiterated a “Buy” rating with a price target of $28. In addition to DBS, Bank of America Securities also maintained a “Buy” rating. JPMorgan lowered the firm’s price target from $27 to $24 and kept an “Overweight” rating on the shares. In contrast, Barclays analyst Jiong Shao reaffirmed a “Sell” rating and set a price target of $14. Despite the sell rating, the analyst’s price target is still higher than the current share price.
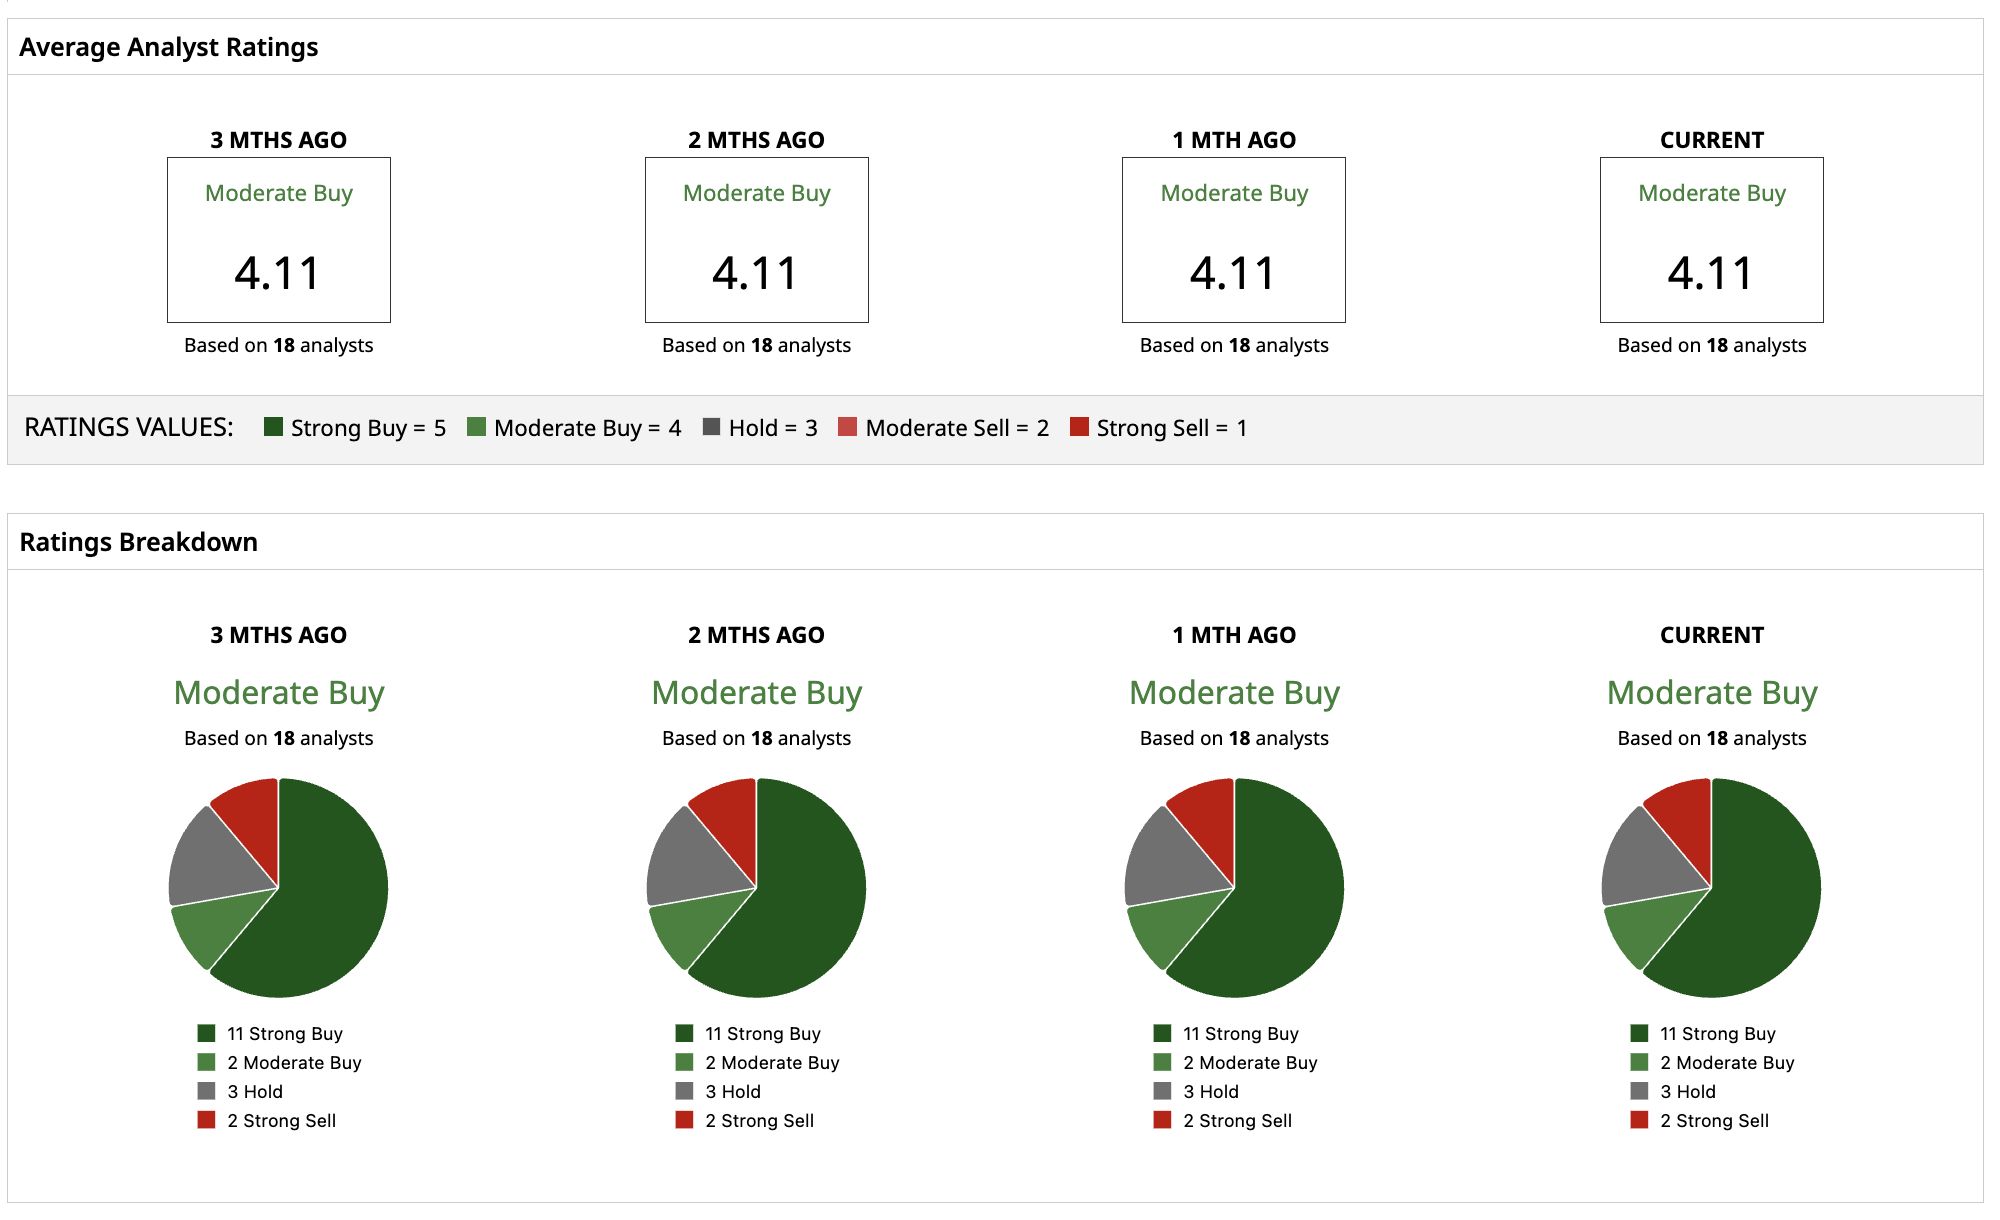
Based on 18 Wall Street analysts covering the stock, XPEV stock holds a consensus “Moderate Buy” rating. It has a median price target of $18, which reflects 80% upside from current levels. The high price target of $24 implies a further 140% from the current share price.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘Substantially Higher Than a Car’: XPeng’s CEO on What Each Robot Could Earn. First It Has to Survive a Brutal Price War. Needham Just Upped Its Price Target on OKTA Stock. Here's Why. Why It’s Time to Load Up on Meta Stock As Snap Partners With Nvidia on Its Specs, Here’s How You Should Play SNAP Stock