

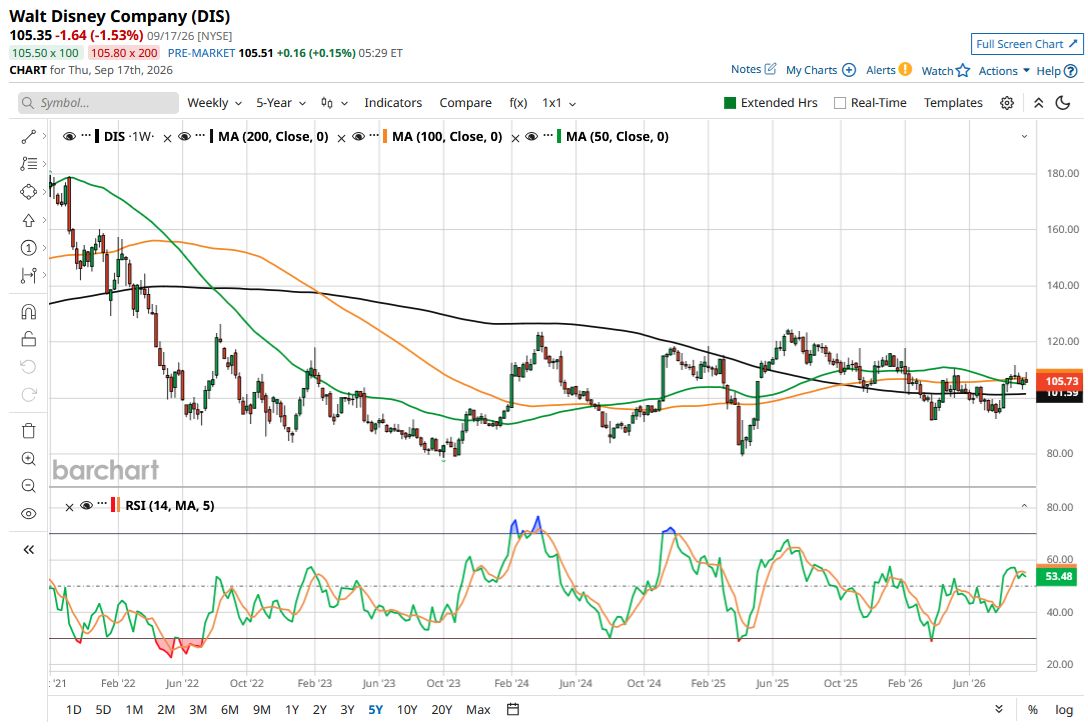
Things haven’t been great for Disney (DIS) investors for the last few years. It is down over 7% for the year and is underperforming the S&P 500 Index ($SPX) by a fairly wide margin. It saw low single-digit gains last year as well, with the returns trailing the broader markets. While the stock eked out a 23% gain in 2024, which was in line with the S&P 500 Index ($SPX), it underperformed the broader market in the previous three years.
 www.barchart.com
Disney has lost nearly 40% over the last five years and is up barely 15% over the last 10 years. Thanks to this perennial underperformance, Disney’s valuations have taken a beating. The stock, which not long ago used to trade at a premium to its average S&P 500 Index peer, now trades at a forward price-to-earnings (P/E) multiple of 15.4x. For context, the S&P 500 Index’s forward P/E is around 19x.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
In its fiscal Q3 shareholder letter last month, Disney said that it finds its shares “undervalued,” an assertion I agreed with. DIS stock is currently trading slightly higher than those levels, and unless something changes over the course of the year, it seems headed for another year of underperformance.
Why Has Disney's Stock Been Falling?
A lot has been weighing on Disney's stock, actually. Its linear TV business continues to be in a structural decline, and while the streaming business has been growing, subscriber growth has slowed from the bump we saw during the Covid-19 pandemic.
There are also lingering concerns over the Parks segment, which accounts for the bulk of Disney’s profitability. While attendance at Disney’s parks has held relatively well and the company has dismissed fears of the macro environment having a noticeable impact on its customers, markets haven’t bought that argument. Furthermore, Disney is currently amidst a massive capex cycle wherein it plans to spend $60 billion over 10 years to revamp its parks. While these investments would help improve Disney’s value proposition and make the parks even more attractive, they are also draining its otherwise healthy free cash flows.
Disney’s box office performance hasn’t been up to the mark, and some titles like The Mandalorian and Grogu and Moana underperformed. Box office success tends to have a multiplier effect for Disney. It leads to better visibility for Disney, which in turn leads to higher attendance at the company's theme parks and more merchandise sales.
Then there is concern over competition from short-form videos and the fallout from artificial intelligence (AI). While companies like Disney and Netflix (NFLX) are leveraging AI to make their offerings even more appealing, the technology also threatens their exclusive intellectual property (IP), which is their moat.
Disney is also going through a leadership transition after Bob Iger stepped down as CEO earlier this year. He handed over the baton to Josh D’Amaro, who has since made several organizational changes. In March, Disney announced a new executive team and created a new post for president and chief creative officer. Now, it has named Adam Smith as the Chairman of its Direct-to-Consumer business, which is its streaming unit.
DIS Stock Forecast
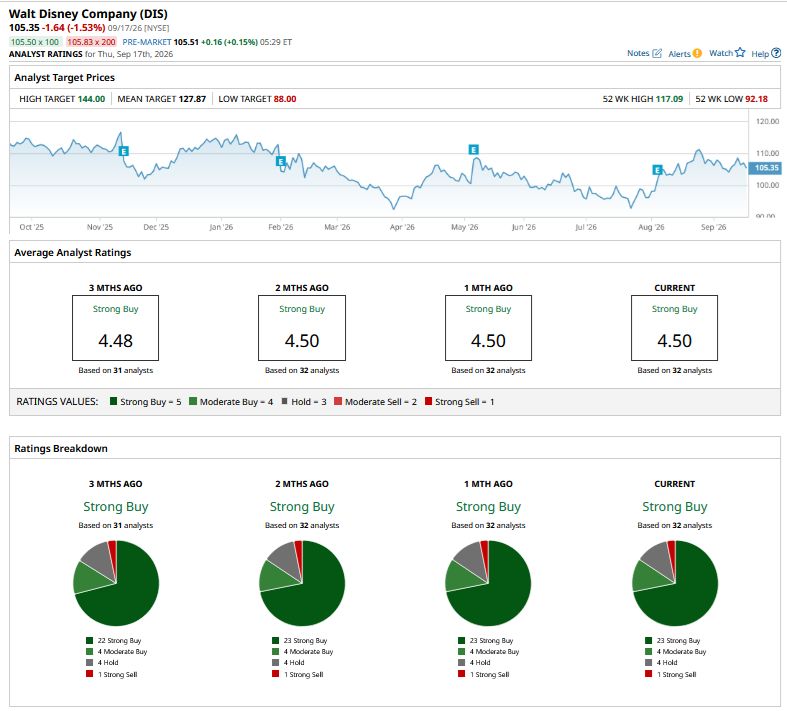
There hasn’t been much analyst action on DIS stock over the last couple of months. There were cursory adjustments to target prices after fiscal Q3 earnings last month, but no major revisions. Of the 32 analysts polled by Barchart, 23 rate DIS as a “Strong Buy” and four as a “Moderate Buy.” Four analysts rate Disney as a “Hold,” while one analyst has given the stock a “Strong Sell” rating. Disney’s mean target price of $127.87 is 21.4% higher than current levels.
 www.barchart.com
How to Play DIS Stock Now?
Owning a stock underperforming as terribly as Disney can be frustrating, especially at a time when the broader markets have given stellar returns over the period. That said, while Disney has been out of favor with markets, it remains a strong brand with a considerable moat. The business has several moving parts complementing each other. For instance, even if a movie flops at the box office, it can help drive merchandise sales while adding to the streaming library. It is the literal “cradle-to-grave” business, offering something for practically every age group.
However, despite its cheap valuations, I don’t see a near-term trigger that can push DIS stock higher. I continue to believe that it is a value stock and can deliver decent returns over the next couple of years. However, I am not too inclined to add more shares at these levels, particularly as the correction in tech names has created some interesting opportunities elsewhere.
On the date of publication, Mohit Oberoi had a position in: DIS , NFLX . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.