

POET Technologies (POET) holds a striking amount of cash for a company of its size. After a $400 million raise this year, it sits on about $796 million in cash and short-term investments. In comparison, it has a debt of just $7.80 million, making it essentially debt-free. Yet its actual business is almost invisible. Revenue last quarter was just $570,000, and for all of 2025, it brought in about $1 million.
Interestingly, the market values it at just twice the cash it holds. There are reasons for that, but the management believes investors should look past those reasons. Here's a look at what the company does.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
POET builds something called an “optical interposer.” Think of it as a base layer that lets light-based chips and electronic chips sit together in one small package. It’s made using the same mass-production methods as regular chips. That lowers cost and avoids assembling each unit slowly by hand. This matters because AI data centers are struggling to move data between chips fast enough. Light-based connections are the fix the industry is chasing, and POET wants to supply them at scale.
The market it’s targeting is projected to exceed $30 billion by the early 2030s, so the potential is huge. And POET has landed real orders too, including a $50 million deal with Lumilens that could grow past $500 million over five years.
Lately, though, that optimism has taken some hits. The stock has fallen from about $21 in May to under $8. A dilutive $400 million share sale, a short-seller accusing POET of overhyping its business deals, and several securities lawsuits have all hit at once. CEO Suresh Venkatesan defended that raise, saying it removes any doubt about whether the company can survive long enough to deliver. He says it also lets management focus on execution. The cash pile is what buys POET time through it all. It lost over $23 million in the first half of the year, so that money funds the long, costly road from lab to real production.
About Poet Technologies' Stock
POET Technologies makes light-based chip components that help AI data centers move data faster. Its products are built on its Optical Interposer platform, which aims to cut cost and power use. Originally incorporated in 1972, the company is based in Toronto, Canada, and is led by CEO Suresh Venkatesan.
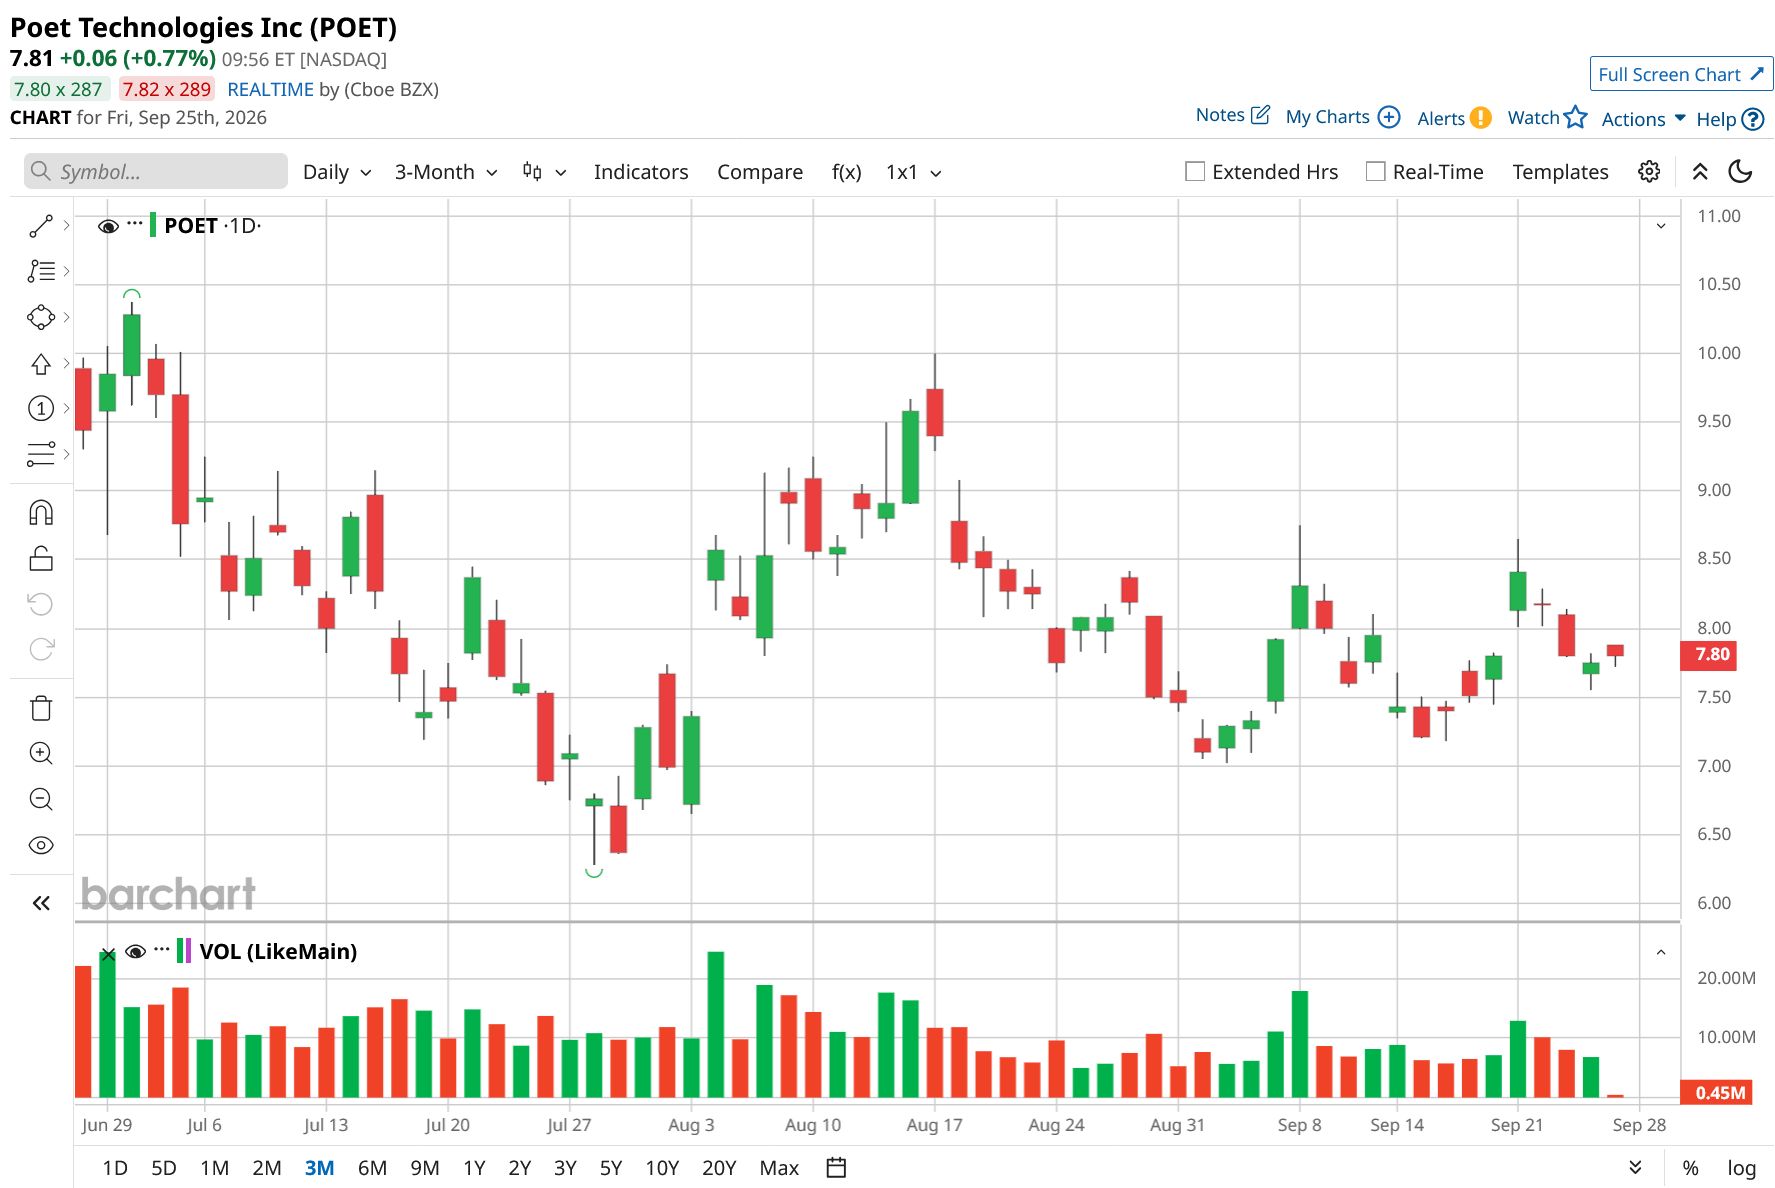
POET stock is up about 26% over the last 12 months, well behind the iShares Semiconductor ETF’s (SOXX) 113% gain. After hitting a decade high of $20.81 in mid-May, it has since fallen to around $7.80.
 www.barchart.com
Earnings Show Strength In Business
POET Technologies Inc. reported its second-quarter fiscal 2026 earnings on Aug. 13. The company reported revenue of $569,925, up 13% from the first quarter and 112% year-over-year (YoY). The earnings per share came in at -$0.07, marginally beating Wall Street consensus of -$0.08. Net loss narrowed to $11.3 million from $12.3 million in the first quarter. Moreover, the company ended the quarter with $796.3 million in cash and short-term investments following completion of its $400 million financing in May. The company signed a strategic partnership with Lumilens to develop advanced photonic technology for AI infrastructure. As part of the deal, Lumilens placed an initial $50 million order for the company’s POET Optical Interposer-based engines.
The company’s CEO, Suresh Venkatesan, said the second quarter showed the company is moving from development toward generating more revenue. He highlighted its sixth consecutive quarter of revenue growth, a smaller net loss, and the company’s optical engine production ramp remaining on track for the second half of 2026.
What Do Analysts Expect for POET Stock?
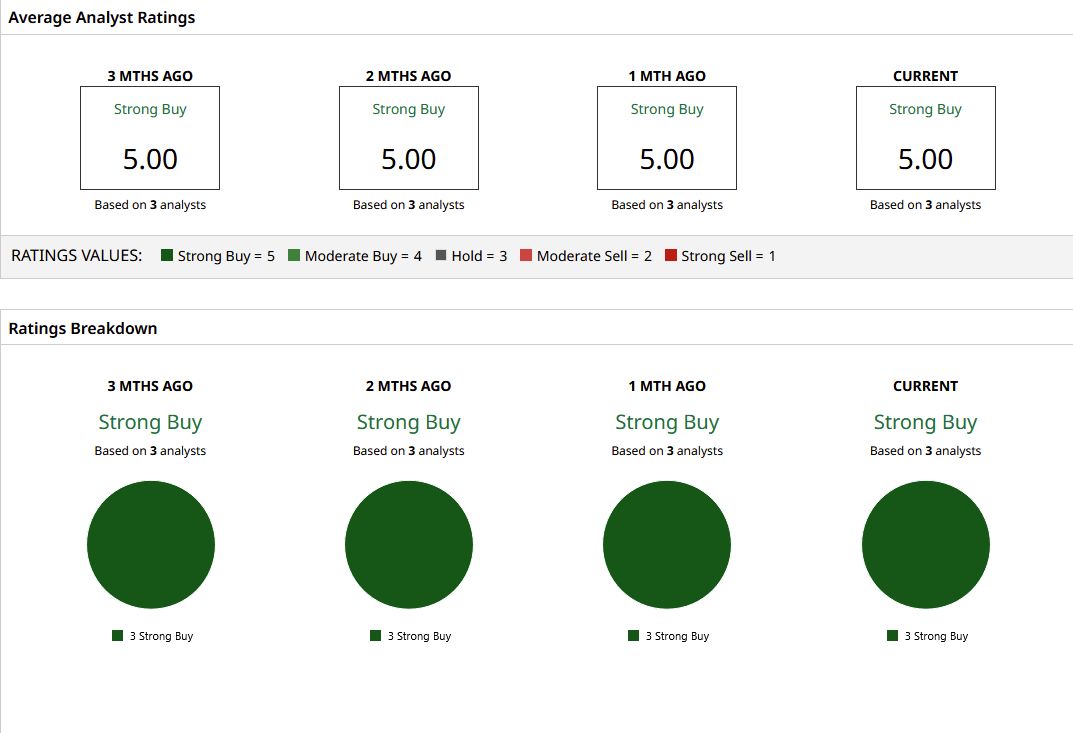
The firm does not receive sizable coverage from Wall Street, with only three analysts covering the stock. All three of those analysts rate it a “Strong Buy” with a mean price target of $13.38, indicating a healthy 72% upside.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This Photonics Company Trades at 2x Its Cash. Here’s What It Does, and Whether You Should Buy It. Analysts Keep Hiking Broadcom Price Targets, But AVGO Is Flat - Shorting AVGO Puts Is an Attractive Play Dave Ramsey Warns Car Debt Will ‘Suck The Bone Marrow Out Of Your Money’ as 1 In 5 New-Car Buyers Now Pays Over $1,000 a Month Here Is How to Play Accenture Stock After a New AWS Collaboration