

Healthpeak Properties, Inc. (DOC), with a market capitalization of approximately $6.2 billion, is a prominent healthcare real estate investment trust that owns, operates and develops outpatient medical and life science properties. The Denver, Colorado-based company owns approximately 700 properties that support healthcare providers, scientists and researchers across major U.S. markets.
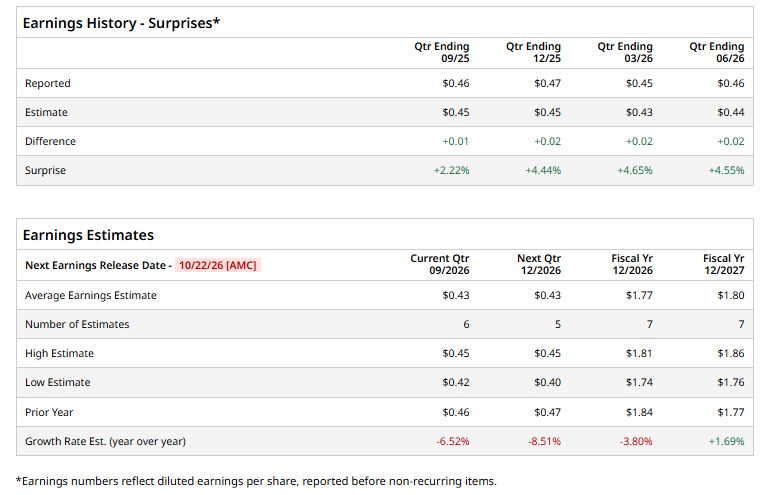
DOC is set to report its Q3 earnings on Monday, November 3, 2026, after the market closes. Ahead of the release, analysts expect the company to report diluted EPS of 43 cents, down 6.5% from 46 cents in the year-ago quarter. That said, DOC has exceeded Wall Street’s EPS estimates in each of the past four quarters, highlighting its consistent earnings performance.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts expect DOC to report EPS of $1.77, down 3.8% from $1.84 in fiscal 2025. However, DOC’s EPS is projected to grow 1.7% year over year to $1.80 in fiscal 2027.
 www.barchart.com
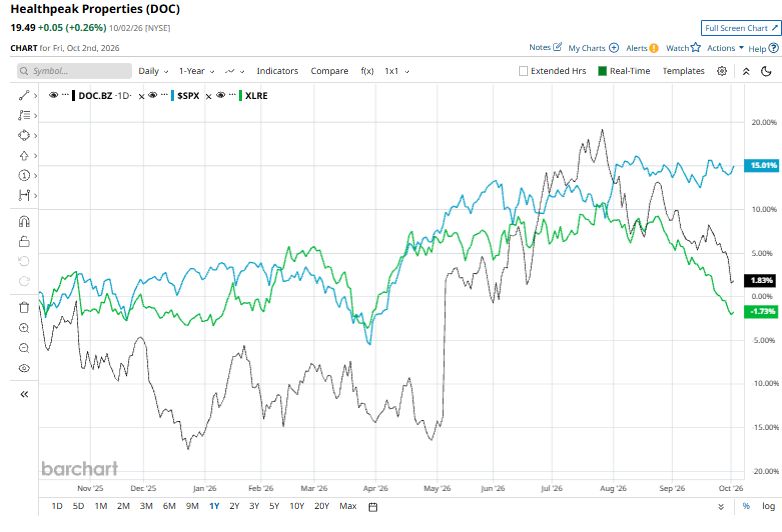
DOC stock has risen 1.6% over the past 52 weeks, underperforming the S&P 500 Index ($SPX), which gained 15%, but outperforming the State Street Real Estate Select Sector SPDR ETF (XLRE), which declined 2.6% over the same period.
 www.barchart.com
Healthpeak’s recent performance has been supported by better-than-expected financial results and continued shareholder returns. On August 4, the company reported second-quarter FFO of 46 cents per share, beating analysts’ estimate of 44 cents, while revenue of $771.6 million also exceeded expectations. Healthpeak maintained its full-year FFO guidance of $1.73 to $1.77 per share. More recently, on October 1, the company declared a monthly dividend of $0.10167 per share, equivalent to an annualized $1.22, reinforcing its commitment to returning capital to shareholders.
Analysts remain somewhat bullish on DOC, with the stock carrying a consensus “Moderate Buy” rating. Of the 22 analysts covering the stock, six recommend a “Strong Buy,” one rates it a “Moderate Buy” and 15 suggest a “Hold.” Meanwhile, the average price target of $22.76 implies potential upside of 16.8% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
NVO vs. LLY: Novo’s CEO Says Confidence Is Gone. Lilly Is Winning 7 in 10 New Seniors. Nvidia Bull Put Spread Could Return 16% U.S. Stock Futures Muted as Europe’s Turmoil Curbs Risk Appetite; Fed Minutes Awaited As Starship Finally Reaches Orbit, Here’s How You Should Place SpaceX Stock