

Valued at $90.1 billion by market cap, AppLovin Corporation (APP) is a leading mobile advertising and marketing technology company that helps businesses acquire users, monetize apps, and optimize digital advertising performance. The California-based company provides tools for ad targeting, analytics, and revenue optimization, enabling developers and brands to grow and monetize their digital products efficiently.
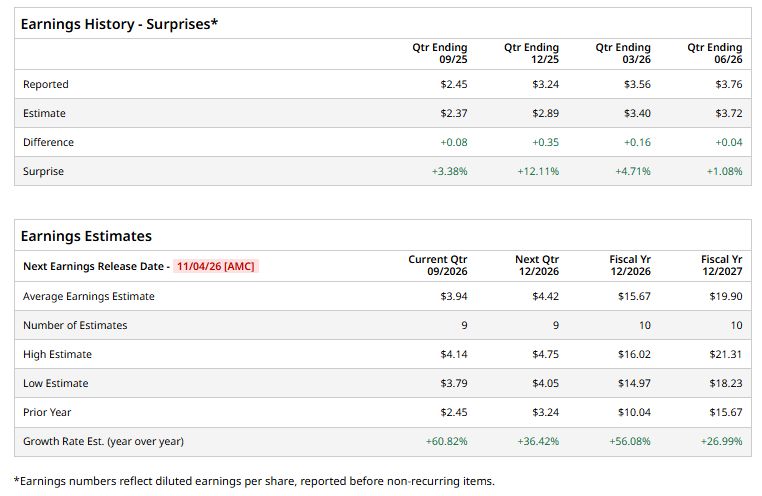
The advertising giant is expected to announce its fiscal third-quarter earnings for 2026 after the market closes on Wednesday, Nov. 4. Ahead of the event, analysts expect APP to report a profit of $3.94 per share on a diluted basis, up 60.8% from $2.45 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the current year, analysts expect APP to report EPS of $15.67, up 56.1% from $10.04 in fiscal 2025. Its EPS is expected to rise 27% year over year to $19.90 in fiscal 2027.
 www.barchart.com
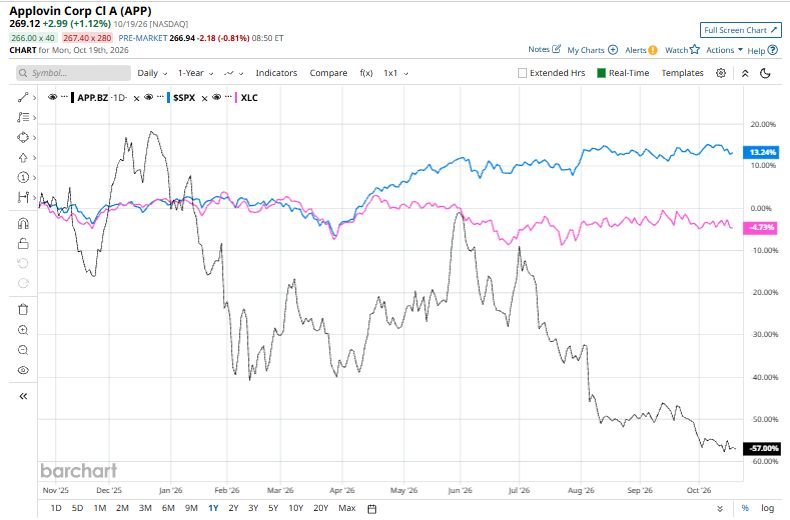
APP shares have fallen 53% over the past year, significantly underperforming the S&P 500 Index’s ($SPX) 15.4% gains and the State Street Communication Services Select Sector SPDR ETF’s (XLC) 5.5% downtick over the same time frame.
 www.barchart.com
AppLovin has lagged the broader market over the past year as concerns about its AI advertising technology, slower-than-expected product development, and mounting legal scrutiny have undermined investor confidence.
Yet, analysts’ consensus opinion on APP stock is bullish, with a “Strong Buy” rating overall. Out of 30 analysts covering the stock, 21 advise a “Strong Buy” rating, two suggest a “Moderate Buy,” and seven give a “Hold.” APP’s average analyst price target is $483.10, indicating a potential upside of 79.5% from the current price levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear United Airlines Stock Fans, Mark Your Calendars for October 20 AutoZone Stock is Up and Price Targets are Still High - What's the Best AZO Play? Caterpillar vs. Deere: The Better Heavy Equipment Stock for the Data Center Boom TSMC Stock Just Delivered Another Blowout Quarter. Why It's a Buy for the Next 10 Years.