

Q3 earnings season is in full swing and will gain further traction this week as Big Tech companies, including Alphabet (GOOG) (GOOGL), Amazon (AMZN), and Microsoft (MSFT), release their quarterly reports. While these multi-trillion-dollar giants' earnings calls have always drawn outsized attention, they have become even more market-moving since 2023, when artificial intelligence (AI) emerged as the dominant investing theme.
Markets, particularly the tech universe, have been pretty much divided into two halves amid the AI pivot. On one hand are companies considered “AI winners” that are investing heavily in the technology, even though, in most cases, it is not accompanied by commensurate growth in current earnings. Then we have what are considered “AI losers,” which include software and IT services firms. There are concerns over the very business models of these companies amid the threat of AI disruption.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Adobe Is Considered an “AI Loser”
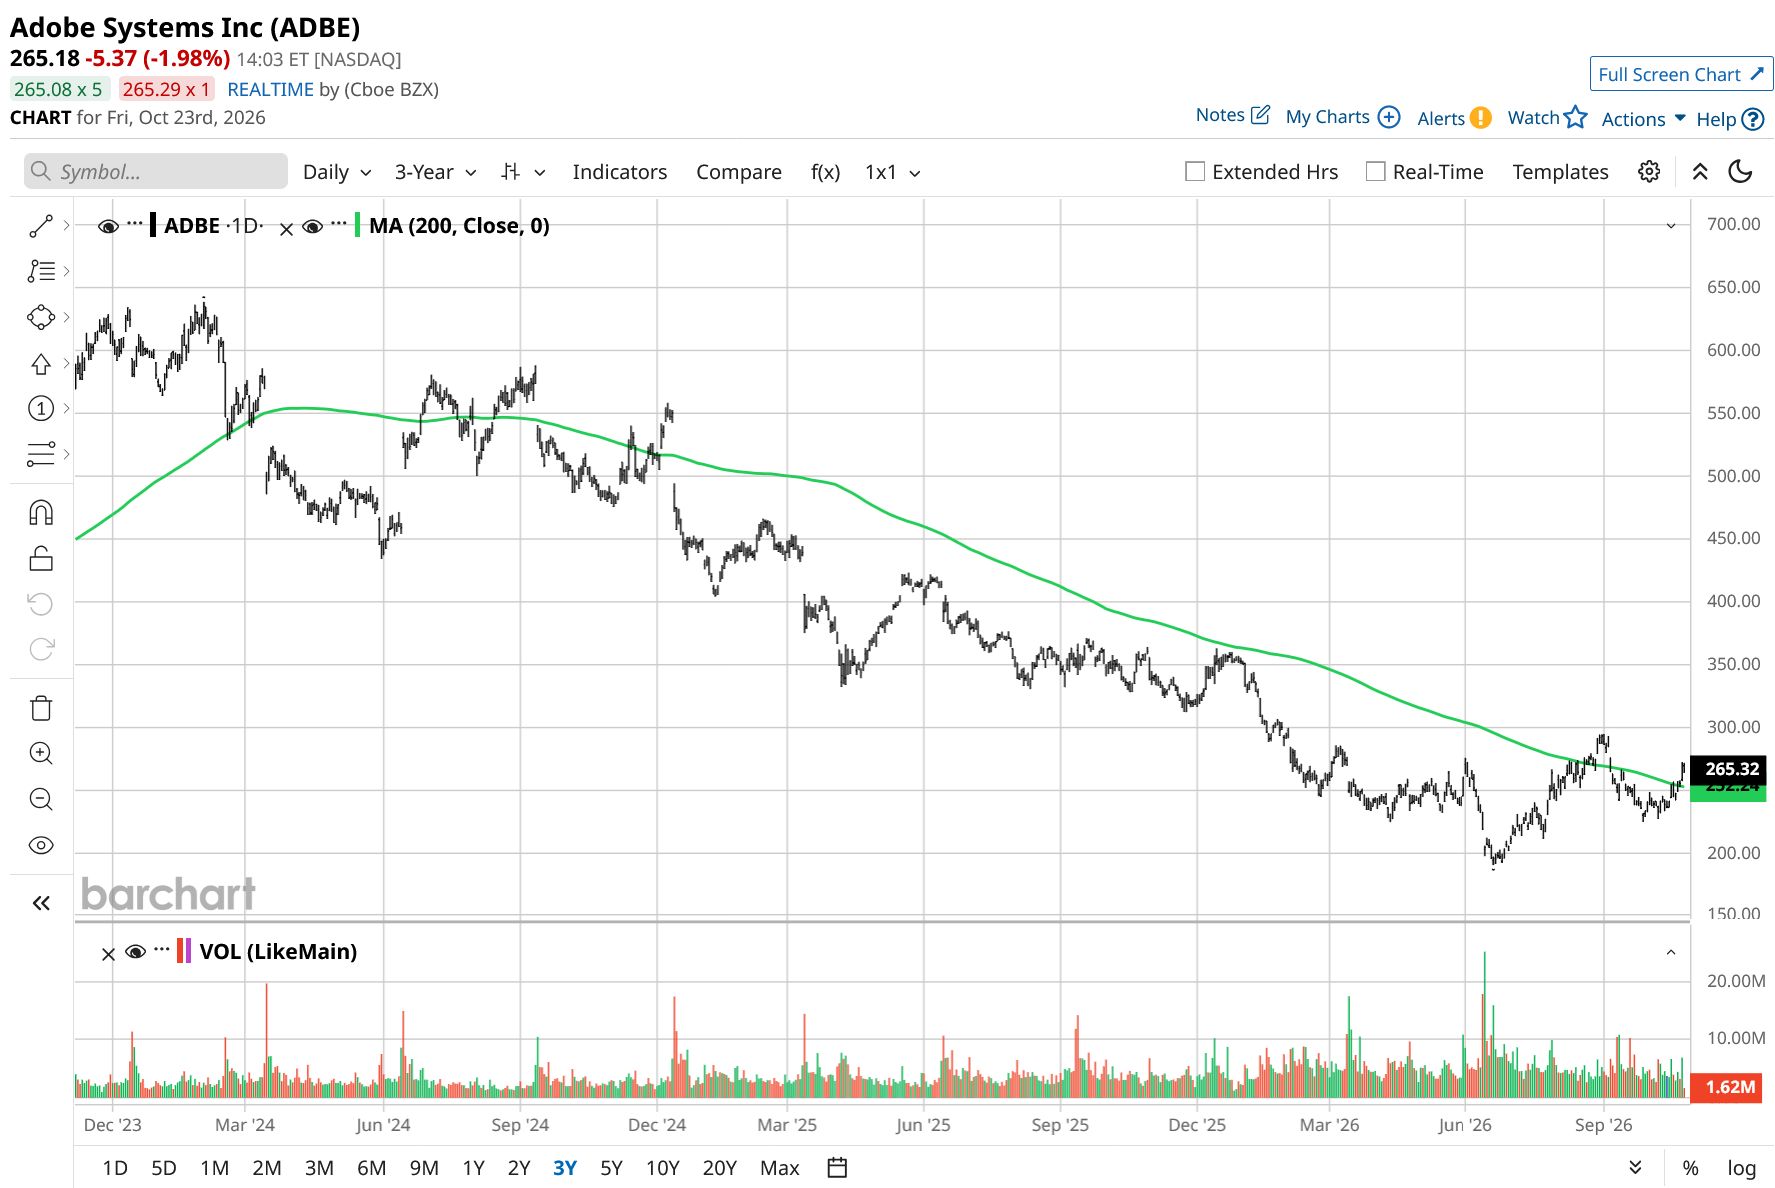
Unsurprisingly, the price action of these two sets of companies has diverged. When fears emerge over AI being a bubble or about tech companies’ burgeoning AI capex, AI winners tend to fall in tandem, while the other set, which includes the likes of Adobe (ADBE), rallies. Adobe has been quite volatile this year, and while the stock is still down over 24% for the year, it has risen 39% from its 2026 lows that it hit in June.
 www.barchart.com
In my previous article, I noted that Adobe stock was a buy despite all the challenges. With the stock now up considerably from those levels, let’s revisit the analysis, especially as Big Tech companies report their earnings this week, which could also impact Adobe’s price action. Incidentally, the key reason ADBE stock rallied on Thursday, Oct. 22, was that AI names crashed following Q3 earnings of Meta Platforms (META) and Tesla (TSLA).
Adobe Stock Forecast
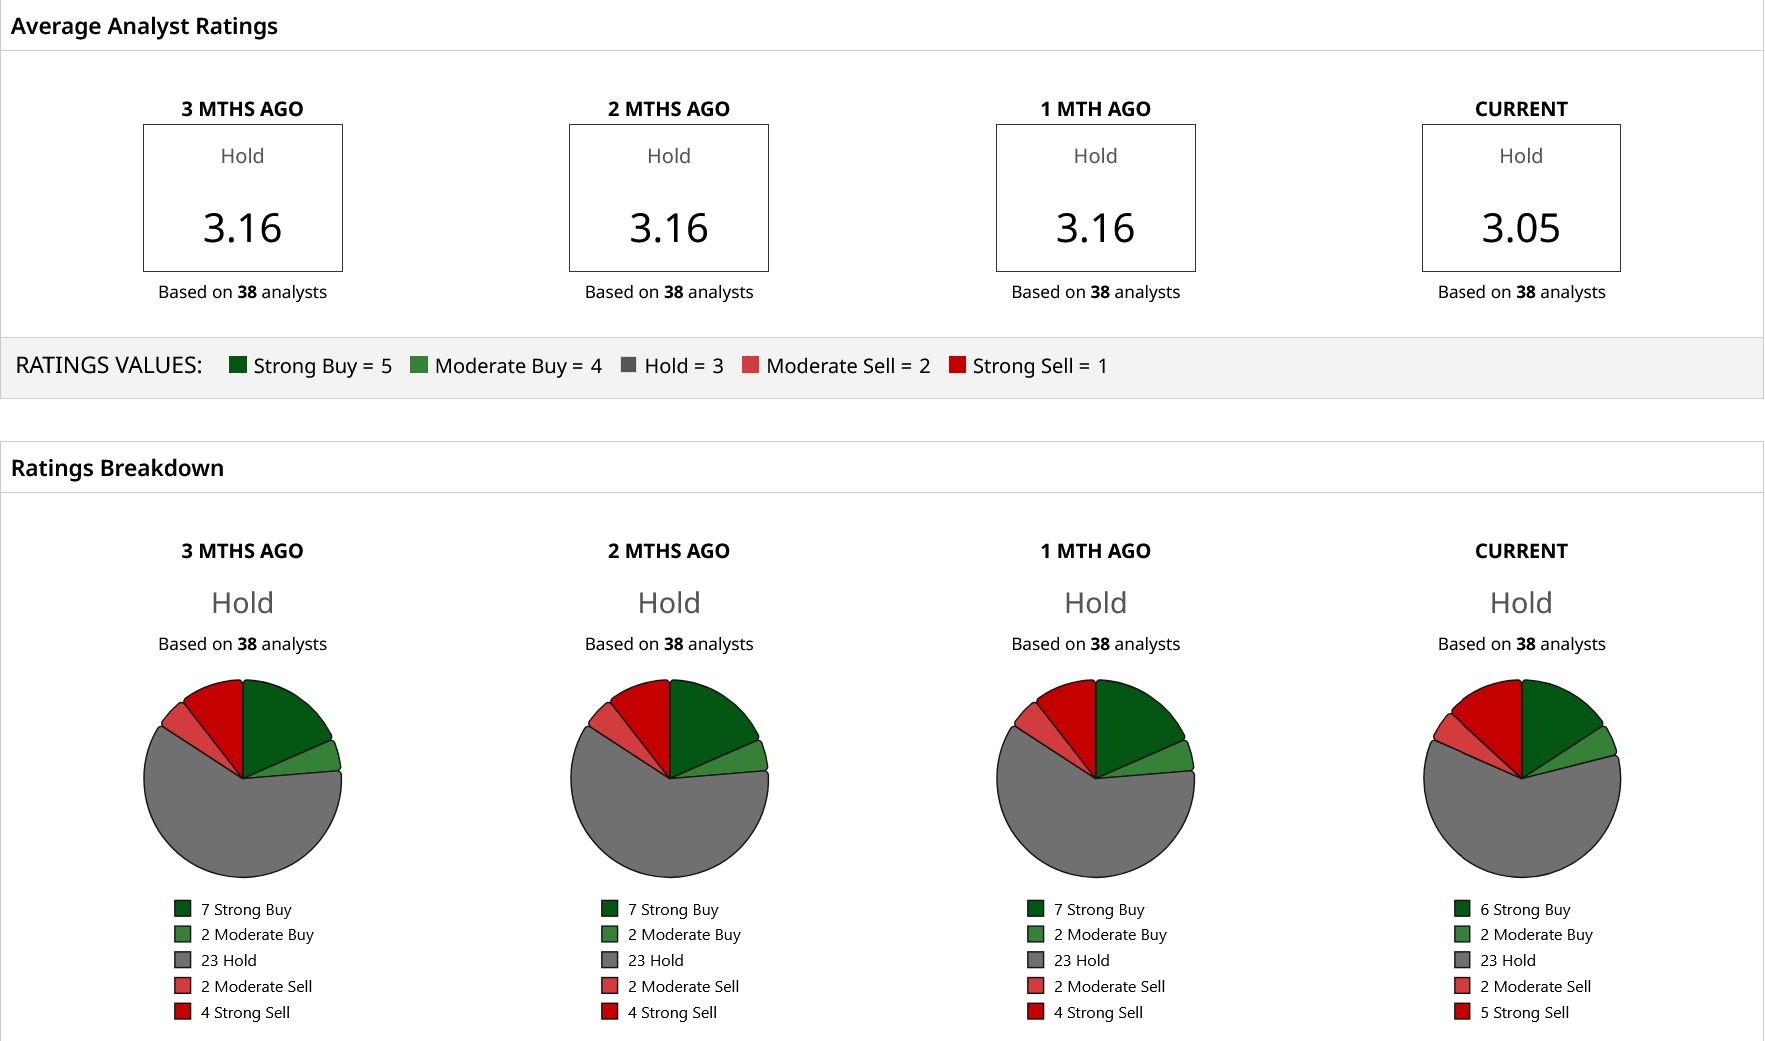
Notably, amid AI disruption fears, sell-side analysts have been getting bearish on Adobe. Earlier this month, HSBC downgraded the stock from a “Buy” to “Hold” and lowered its target price from $310 to $267. Wells Fargo analyst Michael Turin went a step further and double-downgraded Adobe from “Overweight” to “Underweight” and slashed his target price from $270 to $225.
Currently, only 21% of analysts tracked by Barchart rate Adobe as a “Buy” or equivalent, and its consensus rating is “Hold.” For context, in June 2025, almost 74% of analysts tracking Adobe rated it as a “Buy.” The stock hasn’t been rated lower, and its target price sits at $267.85, almost matching the current price.
 www.barchart.com
Battling a Growth Slowdown
Wall Street’s pessimism towards ADBE is not difficult to comprehend. In its fiscal Q3 2026, Adobe's remaining performance obligations (RPOs) grew 8% year-over-year (YoY), which was the first time since fiscal 2023 that the metric grew in single digits. Adobe’s annualized recurring revenue growth is also slowing down, and the company expects it to rise 10.2% in the current fiscal year. The growth slowdown is quite palpable, which has been worsened by AI disruption fears. For instance, ArtCraft recently released open-source alternatives to Adobe’s Creative Cloud by basically reverse-engineering Adobe tools using Claude.
Adobe is also undergoing a leadership transition and has a new CEO. The company is under an interim CFO after previous CFO Dan Durn departed in June to join Marvell Technology (MRVL). The optics of the CFO of a software company joining a chipmaker were hard to ignore given how central chips are to AI while software companies are at the receiving end of the technology.
How to Play ADBE Stock This Earnings Season?
Buying Adobe is ultimately a function of how one sees AI playing out. For those who see the technology eating software in due course, Adobe is that stock they wouldn’t proverbially touch with a 10-foot pole. On the other hand, for those who see AI as a bubble, ADBE stock would be a tempting buy at a forward price-to-earnings (P/E) multiple of 12.83x and a P/E-to-growth (PEG) multiple of 0.90x. Adobe is also a free cash flow powerhouse, unlike Big Tech companies whose once-enviable free cash flows have fallen prey to AI capex.
All said, while I see Adobe as among the best “anti-AI” plays out there, I would be wary of adding it here after the sharp rally over the last couple of weeks, as some earnings disappointment from Big Tech companies already seems to have been priced into the stock. I would, however, keep it on my radar as a play to bet against AI disruption.
On the date of publication, Mohit Oberoi had a position in: TSLA , META , MSFT , AMZN , GOOG . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Adobe Stock Is the Best ‘Anti-AI’ Play This Earnings Season Option Volatility and Earnings Report For Oct 26 - 30 U.S. Stock Futures Gain as Oil Slides; Big Tech Earnings and Fed Meeting Awaited CRWV Stock Warning: Why Bernstein Says CoreWeave Shares Haven’t Bottomed Out Yet