

International Business Machines (IBM) has spent the last couple of years trying to convince investors it's more than an old-school technology giant. A quarter ago, IBM’s software story looked less comfortable, with delayed deals and timing issues clouding the outlook. The third quarter brought better news as the software business accelerated, showing strength across key areas, including Red Hat and data software.
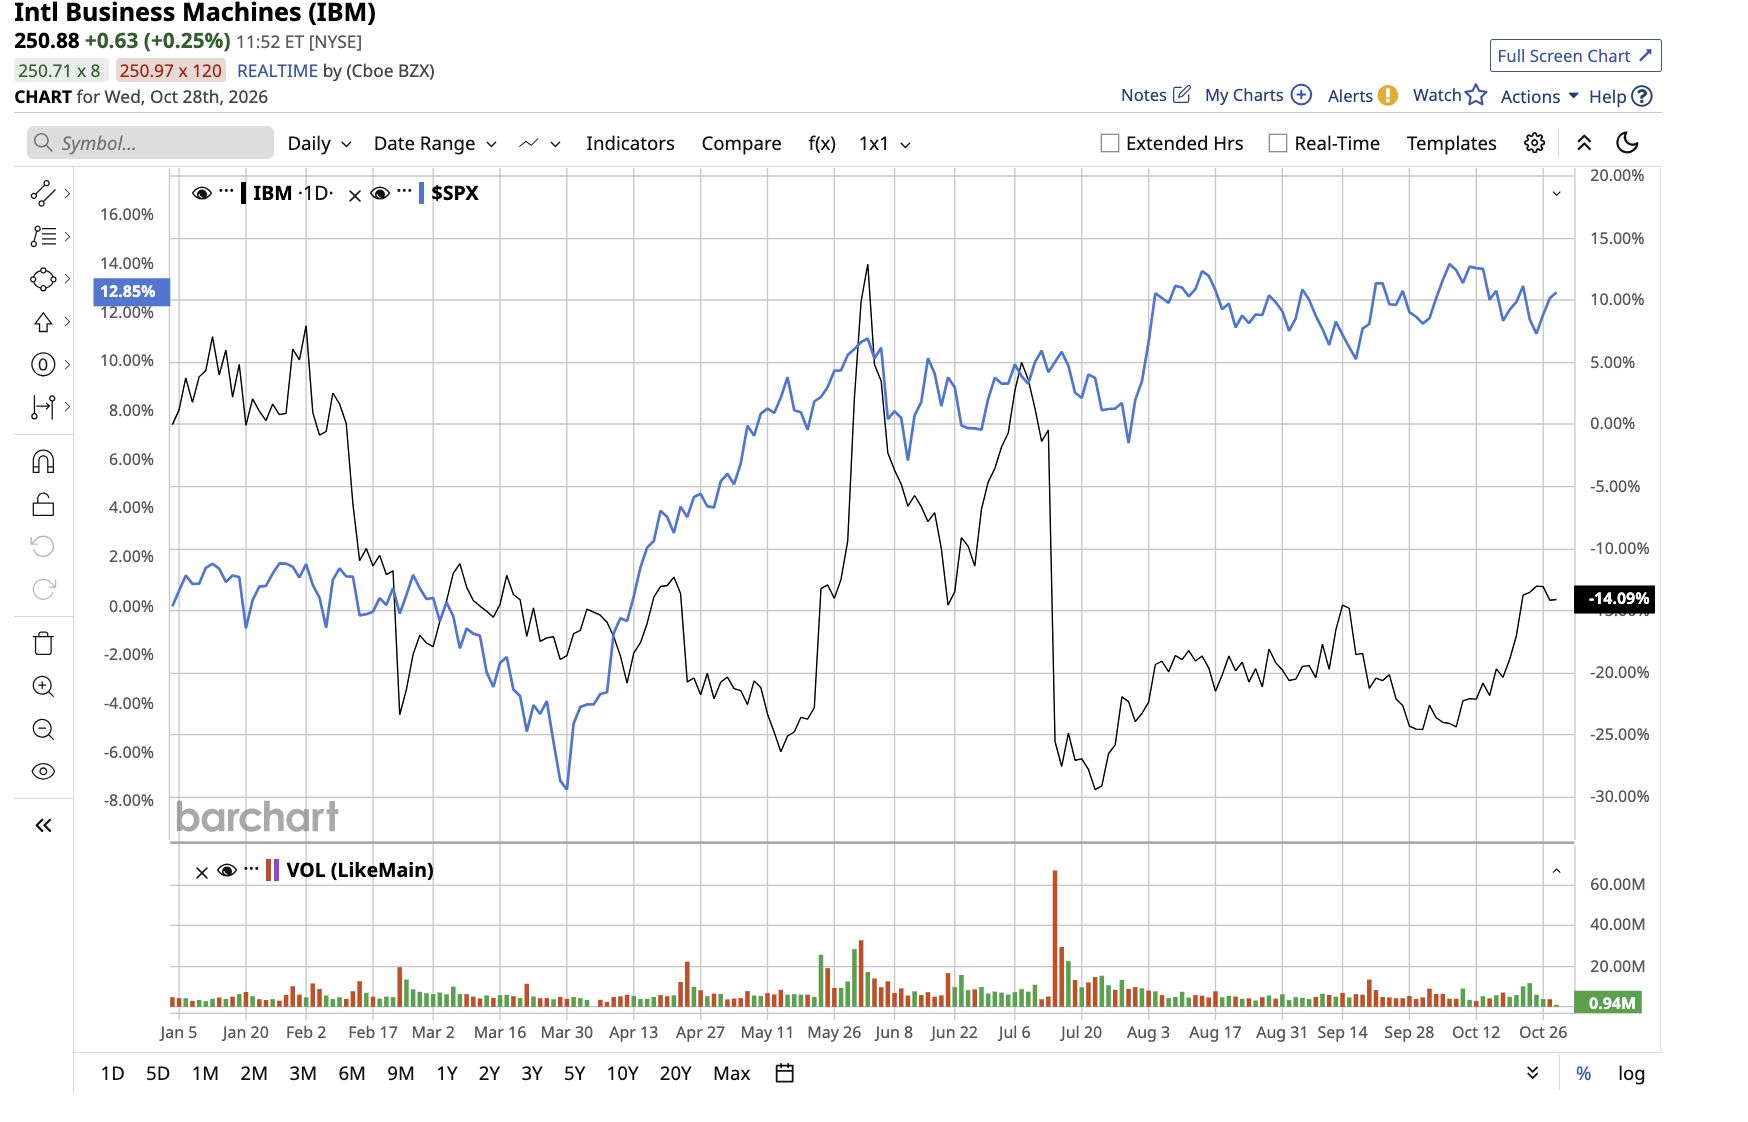
Yet, IBM shares remain well below their $332.46 peak and are down 14% so far this year. If this momentum continues into the coming quarters, investors buying the dip could enter before the market fully recognizes the improvement in IBM’s software business.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
A Beaten-Down Stock Meets a Better Earnings Story
Trouble began brewing as IBM’s software business lost momentum. Software revenue climbed just 5% year-over-year (YoY) in the second quarter, down sharply from 11% in the first quarter and 14% in the fourth quarter of 2025. The slowdown was upsetting because software has been central to IBM's transformation beyond its legacy hardware business. Investors had counted on this segment to drive stronger growth, so the disappointing numbers hurt confidence in the strategy. Management pointed to the company’s failure to close several large software deals on schedule, leading to a delay in recognizing revenue. Yet lingering uncertainty about when that missing revenue might arrive continued to drag on the stock.
The third quarter gave a more encouraging picture. IBM generated $17.1 billion in revenue, up 5% YoY. Software revenue reached $7.8 billion, increasing 8% over the year-ago quarter and accounting for roughly 46% of total revenue. Adjusted earnings per share rose 11% to $2.95 from the year-ago quarter. During the Q3 earnings call, management stressed that software growth rose by four percentage points to reach 9% in the third quarter, backed by IBM's robust recurring-revenue base and sharper deal execution. CFO Jim Kavanaugh noted that three of four software sub-segments posted strong double-digit revenue gains, driven by a wave of new business and more effective pipeline conversion. IBM also won about two-thirds of the major deals it had missed in the second quarter. This mix of new wins and reclaimed contracts signals a rebound that goes beyond timing, pointing to deeper, more sustained momentum.
Red Hat, Data Software, and AI Give Investors a Reason to Look Ahead
Red Hat continues as a key driver of IBM's software business. Its revenue grew 11% in the third quarter, while bookings growth returned to the high teens. OpenShift, its hybrid cloud application platform, reached $2.4 billion in annual recurring revenue, growing more than 30%. Furthermore, its data software business grew 20%, partly supported by Confluent, whose bookings rose about 20%. Enterprise AI applications need reliable, timely data. This creates opportunities for companies that help businesses manage and use information productively. IBM could benefit as customers move from experimenting with AI to applying it to everyday operations.
The stronger results prompted management to lift its full-year software revenue growth forecast to about 7% to 8%. IBM expects double-digit growth in hybrid cloud, mid-teens growth in data, and low double-digit growth in automation. These forecasts suggest management expects several software businesses to boost growth rather than rely on a single segment. Cash generation brings fresh momentum to the bull case. IBM generated an impressive $3 billion in free cash flow, up $700 million from last year, and now expects full-year free cash flow growth to exceed $1 billion. Management pointed out expanding margins in both software and infrastructure, fueled by productivity gains from internal AI and automation. With this cash surge, IBM is prepared to invest more boldly in its portfolio and keep rewarding shareholders. The company boasts a forward dividend yield of 2.7%, outpacing the tech sector average. With 31 consecutive years of dividend increases, it proudly holds the Dividend Aristocrat title.
Overall, Red Hat's momentum, double-digit data software growth, better deal execution, higher full-year expectations, and a steady dividend strengthen IBM's bull case. The challenge is sustaining that performance beyond one quarter. Investors who trust IBM to convert enterprise AI demand into software revenue and cash flow may see the recent share price weakness as a buying opportunity.
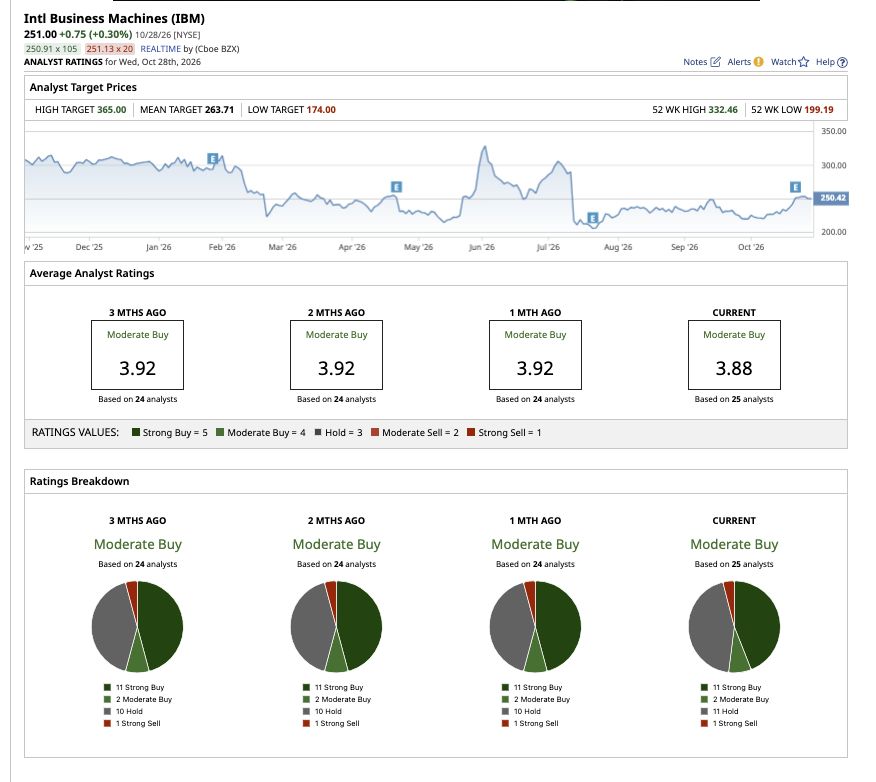
Despite the year-to-date (YTD) decline, IBM stock has started to recover, climbing roughly 1% over the past five days. Analysts expect the stock to rally 4% from current levels based on its average price target of $263.71. Plus, the high target price of $365 implies a 44% upside over the next 12 months.
On Wall Street, IBM stock has an overall “Moderate Buy” consensus. Out of the 25 analysts covering the shares, 11 have a “Strong Buy,” two have a “Moderate Buy” recommendation, 11 have a “Hold” rating, and one says it is a “Strong Sell.”
 www.barchart.com
On the date of publication, Sushree Mohanty did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Christine Lagarde Will Leave the ECB 9 Months Early — But the Real Crisis Is What Her Successor Inherits IBM’s Software Business Is Picking Up Speed. Here’s Why It’s Time to Grab IBM Stock on the Dip. Fed Chair Warsh Refuses to Call Financial Conditions 'Tight' — and That Single Phrase May Have Just Locked In a December Rate Hike ‘I Still Live A Great Life’: Floyd Mayweather Says a Man ‘Acting Like He Was A Friend’ Stole $200 Million From Him