

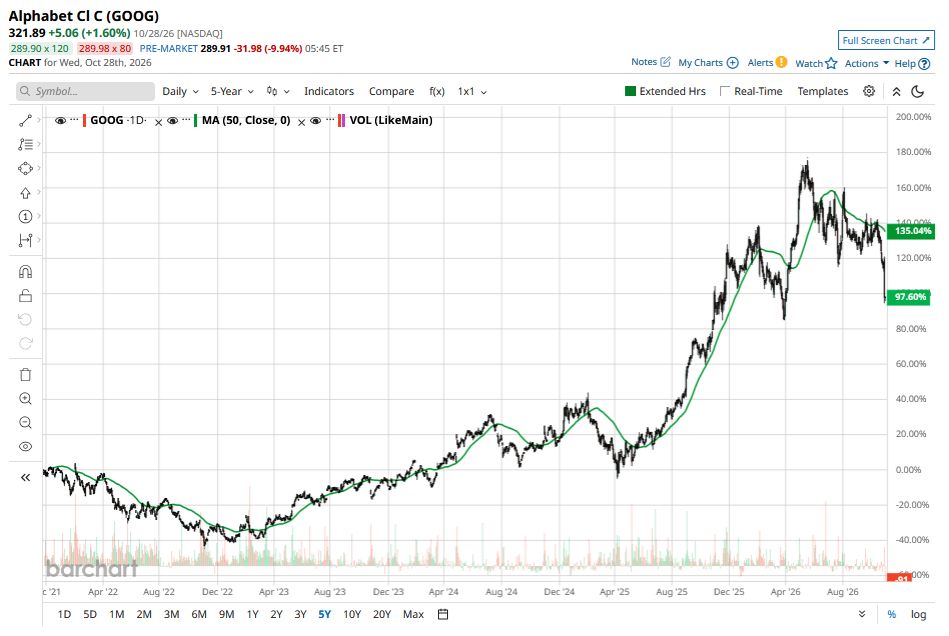
Alphabet (GOOG) (GOOGL) released its Q3 earnings on Oct. 28, after markets closed. The search giant’s earnings missed on most metrics and dampened the already tepid sentiment towards the stock. GOOG is trading sharply lower today, reminiscent of the crash after its Q2 earnings.
Following today’s crash, Alphabet has turned negative for the year and further expanded its underperformance versus its average Magnificent 7 peer. It is quite a reversal of fortunes for GOOG, which was the best-performing Mag 7 stock last year with 65% gains.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
After being bearish on Alphabet for much of this year, mainly on valuation and soaring artificial intelligence (AI) capex, I noted that the stock was well set up heading into Q3 earnings. However, the earnings were disappointing and were far worse than the previous report, where at least the stellar beat on cloud revenues was a major positive.
Alphabet Missed on Most Metrics in Q3
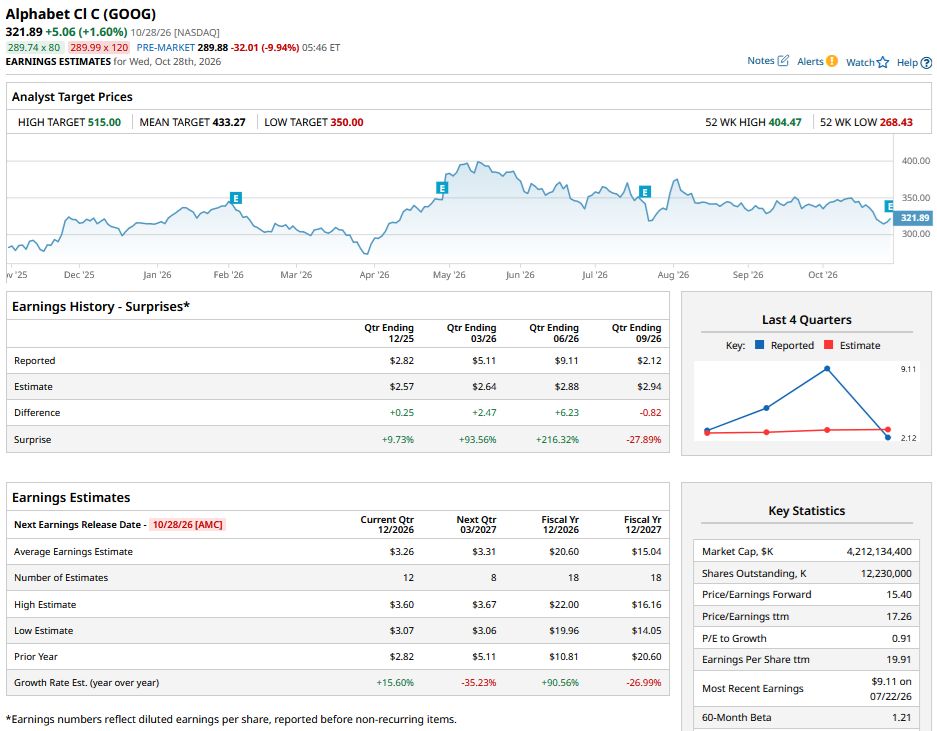
This time around, Alphabet missed on both the top line and the bottom line, and while cloud revenues doubled in the quarter, they were largely in line with estimates. If anything, they fell short of some of the optimistic estimates. Just as with Nvidia (NVDA), the bar is not the “consensus” but the Street-high estimate when it comes to Google’s cloud business. The company failed to clear that bar, which added fuel to the sell-off.
Alphabet’s Search revenues also decelerated in Q3 when compared with the previous quarter. There were headwinds from adverse forex movements and some ad budgets getting drawn to Q2 due to the FIFA World Cup, but lower monetization in AI mode is also to blame. While Alphabet is scaling ads in AI overviews and AI mode, for now the monetization is below what it generates in traditional search.
Alphabet Warns of ‘Significant’ Increase in 2027 Capex
During my pre-earnings analysis, I noted that Alphabet needs to calm nerves over its AI capex. The company maintained its 2026 capex budget but warned of a “significant” increase next year, reserving more details for the next earnings call.
The AI buildout is taking a toll on Alphabet’s free cash flows, and it reported negative free cash flows of $9.1 billion in Q3, marking its second consecutive quarter of cash burn. The company warned that its growing capex “will put pressure on free cash flows," signalling more quarters of cash burn.
While CFO Anat Ashkenazi said that Alphabet is uniquely positioned “to be able to monetize our AI investments across many products that reach billions of users and enterprises,” markets have stopped buying that often repeated story of AI driving long-term growth and are looking for signs of current monetization along with a timeline for positive free cash flows.
Alphabet’s commentary on capex and free cash flows failed to calm nerves. As I noted previously, one of the reasons Microsoft (MSFT) has soared from its 2026 lows is because the company forecasted positive free cash flows next year despite the increase in capex. Markets want to hear something similar from other tech giants, especially as rising interest rates make the AI buildout even more costly.
GOOG Stock Looks a Buy Below $300
I previously booked profits when Alphabet stock soared past $400. The stock had run ahead of fundamentals at its peak, and its valuations appeared stretched. However, as Alphabet stock falls below $300, I believe it looks like an attractive “buy” despite all the concerns discussed above.
Consensus estimates call for Alphabet to report earnings per share (EPS) of around $15 next year. At a stock price of $300, it gives us a 2027 price-to-earnings (P/E) multiple of 20x, which is quite decent. The company has several growth drivers for 2027 and beyond, including its Tensor Processing Units (TPUs), whose third-party sales are expected to increase significantly next year.
 www.barchart.com
There are macro risks from a slowing global economy amid high inflation taking a toll on ad spending and lower monetization in AI overviews, coupled with rising search competition from other AI companies impacting Alphabet's core Search business. However, I believe the risks seem more than baked into prices, and I am increasing my GOOG holdings following the crash.
On the date of publication, Mohit Oberoi had a position in: MSFT , GOOG , NVDA . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Alphabet's Earnings Horror Show Continues, But GOOG Stock Is a Buy Below $300 Reddit Sinks as Google's AI Shift Takes a Bite Out of Search Traffic. What's Next for RDDT Stock. How to Play the Nasty Post-Earnings Selloff in Enphase Stock Oracle Surges 10% on Ambitious New Targets: 3 Questions to Answer Before Dumping ORCL Stock