

Qualcomm (QCOM) is navigating an increasingly complicated semiconductor landscape, one that looks markedly different from the environment that fueled its earlier growth. While smartphones remain a cornerstone of its business, changing industry conditions, escalating component costs, and Apple (AAPL) efforts to develop its own modem technology are introducing fresh uncertainties into the company's growth outlook.
These headwinds have also taken a toll on Qualcomm’s shares. On Friday, Oct. 30, QCOM stock tumbled 11.2% after Intel's earnings triggered sectorwide concerns about memory shortages and slowed consumer spending in the PC market. Last month was particularly rough, as QCOM was caught up in a technology-led selloff, as inflation concerns, rising Treasury yields, and a broader shift toward risk aversion rattled investors.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
The pressure is not limited to demand, though. Rising memory prices and supply constraints, partly fueled by the growing appetite for components from artificial intelligence (AI) data centers, are increasing smartphone manufacturing costs. This could complicate production schedules and further strain consumer demand, particularly among price-sensitive Android OEMs.
However, there is another side to Qualcomm's business. Its growing automotive, Internet of Things (IoT), data-center computing, and AI infrastructure operations are opening up opportunities beyond smartphones.
So, when the company publishes its Q4 and FY2026 results on Wednesday, Nov. 4, after the market closes, it will offer a fresh look at how these businesses are developing alongside its established operations.
About Qualcomm Stock
Qualcomm develops and commercializes wireless technologies across global markets, with a diversified portfolio spanning semiconductor solutions, intellectual property licensing, and strategic investments. Beyond its core technology operations, the company also delivers network security, government services, and data center solutions, supporting its roughly $176 billion valuation.
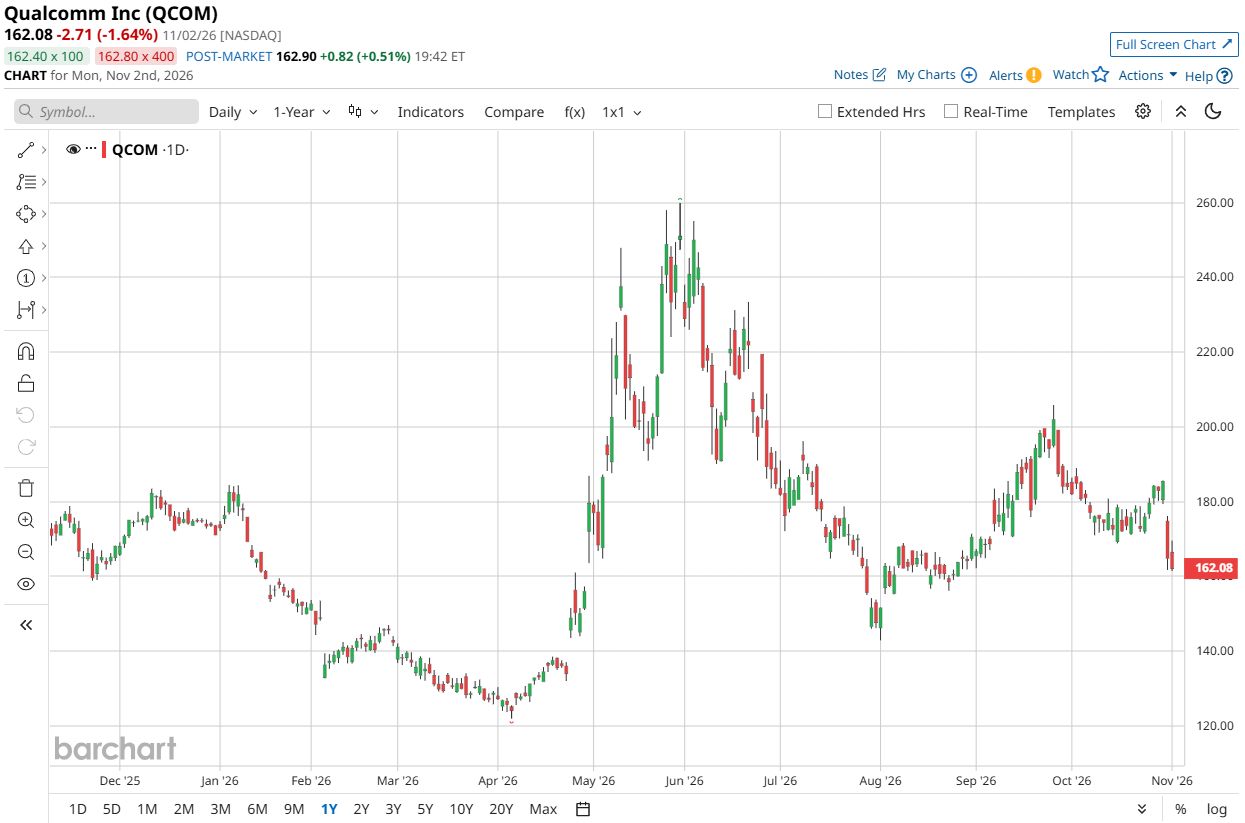
Qualcomm's recent price performance has been less encouraging. Shares of the San Diego, California-based tech giant have fallen 9% over the past 52 weeks. The decline has continued into 2026, with the stock down 4% year-to-date (YTD), while in the past month alone, shares have plunged 11%.
 www.barchart.com
From a valuation perspective, QCOM stock is currently trading at 15.66 times forward adjusted earnings, below the industry average. The discount points to Qualcomm's relatively modest valuation compared with its peers, despite the challenges affecting its recent performance.
The company has also increased its dividend for 22 consecutive years and currently distributes an annual dividend of $3.68 per share, representing a yield of 2.23%. Most recently, on Wednesday, Oct. 21, Qualcomm announced a quarterly cash dividend of $0.92 per common share. The payment is scheduled for Thursday, Dec. 17, to stockholders of record at the close of business on Thursday, Dec. 3.
A Closer Look at Q3 Earnings
On July 29, Qualcomm reported mixed financial results for Q3 FY2026. Revenue came in at $9.95 billion, down 4% year-over-year (YoY), but ahead of the Street's estimate of $9.66 billion. Non-GAAP EPS, meanwhile, declined 20.2% YoY to $2.21, narrowly missing analysts' expectations of $2.22.
Although revenue reached the upper end of management's guidance, earnings highlighted the mounting pressure from softer handset demand, more expensive memory components, and elevated manufacturing costs. The biggest weakness came from Qualcomm CDMA Technologies (QCT), where revenue declined 5.4% YoY to $8.5 billion.
Within this segment, Handset revenue dropped 19.6% YoY to $5.09 billion, reflecting an industry contraction compounded by memory-related supply constraints and rising component expenses. However, Qualcomm's diversification efforts offered some welcome relief.
Automotive revenue jumped 61.4% from the year-ago value to $1.59 billion, while IoT revenue increased 8.9% from the last year’s quarter to $1.83 billion. These gains underscore the growing contribution of businesses outside the traditional smartphone market.
Profitability, however, remained under pressure. Non-GAAP operating income declined 22.4% YoY to $2.8 billion, while non-GAAP net income dipped 22.5% from the prior year's period to $2.4 billion. Looking ahead, management expects Q4 FY2026 revenue to land between $9.7 billion and $10.5 billion, with non-GAAP EPS projected at $2.05–$2.25.
Analysts, however, are taking a more cautious view of the near-term earnings trajectory. Estimates call for Q4 FY2026 EPS to decrease 43% YoY to $1.46. For full FY2026, analysts project EPS to plunge 23.4% from the previous year to $7.71, followed by another 7% decline to $7.17.
What Do Analysts Expect for QCOM Stock?
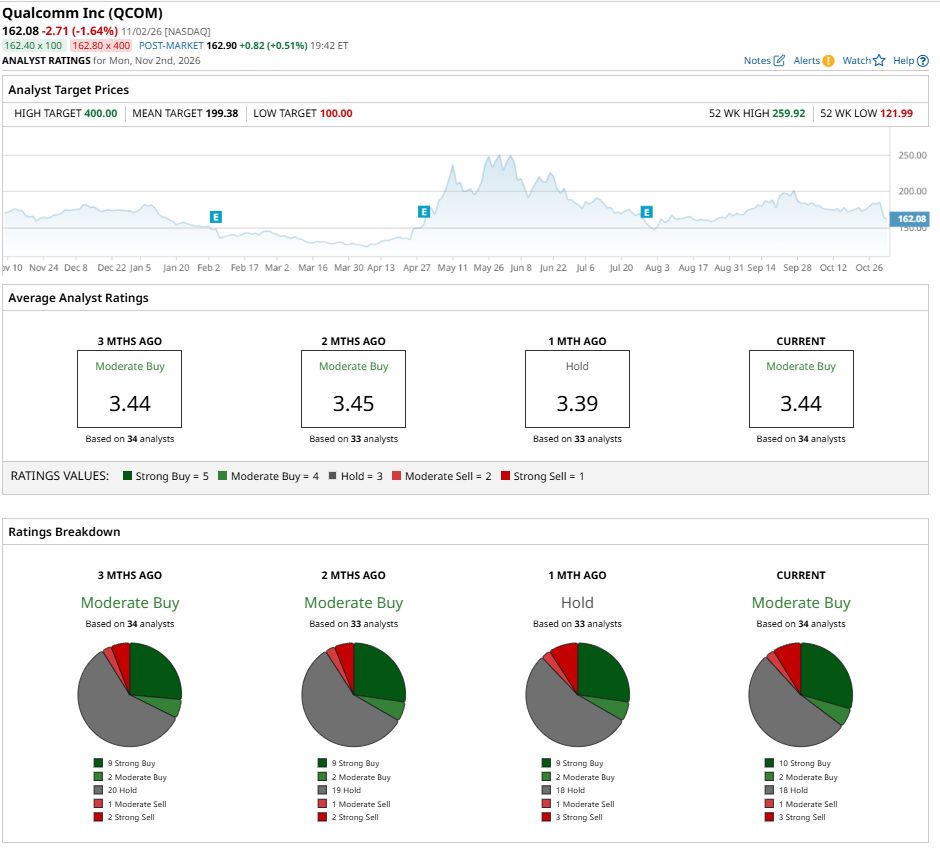
Despite the recent share-price weakness and near-term earnings concerns, Wall Street's overall assessment of Qualcomm remains relatively constructive. Analysts covering the stock have assigned it an overall rating of “Moderate Buy.”
Of the 34 analysts following QCOM stock, 10 recommend a “Strong Buy,” while two maintain a “Moderate Buy” rating. Another 18 recommend “Hold” on QCOM. On the more cautious end, one analyst has issued a “Moderate Sell” rating, while three have assigned a “Strong Sell.”
To that end, the average price target stands at $199.38, implying potential upside of 23%. Meanwhile, the Street-high target of $400 points to a potential gain of 147% from current levels.
 www.barchart.com
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear Qualcomm Stock Fans, Mark Your Calendars for November 4 GOOGL Stock Is Down 10% YTD. Alphabet’s Historic Selloff Could Be a Buying Opportunity. Dear Arm Stock Fans, Mark Your Calendars for November 4 Dear Arista Networks Stock Fans, Mark Your Calendars for November 3