

Google parent Alphabet (GOOGL) recently became a victim of one of the most common emotions in the stock market: an overreaction. Investors have already had a prevalent fear of artificial intelligence (AI) spending and whether the returns will be able to justify growing tech capital expenditures. With that fear in the background, Alphabet just committed the proverbial cardinal sin of missing revenue and earnings estimates in its third-quarter results, while also reporting its second consecutive quarter of negative free cash flow.
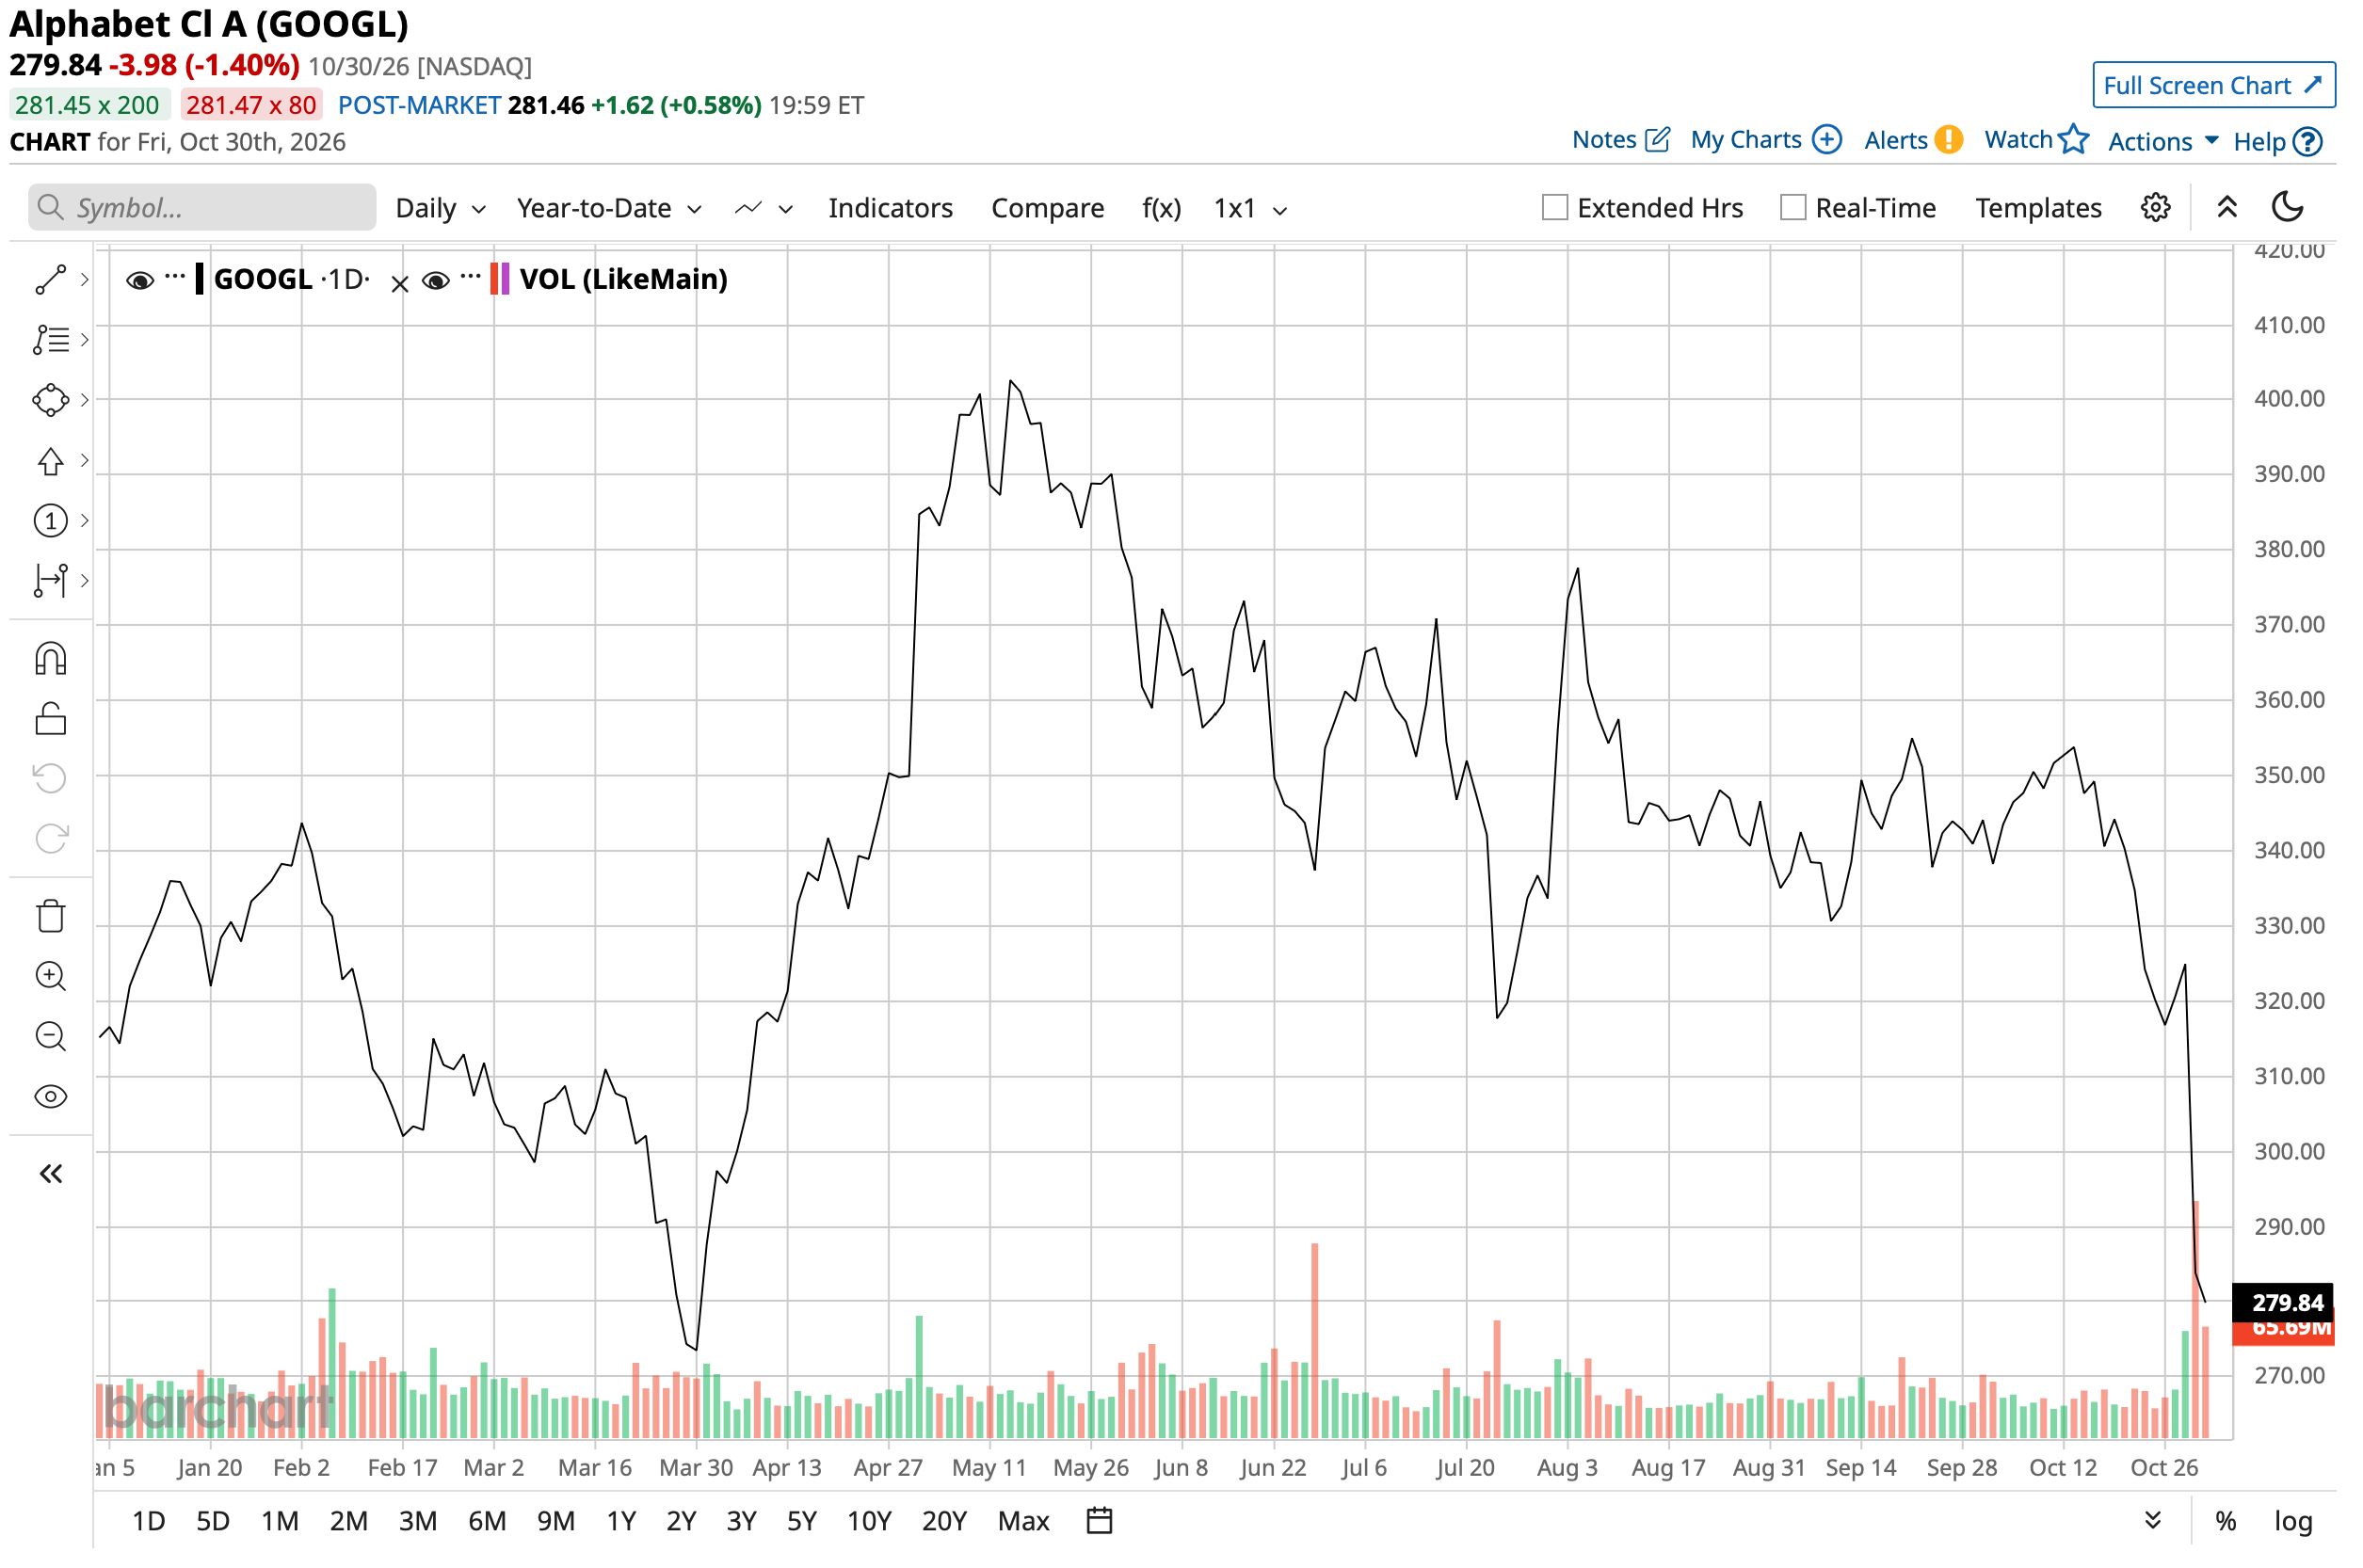
That was enough to send GOOGL stock on a downward spiral, with Alphabet stock falling almost 13% on Oct. 29. Alphabet has been under pressure this year, falling by 11% on a year-to-date (YTD) basis. Still, it remains one of the most valuable companies in the world with a market capitalization of $3.4 trillion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Has the recent dip emerged as an opportunity to load up on GOOGL stock now? Let's take a closer look.
 www.barchart.com
Alphabet Reports Q3 Results
Apart from the earnings miss and negative free cash flow, softer growth in Alphabet's Search business also spooked the markets. Some market participants reckon that users may be shifting away from Google Search for their search needs and using chatbots from the likes of OpenAI and Anthropic (ANT), as well as Google Gemini. Worries are also emerging that Google's AI Mode has less monetization potential than the company's traditional search business, despite AI Mode initially being hailed as Google's answer to the challenge from generative AI platforms.
Of course, the recent Q3 misses were disappointing, but the numbers themselves do not derail the investment thesis around GOOGL stock. In Q3 2026, Alphabet reported revenue of $127.6 billion, up 25% from the previous year. Crucially, all of the company's major revenue segments showed year-over-year (YOY) growth. Search continued to remain its most dominant business with $63.35 billion in revenue, marking 12% YOY growth. However, that growth came in below expectations. Overall, Google's advertising business — which also includes YouTube Ads and Google Network — showed revenue of $82 billion, up 11% YOY.
Google Cloud revenue stood at $30.71 billion in Q3, more than doubling from the prior year. Google Cloud was also the fastest-growing cloud provider compared to Amazon's (AMZN) AWS and Microsoft (MSFT) Azure. Notably, backlog climbed to $561 billion at the end of Q3, with the company expecting more than half of that figure to be recognized over the next two years.
Earnings fell by 26% YOY to $2.12 per share as total costs and expenses rose by 22%, driven by a 36% rise in R&D expenses to $20.6 billion. Overall, earnings missed the consensus estimate of $3.02 per share.
Meanwhile, Alphabet reported free cash flow of -$9.1 billion in Q3 2026. Yet, net cash provided by operating activities for the nine months ended Sept. 30, 2026 was $127.1 billion, a rise of 13% YOY. For the quarter, net cash provided by operating activities came in at $42.3 billion, down from $48.4 billion in the prior-year quarter. Overall, Alphabet closed the quarter with a cash balance of $56.3 billion. However, long-term debt levels rose to $125.1 billion, with interest expense jumping to $967 million for the quarter.
GOOGL stock continues to trade at relatively overvalued levels. Its forward price-to-earnings (P/E) ratio of 13.9 times, price-to-sales (P/S) ratio of 8.5 times, and price-to-cash flow ratio of 22 times are all above the respective sector medians.
In terms of Google's AI models, the impact of the recently released Gemini 4 Argon has been somewhat underwhelming when compared to the buzz generated around GPT-6 Astra or Claude Fable. Yet, on the Q3 earnings call, CEO Sundar Pichai revealed a three-pronged strategy for the firm to be a formidable player in the AI model space. For its most recent model, Carbon, management also noted that access would initially be limited to selected cybersecurity firms, before being gradually widened to additional trusted partners through its Fairwind Program. Google is still gathering feedback and refining safeguards before a broader release to developers, businesses, and consumers, although the company has not specified a release date.
What Do Analysts Think of Alphabet Stock?
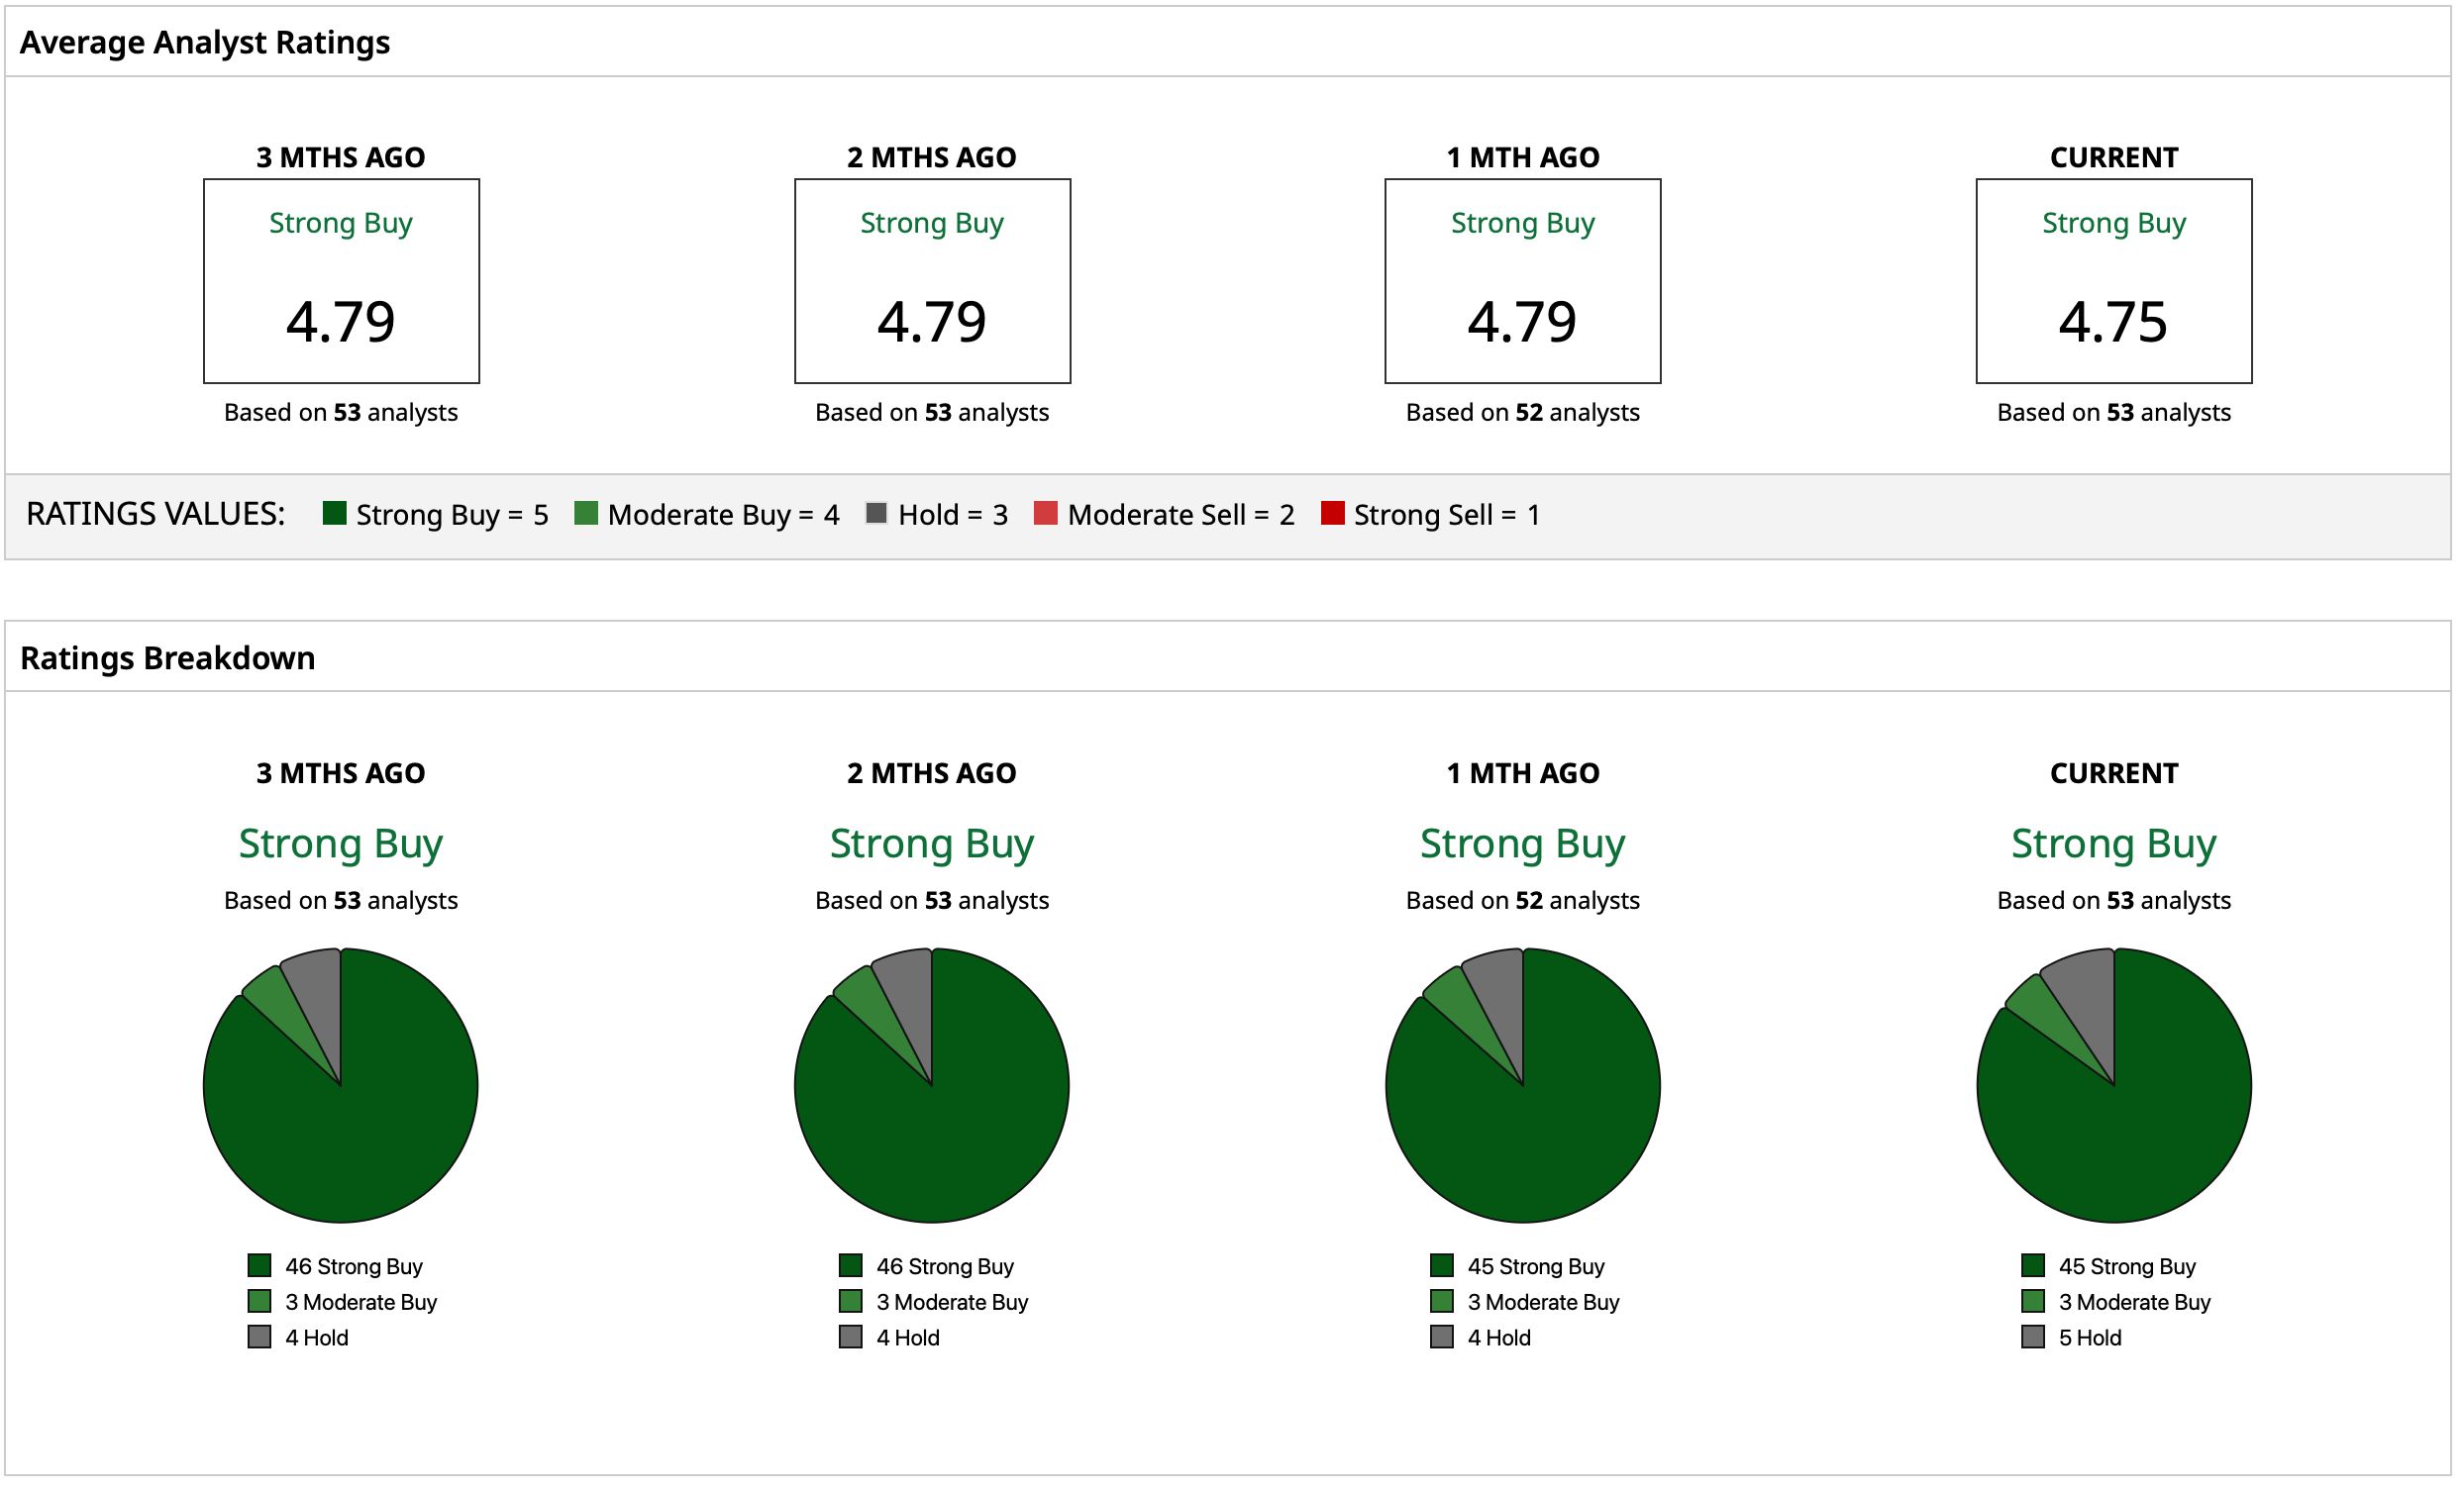
Overall, analysts have a consensus “Strong Buy” rating for Alphabet stock despite the recent selloff and Q3 disappointment. Out of 53 analysts covering the stock, 45 have a “Strong Buy” rating, three have a “Moderate Buy” rating, and five have a “Hold” rating. The mean price target of $404.21 denotes potential upside of 44% from current levels.
 www.barchart.com
On the date of publication, Pathikrit Bose did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Investors Should Load Up on Google Stock Now CrowdStrike Stock Is Climbing, but 1 Risk Could Derail the Rally Intel’s Earnings Disaster Exposed a Problem Investors Shouldn’t Ignore Billionaire Mark Cuban Says the Hardest Part of Fixing Health Costs Isn’t the CEOs or Insurance Companies, ‘Employees Fight Any Change’