

Businesses are exploring stablecoins to manage cash and make payments, including across borders. In October, Visa (V) said that payment volume across its more than 160 stablecoin-linked card programs grew nearly 200% year-over-year (YOY).
Visa's latest results also showed growth. Fiscal fourth-quarter revenue rose 13% to $12.1 billion, while adjusted EPS of $3.48 slightly beat Wall Street’s expectations. The company also raised its quarterly dividend by 16.4% to $0.78 per share, payable on Dec. 1 to shareholders of record on Nov. 10.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
But is that bigger dividend enough to make Visa stock a buy today? Let’s find out.
The Numbers Behind the Bigger Payout
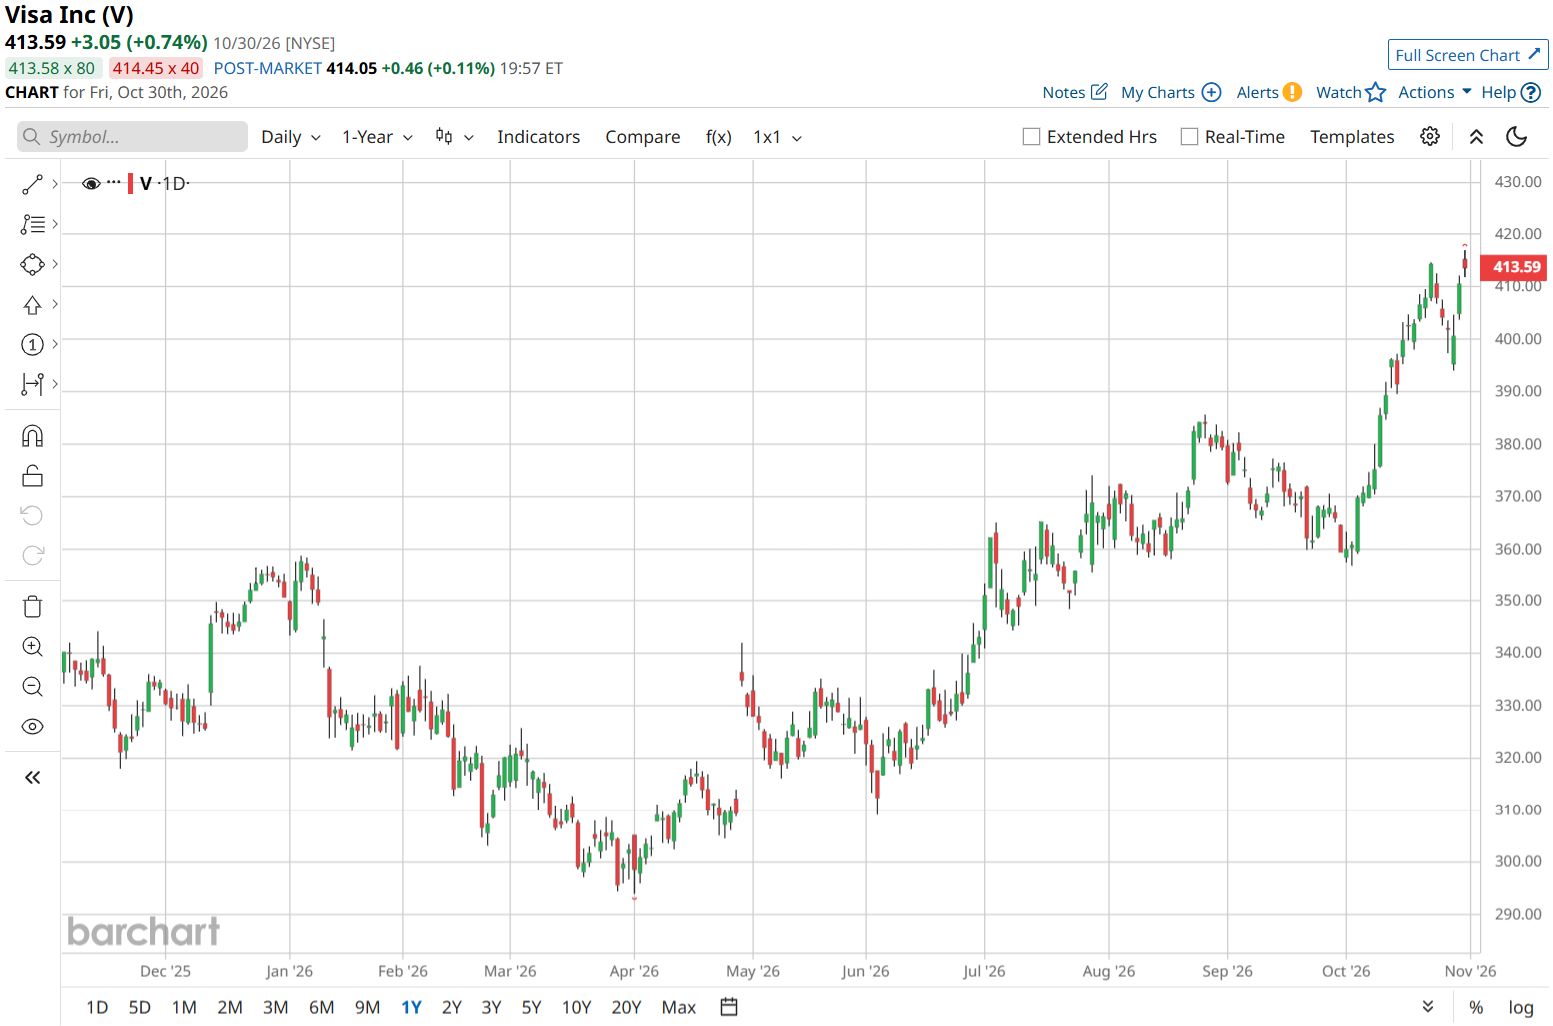
Visa earns fees by connecting consumers, merchants, and financial institutions through its payments network, rather than lending directly to cardholders. Shares of V stock have risen 25% over the past 52 weeks and 20% year-to-date (YTD).
 www.barchart.com
That leaves V stock trading at 27.5 times forward earnings. That's compared to the sector average of about 11 times.
Visa raised its quarterly dividend from $0.67 to $0.78, an increase of 16.4%. The new rate works out to $3.12 annually and a yield of roughly 0.74% at a share price of about $420. That annualized figure is not the amount paid during fiscal 2026. The next payment is due Dec. 1 to shareholders of record on Nov. 10.
Before the increase, the $2.68 annualized dividend yielded 0.65%, and the forward payout ratio was 19.09%. That relatively small share of earnings leaves room for further increases, following 18 years of dividend growth. Still, the new yield remains well below the financial sector average. Visa also returned cash through buybacks, with combined repurchases and dividends totaling $5.2 billion in the quarter and $25.6 billion for fiscal 2026.
Fiscal Q4 revenue rose 13% to $12.1 billion. GAAP net income increased 18% to $6 billion, while diluted EPS rose 22% to $3.19. Adjusted net income climbed 13% to $6.6 billion, and adjusted EPS increased 17% to $3.48. EPS grew faster than total profit, reflecting the benefit of fewer shares outstanding.
The full-year results showed similar progress. Revenue increased 15% to $45.9 billion, while GAAP net income rose 17% to $23.5 billion and diluted EPS increased 21% to $12.32. Adjusted net income grew 12% to $25.3 billion, with adjusted EPS up 16% to $13.27.
More payments moving through the network helped drive those gains. On a constant-dollar basis, payment volume grew 9% in both the quarter and the full year. Quarterly cross-border volume rose 14%, both overall and excluding transactions within Europe. For the full year, those measures increased 13% and 12%, respectively. Visa processed 74.2 billion transactions in the quarter, up 10%, and 281.3 billion across fiscal 2026, up 9% YOY.
Where Visa’s Next Growth Could Come From
Visa is reportedly in talks to buy Fireblocks for $2.5 billion, which is roughly 69% below its $8 billion valuation in January 2022. The deal would add tools for holding digital assets securely, settling stablecoin payments, and turning assets into blockchain-based tokens. Fireblocks' payment network reportedly handles more than $200 billion in stablecoin transactions per month.
Both companies already work together through Open Standard, a stablecoin infrastructure initiative. Still, the talks remain unconfirmed. Neither company has commented, and no deal has been announced.
Meanwhile, Visa, BILL (BILL), and Billtrust have launched a live trial that lets trusted artificial intelligence (AI) agents make approved invoice payments through supplier portals. Visa’s Trusted Agent Protocol verifies the agents, allowing them to handle steps that previously required a person to log in or enter information. Suppliers keep control over the payments while buyers spend less time entering details manually.
Visa is also adding tools to help businesses expand commercial-card use and check payments before approval. Supplier Enablement Spend Analytics 2.0 uses AI to review spending, identify suppliers worth approaching about card payments, and estimate the potential financial benefit. Meanwhile, Visa Commercial Fraud Solutions checks suppliers, verifies virtual-card payment activity, and applies payment controls before a transaction is approved.
Wall Street’s Outlook Meets Visa’s Valuation
Visa’s next earnings release is scheduled for Feb. 4, 2027. Analysts expect earnings of $3.63 per share for the December 2026 quarter, up about 15% from $3.17 a year earlier. For fiscal 2027, analysts forecast $15.03 per share, a roughly 13% YOY increase.
Price targets have also moved higher. Morgan Stanley recently raised its target to $471 from $416, TD Cowen increased its target to $450 from $420, and Oppenheimer lifted its target to $440 from $403. Susquehanna, Clear Street, and KeyBanc also raised their targets above $460 before the earnings report.
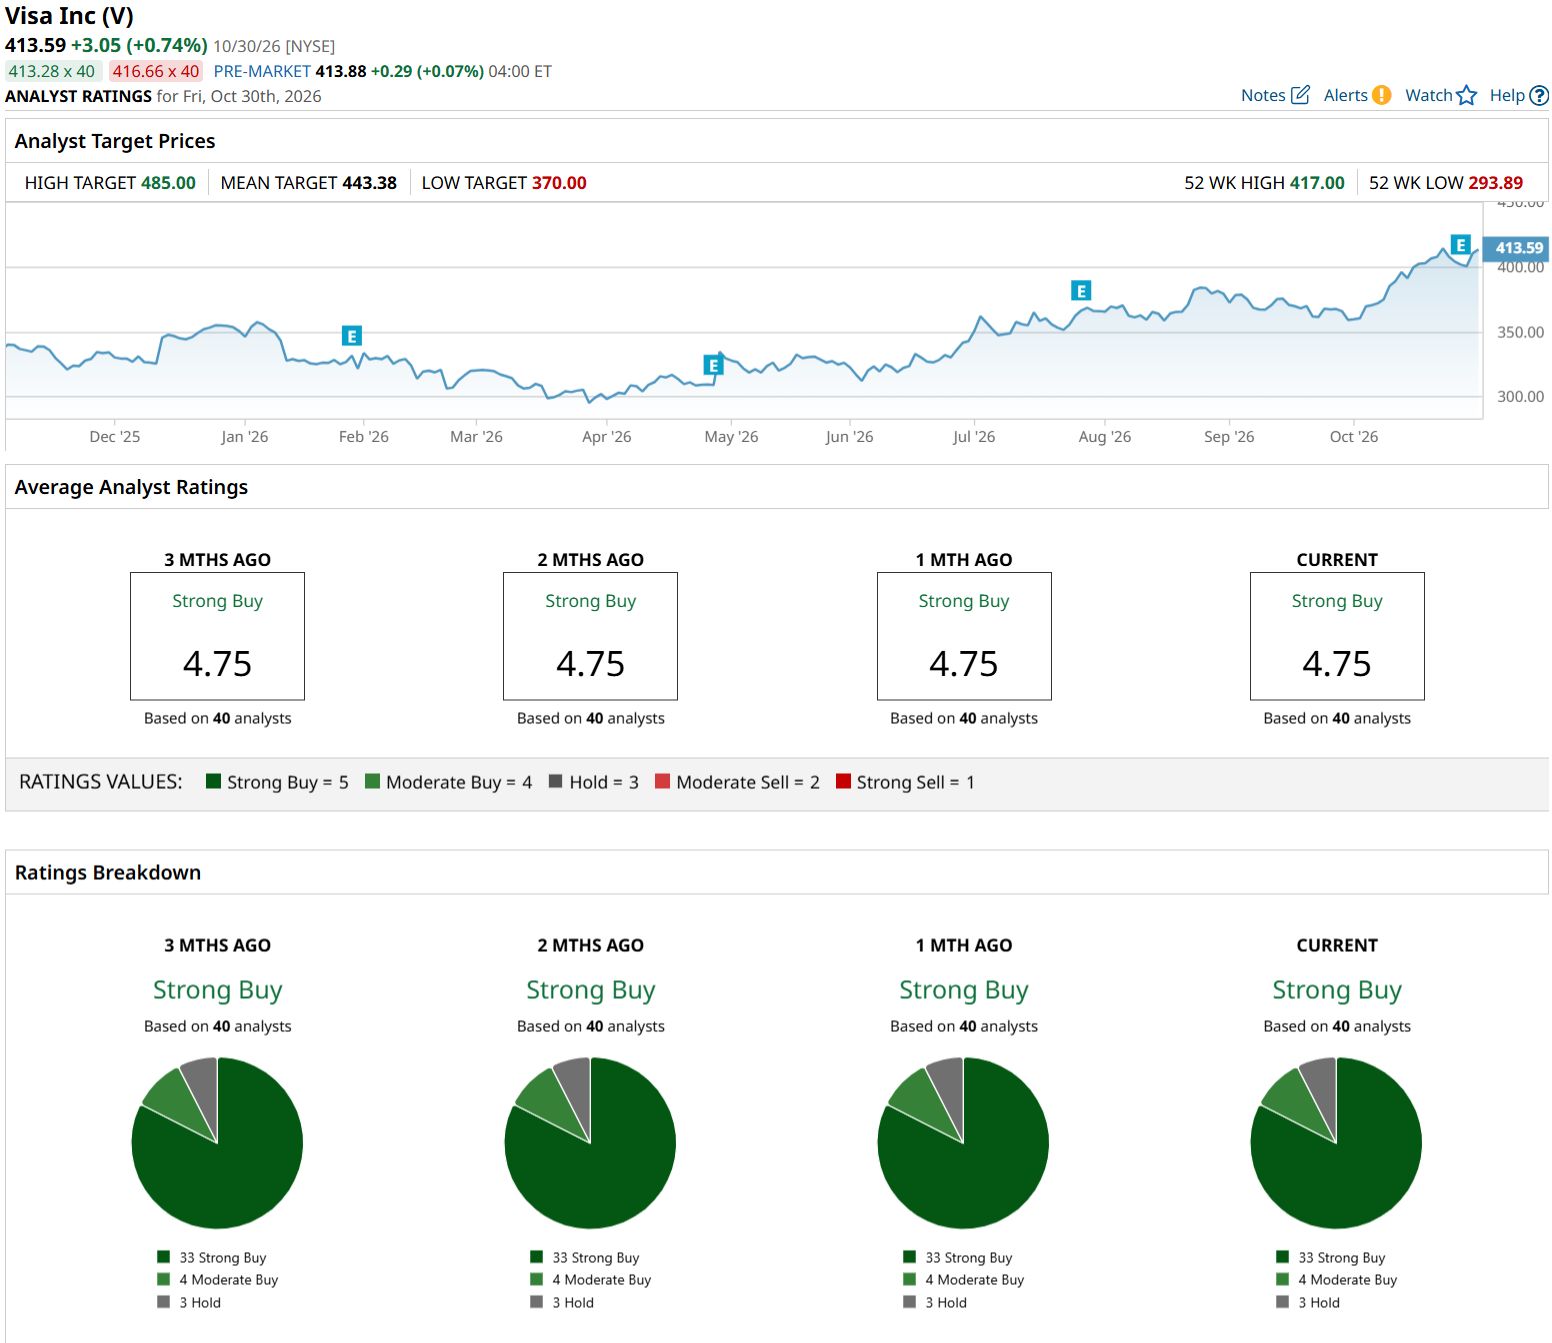
Based on 40 analysts with coverage, V stock has a consensus “Strong Buy” rating overall. Still, the average price target of $446.72 suggests modest potential upside of 6% from current levels.
 www.barchart.com
Conclusion
Visa’s 16.4% dividend increase strengthens its case as a long-term dividend-growth holding, supported by healthy earnings, broad payment activity, and emerging stablecoin and commercial-payment opportunities. Stablecoin-linked card volume has grown nearly 200% YOY. Still, the roughly 0.74% yield offers limited appeal for investors seeking immediate income, while the premium valuation and limited potential upside make today’s entry less compelling. Shares are more likely to grind higher than break out sharply, making Visa a sensible hold or gradual buy. Income-focused investors, however, may prefer to wait for a more attractive price.
On the date of publication, Ebube Jones did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Visa Just Hiked Its Dividend by More Than 16%, But Investors Should Consider Waiting for V to Pull Back Before Buying. AMD Stock Pops on $17B Q4 Revenue Guide. Traders Shouldn't Overlook a $3B Inventory Gamble and Collapsing Free Cash Flow. Dear Uber Stock Fans, Mark Your Calendars for November 4 Ahead of Qualcomm Earnings, Here's What Barchart Data Says Comes Next for QCOM Stock