

The Williams Companies, Inc. (WMB) is an energy infrastructure company headquartered in Tulsa, Oklahoma. With a market capitalization of $84.8 billion, it operates interstate natural gas pipelines and gathering and processing facilities across the United States, transporting approximately one-third of the nation’s natural gas used for heating, cooking, and electricity generation.
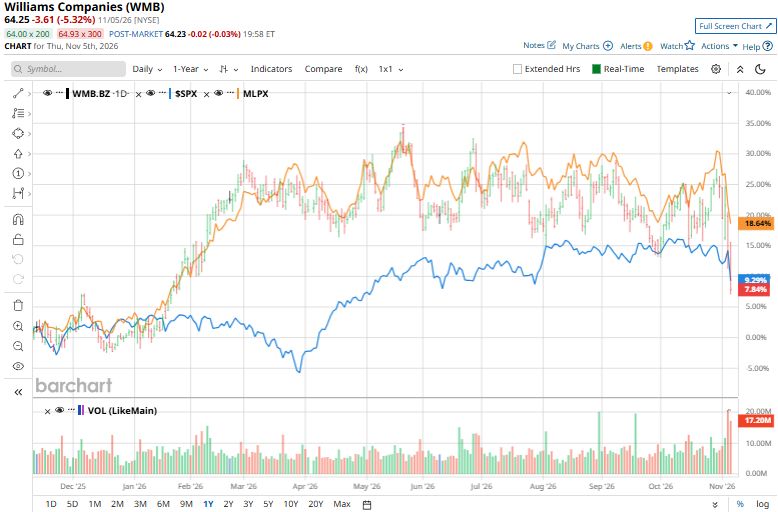
Shares of this natural gas infrastructure giant have outpaced the broader market over the past year. WMB has climbed 11.7% during this period, while the broader S&P 500 Index ($SPX) has gained nearly 8.2%. However, the stock has slightly underperformed the index year-to-date, with a 6.9% gain compared to the index’s 7.4% gain over the same period.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Narrowing the comparison, WMB has also lagged the Global X MLP & Energy Infrastructure ETF (MLPX), which has risen 19.2% over the past year and 15.2% year-to-date.
 www.barchart.com
On Nov. 2, Williams reported its Q3 2026 earnings. Shares fell 4.3% on the day of the announcement but rebounded 1.8% in the following trading session. The company delivered record adjusted EBITDA of $2.04 billion, up 6.2% year over year, driven by higher service revenues from new power generation projects, the Momentum Midstream acquisition, and increased storage revenues. Adjusted net income rose 10% to $663 million, while adjusted diluted EPS increased 10.2% to $0.54. Available funds from operations (AFFO) grew 9.7% to $1.59 billion, and cash flow from operations increased 5% to $1.51 billion.
Looking ahead, Williams reaffirmed its full-year 2026 adjusted EBITDA guidance of $8.3 billion to $8.5 billion and growth capital expenditure outlook of $7.3 billion to $7.9 billion. Management indicated that it expects to finish the year in the upper half of its EBITDA guidance range. The company also completed its acquisition of Momentum Midstream, announced a 9.4 Bcf expansion at Clay Basin storage, and advanced several Transco pipeline projects, including the Southeast Supply Enhancement II. Additionally, Williams reiterated its long-term target of achieving adjusted EBITDA compound annual growth of more than 11% through 2030.
For the current fiscal year, ending in December 2026, analysts expect WMB’s diluted EPS to increase 13.3% to $2.38. However, WMB has missed Wall Street’s consensus EPS estimates in three of the past four quarters, beating expectations only once.
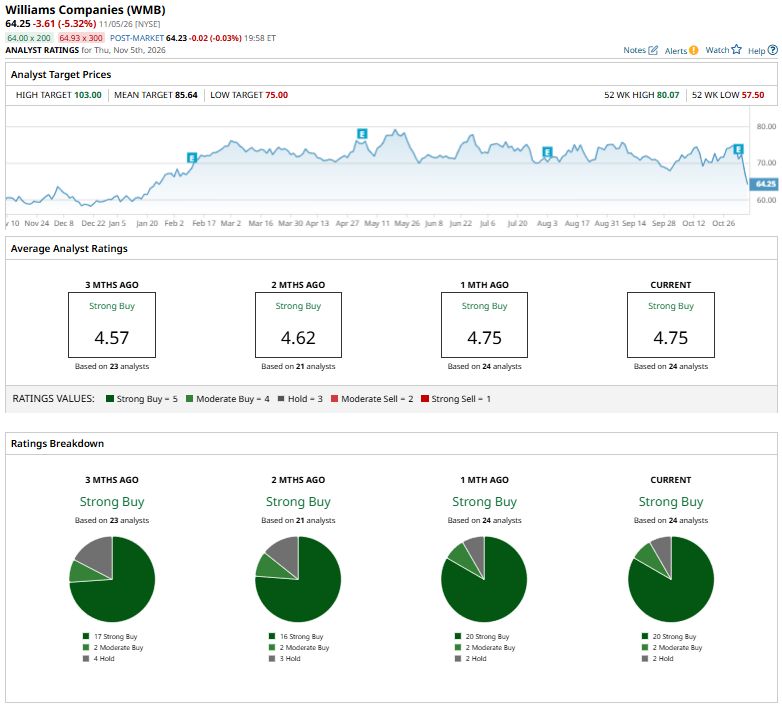
Among the 24 analysts covering WMB, the consensus rating is “Strong Buy,” based on 20 “Strong Buy,” two “Moderate Buy,” and two “Hold” ratings.
 www.barchart.com
The configuration is more bullish than it was two months ago, when the stock had 16 “Strong Buy” recommendations.
On Nov. 4, 2026, CIBC analyst Robert Catellier maintained a “Buy” rating on Williams Companies and kept his price target unchanged at $82.
The mean analyst price target of $85.64 implies a 33.3% premium to WMB's current share price, while the Street-high target of $103 suggests a potential premium of 60.3%.
On the date of publication, Abhishek Bhuyan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This Insurance Stock Just Raised Its Dividend by Over 11% This Could be a Major Problem for Alphabet Investors Uber Technologies Delivers Strong FCF - What's the Best UBER Play? Apple Flagged Supply Constraints and Rising Memory Costs Ahead of Its December Quarter. Here’s What to Know.