

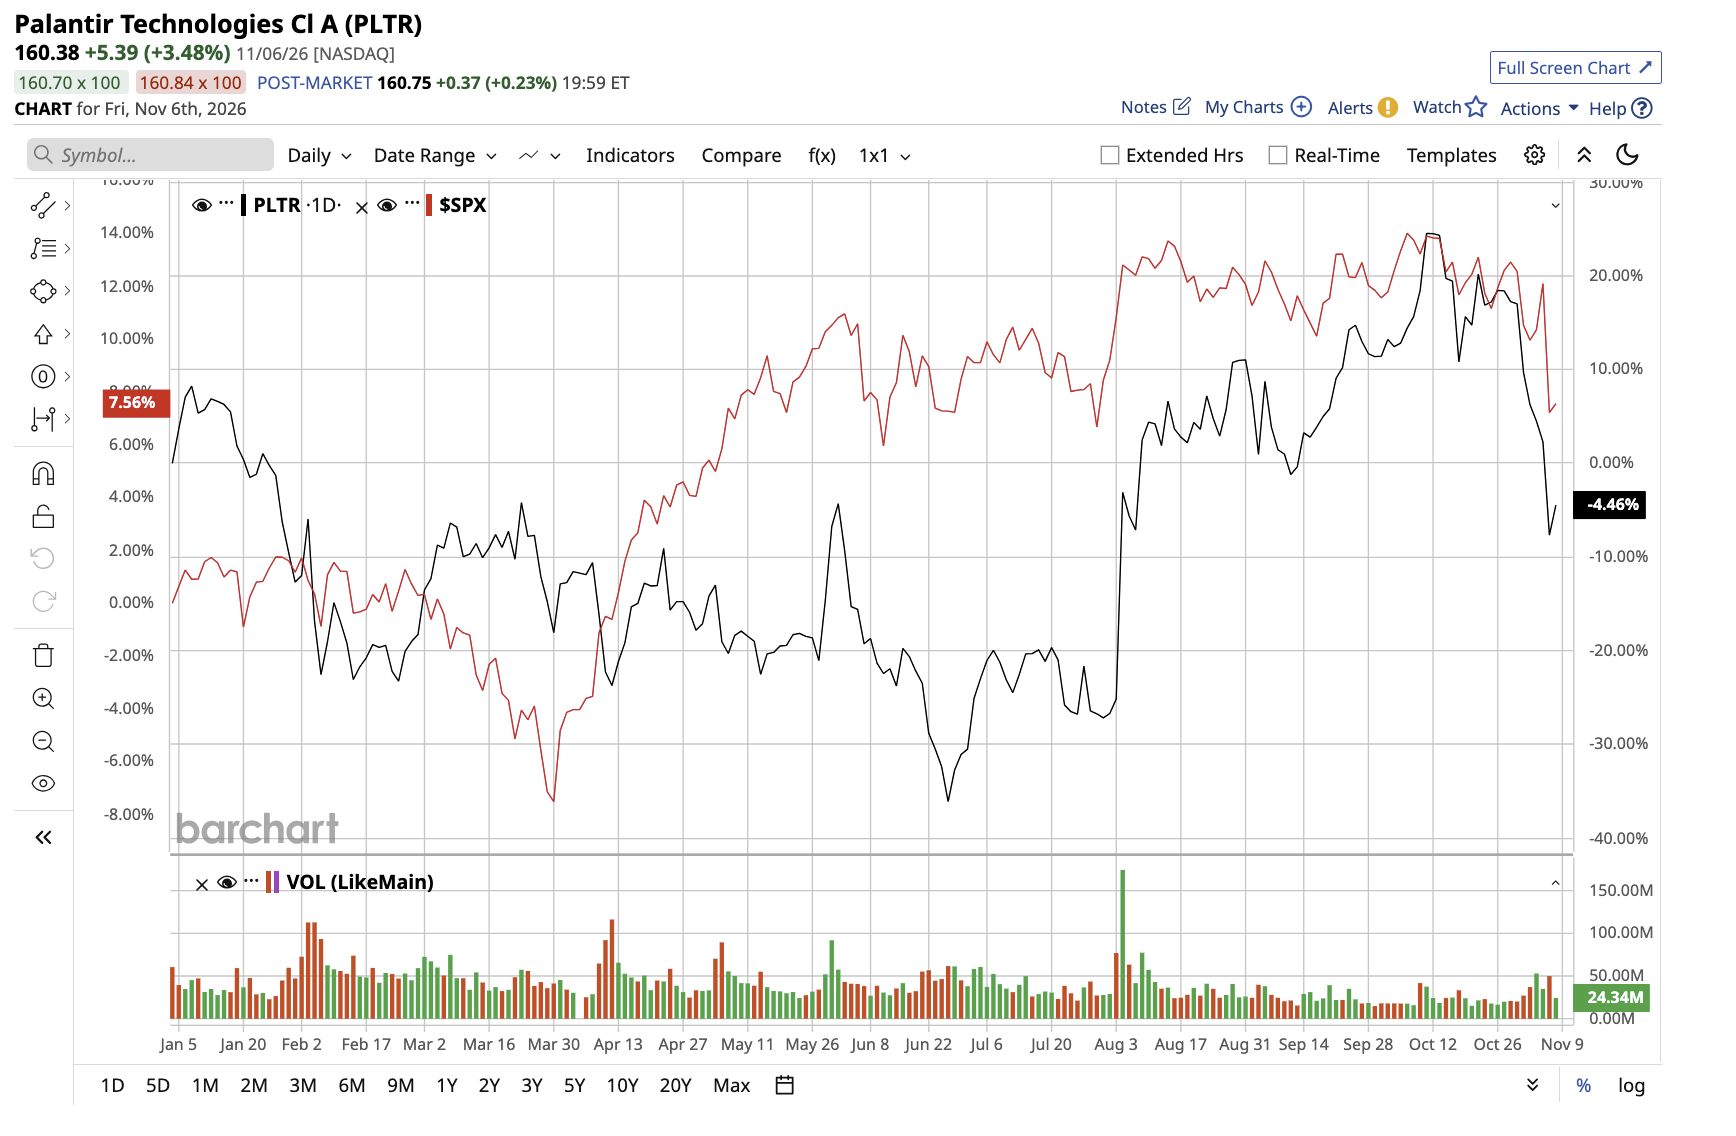
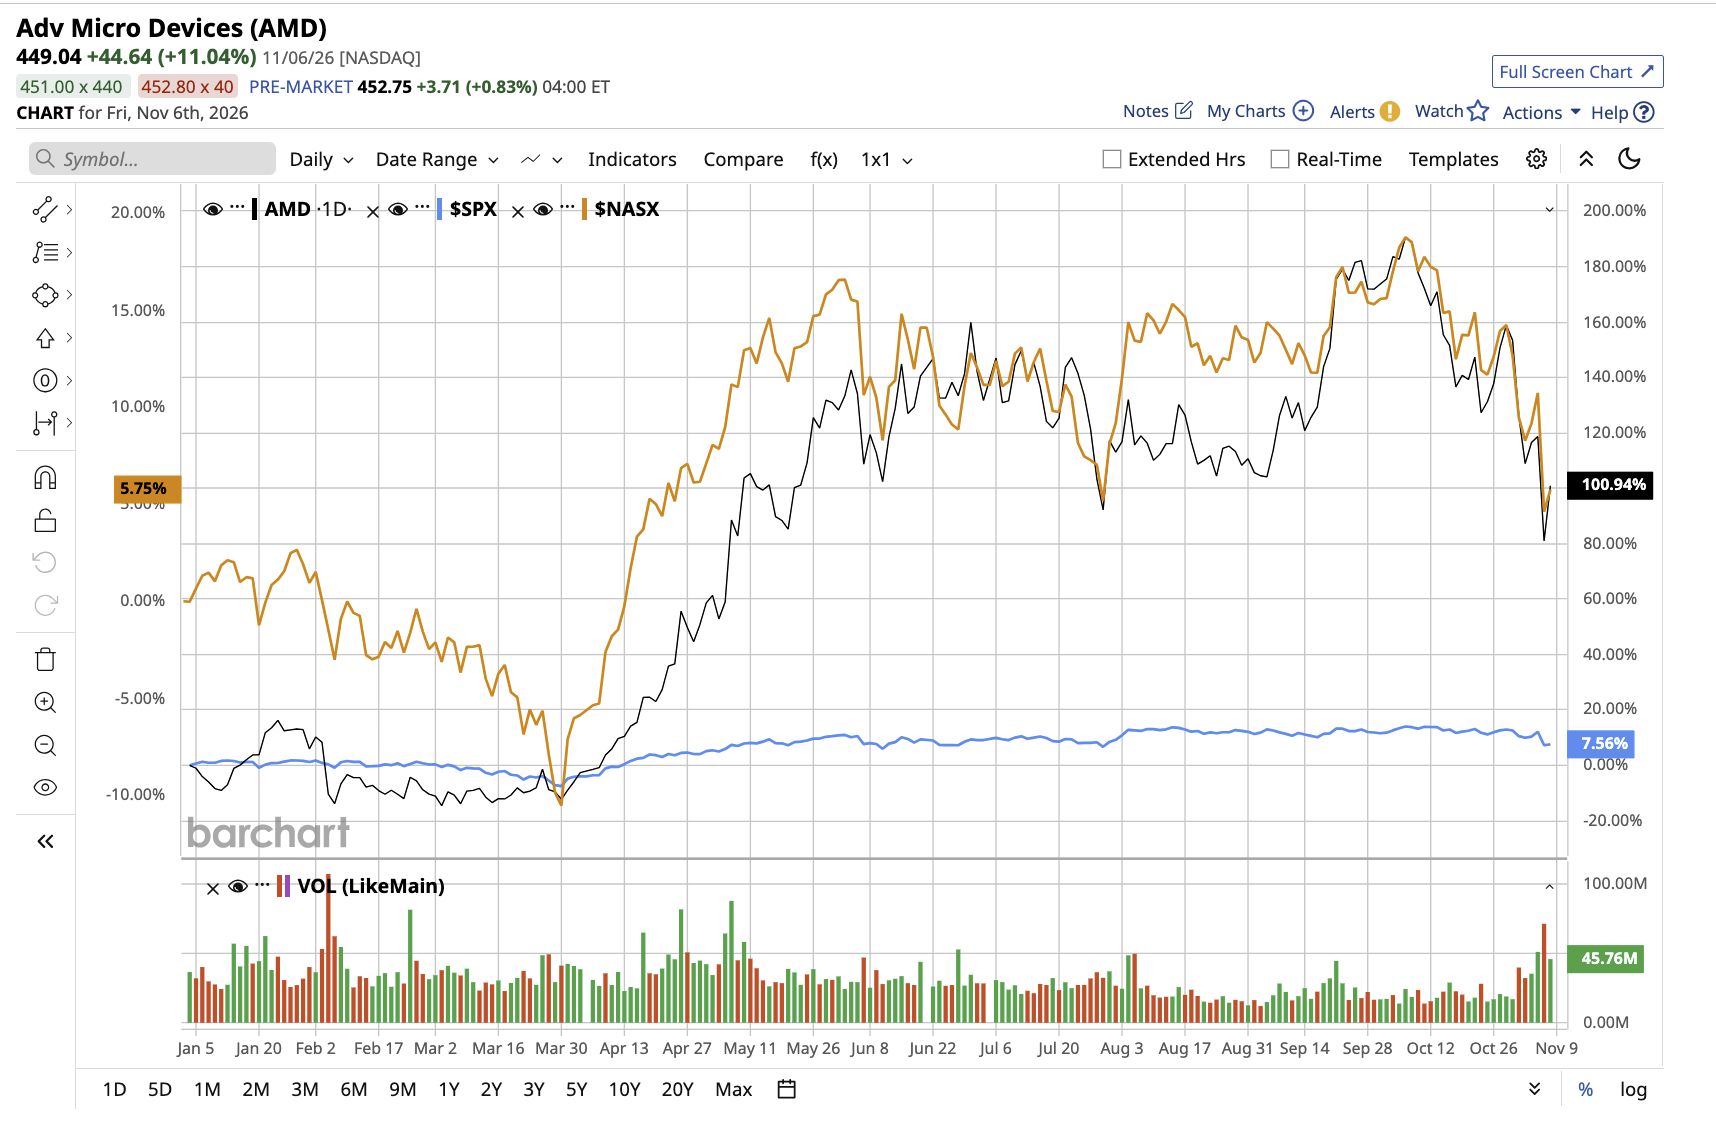
Artificial intelligence (AI) stocks have been struggling lately, even though some names are still performing outstandingly well. Palantir Technologies (PLTR) and Advanced Micro Devices (AMD) have climbed to the top with another stellar quarter, but both stocks were recently caught up in the broader AI selloff. PLTR stock and AMD stock both fell 20% over a number of recent sessions, although they are now staging comebacks.
Investors have been questioning whether the enormous investments in AI and data-center infrastructure will generate sufficient enough returns to justify the spending. Concerns about tighter AI regulations and a possible slowdown in data-center construction have added to the pressure.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
But the companies behind these two stocks are doing more than just getting by. They are thriving and raising the bar for growth. AMD is mounting an impressive comeback in the CPU market, taking market share from Intel (INTC) while expanding its presence in AI accelerators. Palantir, meanwhile, has shed its image as a government-only data analytics firm, with its U.S. commercial business outpacing U.S. government revenue for the first time in its most recent quarter.
Both of these companies are brimming with potential, but investors are paying increasingly high prices to own shares. At current valuations, one appears to have a considerably stronger case.
The Case for Palantir: Commercial AI Is Becoming a Powerful Growth Engine
Palantir creates software that helps governments and businesses make sense of large amounts of data and use that insight to make decisions. The Foundry platform serves commercial clients, while Gotham targets government and defense groups. The Artificial Intelligence Platform (AIP) also helps companies add AI models to their current operations. Instead of offering just another chatbot, Palantir wants to be the software that links AI to real business processes.
 www.barchart.com
In the third quarter of 2026, Palantir’s revenue skyrocketed 96% year-over-year (YOY) to $2.31 billion, with U.S. revenue jumping 119% YOY to $1.94 billion. Even more strikingly, commercial revenue shot up 113% YOY to $1.17 billion.
U.S. commercial revenue soared 148% to $984 million, outpacing the 96% rise in U.S. government revenue to $953 million and surpassing U.S. government revenue for the first time in the company’s history. Palantir's U.S. commercial customer base also jumped 29% YOY to reach 686 clients.
That doesn't mean the government segment is slowing down. Government revenue continued its healthy performance, jumping 81% to $1.15 billion. Meanwhile, the Maven defense platform now has more than 100,000 users.
Bookings signal even more growth ahead. Commercial total contract value (TCV) bookings soared to $1.65 billion, up 17%, while the total remaining deal value surged 55% to $13.4 billion.
As the business expands, Palantir's reliance on government contracts creates uncertainty, since shifting budget priorities could suddenly make it harder to win contracts. That makes the company's commercial progress all the more important.
Profitability was equally impressive, with adjusted operating income reaching $1.43 billion, with a 62% margin. Meanwhile, adjusted earnings came in at $0.44 per share. Adjusted free cash flow surged to $1.22 billion, boasting a 53% margin.
Management also raised its 2026 revenue forecast to a range of $8.53 billion to $8.534 billion, signaling remarkable 91% growth. The firm expects U.S. commercial revenue to soar by at least 143%. Analysts forecast a remarkable 116% surge in Palantir’s fiscal 2026 earnings to $1.36 per share.
Still, while Palantir's growth narrative is compelling, its lofty valuation leaves little room for error.
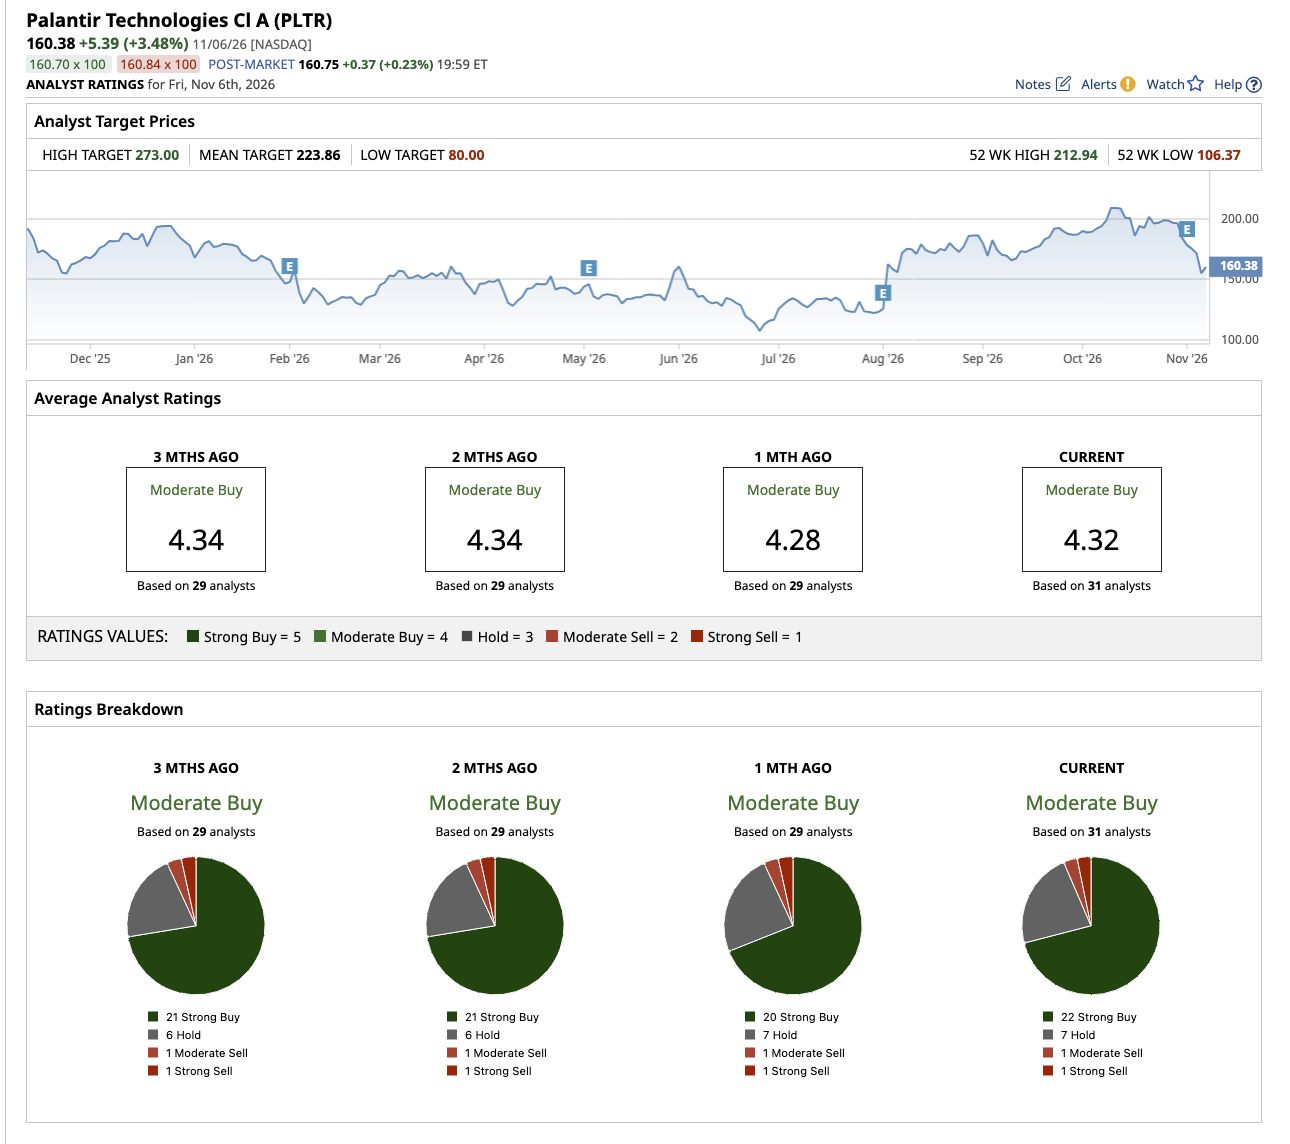
Overall, Wall Street has a consensus “Moderate Buy” rating for PLTR stock. Of the 31 analysts covering the stock, 22 recommend a “Strong Buy,” seven have a “Hold” rating, one has a “Moderate Sell,” and one analyst has a “Strong Sell” rating. The average price target of $223.86 points to potential upside of 32% from current levels, while the highest price estimate of $273 implies a possible gain of 61% from here.
 www.barchart.com
The Case for AMD: A CPU Comeback and a Much Bigger AI Opportunity
AMD makes cutting-edge CPUs and GPUs powering everything from personal computers to massive data centers. The company's Ryzen processors go head-to-head with Intel, while EPYC server chips are steadily carving out a larger slice of the market. With its Instinct accelerators and Helios systems, AMD is also emerging as a formidable rival to Nvidia (NVDA) in AI infrastructure.
 www.barchart.com
In the Q3 fiscal 2026, AMD's revenue reached $13.4 billion, up 45% YOY, while adjusted EPS rose 74% to $2.09. Data-center revenue nearly doubled to $8.5 billion, making up 64% of total sales. Cloud and enterprise server revenue also more than doubled. EPYC Turin processors are now used in more than 540 cloud instance types, and the next-generation Venice chips have commitments for more than 240 platforms, 20% higher than Turin. Management believes the server CPU market could grow to $220 billion by 2030 and expects server revenue to double by 2027.
AMD's AI momentum is accelerating. The company is now shipping MI455X accelerators at scale, and industry giants like Anthropic (ANT), Meta Platforms (META), Microsoft (MSFT), OpenAI, and Oracle (ORCL) have launched their first Helios systems. Meanwhile, AMD is bolstering its ROCm software ecosystem to unlock even greater GPU performance and make deployment easier than ever.
Performance across the company's other segments was a mixed bag in Q3. Client and Gaming revenue slipped 8% YOY to $3.7 billion, with gaming taking a sharper 40% dip to $773 million. In contrast, Embedded revenue jumped 29% YOY to $1.1 billion.
Adjusted gross margin climbed to 56%, while operating income soared 75% to $3.9 billion. Operating margin widened to 29% from 24%. AMD also delivered $1.2 billion in operating cash flow and $554 million in free cash flow.
Management anticipates Q4 revenue to reach around $17 billion, marking a striking 66% surge from last year. Even more impressive, projections for fiscal 2027 call for revenue to soar by more than 80%, backed by data centers expected to generate more than 80% of total sales. Server revenue is on track to double, which could spark even greater margin expansion. For fiscal 2026, analysts forecast a 102% surge in earnings to $6.59 per share.
While scaling production and taking on Nvidia remain major challenges, AMD’s explosive growth story is becoming impossible to overlook.
Which Stock Offers the Better Value Now?
Both companies boast impressive growth stories, yet AMD stands out with a valuation that feels far more grounded. AMD stock trades at 35 times its projected 2027 earnings, which are set to soar 120% to $14.52. In comparison, Palantir stock trades at a lofty 85.4 times estimated fiscal 2027 EPS of $1.98.
Prominent investors like Ray Dalio and Michael Burry have voiced concerns about the AI boom, and Palantir's expensive valuation adds to the bearish debate. Although AMD is hardly a steal, its surging data-center business, growing CPU market share, and rapid earnings growth make a much stronger case for its premium.
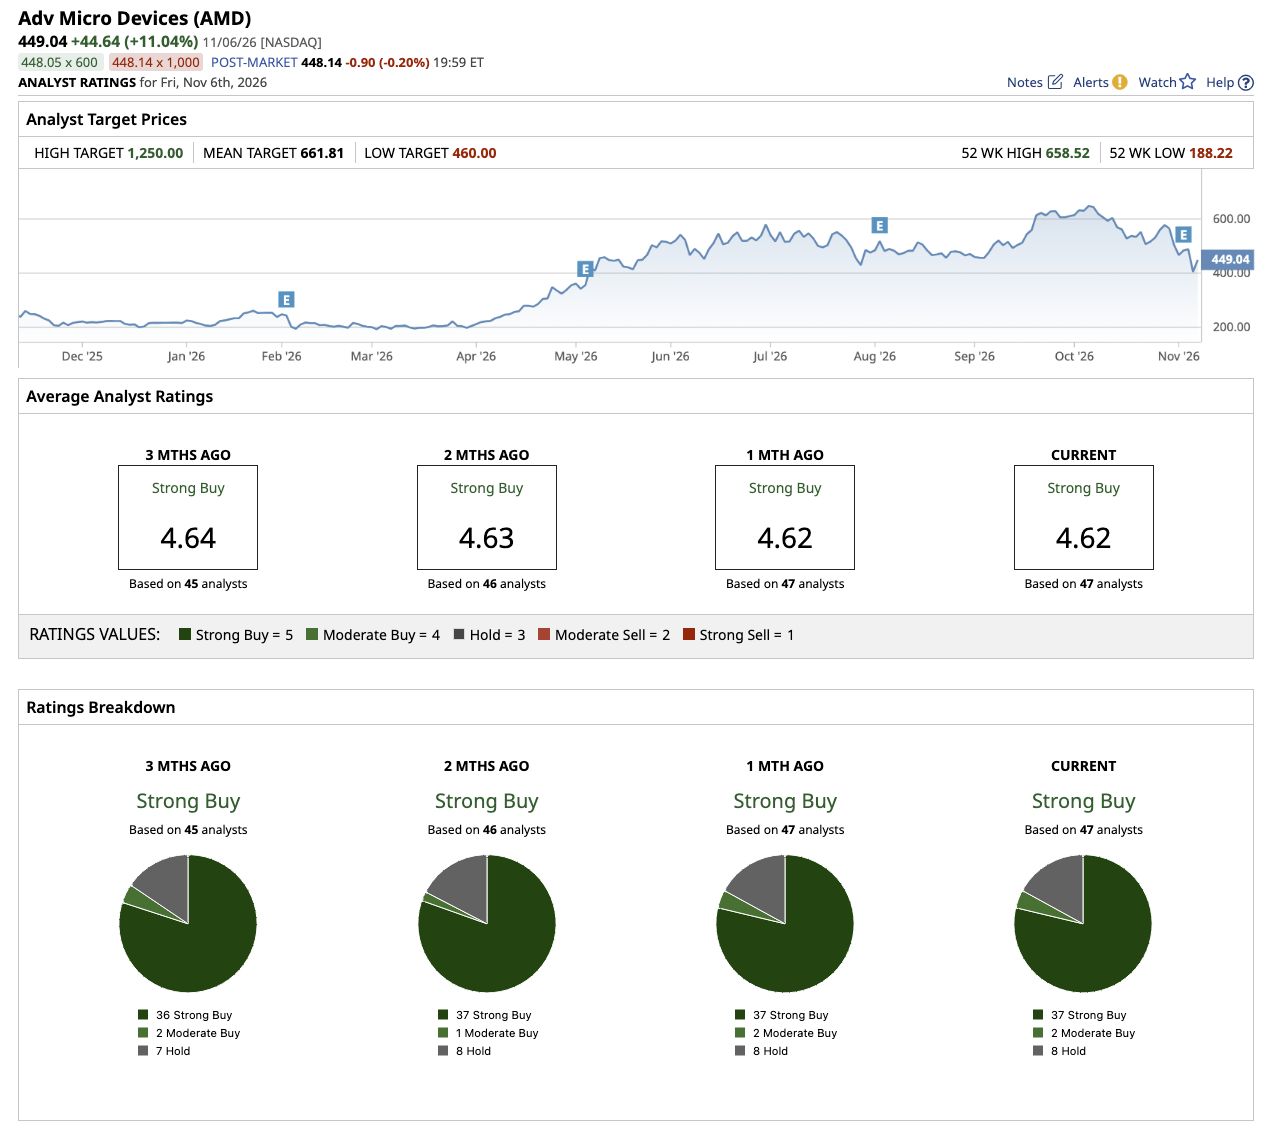
Wall Street currently rates AMD stock as a consensus “Strong Buy.” Of the 47 analysts with coverage, 37 have a “Strong Buy” rating, two recommend a “Moderate Buy,” and eight suggest a “Hold” rating. The average price target of $661.81 implies potential upside of 30% from here, while the Street-high target of $1,250 suggests a possible 146% gain from current levels.
 www.barchart.com
On the date of publication, Sushree Mohanty did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Want to Get Paid $1,000 a Year for 10 Years? Just Live Right Next to a Data Center. Cybertruck Production Is Set to End as Elon Musk Finally Closes the Coffin on a Multi-Year Executional Nightmare Down 44% From All-Time Highs, Here’s Why You Should Consider Buying the Micron Stock Dip Palantir vs. AMD: Both Stocks Have Pulled Back More Than 20%, But 1 Is a Better Value Buy Here