

Meta Platforms (META) has spent the past two years convincing Wall Street that its massive artificial intelligence (AI) bet will eventually pay off. But the market isn't fully on board. META stock has been trading under pressure this year, swinging on every headline about capital expenditures, compute costs, and agent adoption.
Last week, however, Meta made a move with quiet importance. On Nov. 9, the company released Muse Ember, its smallest and cheapest AI model yet. Ember is not a flashy frontier model designed to win benchmarks, but a workhorse built for the unglamorous, repetitive tasks that AI agents do all day. Plus, it is priced to move.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
That makes the case for META stock more interesting, because Meta is doing more than just developing AI. It's putting the plumbing in place for an agent economy, eroding the competition on pricing, and printing money as it operates its primary advertising machine.
Meta Platforms Stock and the Cost of AI
Meta already invests heavily in AI to enhance the efficiency of its platforms and to support new experiences, including content ranking, ad targeting, and the development of generative AI products. Artificial intelligence innovation has become integral to Meta's product development and operational infrastructure. The company maintains partnerships and collaborations with major tech firms such as Microsoft (MSFT), Nvidia (NVDA), Advanced Micro Devices (AMD), Broadcom (AVGO), and OpenAI.
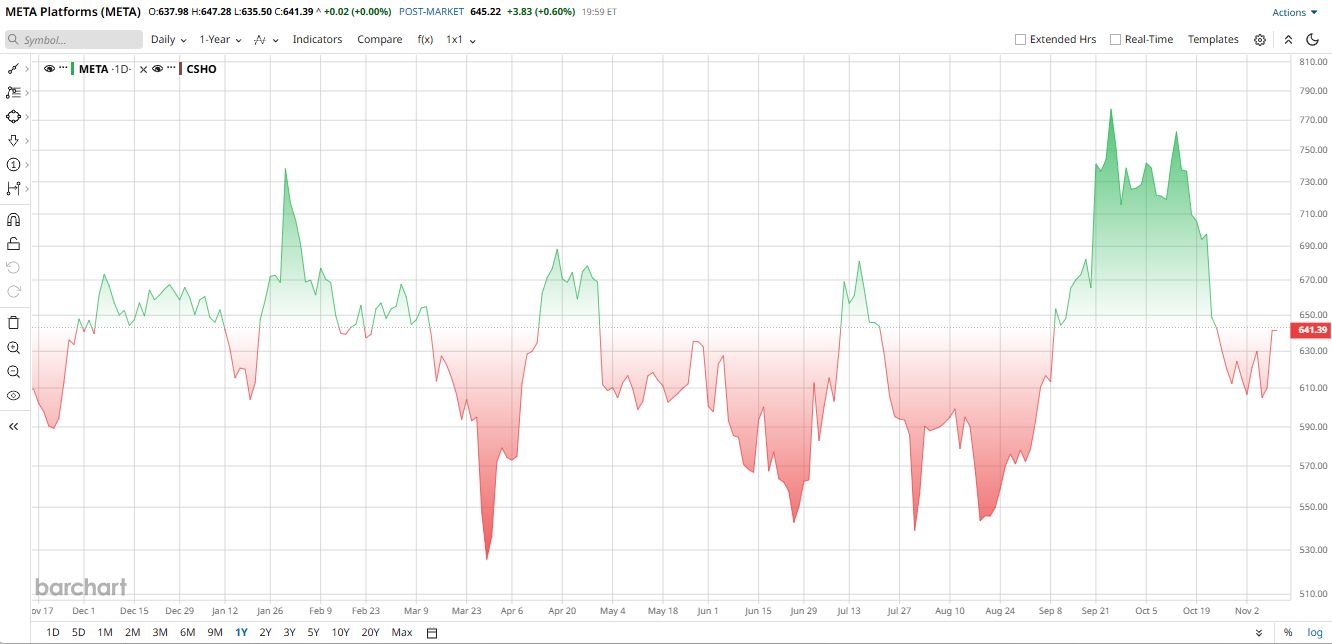
META stock's performance has not been very impressive in 2026. The stock is down roughly 3% year-to-date (YTD), trailing behind other "Magnificent Seven" members as well as far below its own five-year average. The decline has come amid growing concerns that AI infrastructure spending may take longer to pay off, while higher operating costs and legal expenses have added pressure.
Despite underperforming, shares of Meta are not a bargain. The price-to-sales (P/S) ratio is 7.9 times, above the sector median and a significant premium. Similarly, the price-to-book (P/B) ratio is 5.8 times. Meanwhile, the stock's dividend yield stands at just 0.34%. That signals limited income potential for dividend-focused investors.
 www.barchart.com
Muse Ember Could Make Agents Cheaper to Run
Meta’s new Muse Ember model costs $0.10 per million input tokens and $0.50 per million output tokens for prompts of up to 200,000 input tokens. The model handles text, image, audio, and video within a 1 million token context window.
The important comparison is about task cost. Artificial Analysis data estimates $0.14 per task for Ember versus $0.41 for Claude Haiku 5.5 at maximum reasoning, with both scoring around 36 on the Artificial Analysis Intelligence Index. That is Meta’s benchmark, not a guarantee of customer savings. But lower execution costs could make large-scale agent deployment economical and draw developers to Meta’s API.
Meta is also building around the model. The company recently acquired Conductor, a startup that coordinates coding agents across parallel workspaces. “Conductor is joining Meta,” confirmed co-founder Charlie Holtz. Alongside Muse Code and larger Muse models, the deal gives Meta more of the developer workflow.
Meta Reports Q3 Earnings
Meta Platforms posted another solid quarterly performance on Oct. 21, buoyed by its advertising business, although hefty costs from AI infrastructure growth weighed on profitability. Revenue rose 26% year-over-year (YOY) to $64.6 billion in the third quarter.
The main driver of growth continued to be advertising. Ad revenue rose by 26% YOY, as average price per ad grew 14% and ad impressions grew 10%, suggesting that Meta brought in more ad revenue through both volume and better pricing.
Total expenses climbed 68% YOY to $51.6 billion. That figure included a $9.89 billion charge stemming “an agreement with 52 attorneys general to resolve litigation related to teen mental health and social media.” Net income was $9.86 billion, while diluted EPS was $3.83 per share.
In addition, Meta's investments in its infrastructure dampened cash generation. Capital expenditures rose to $34.91 billion while free cash flow fell to -$2.12 billion. At the end of the quarter, cash and marketable securities totaled $82.4 billion.
Looking forward, Meta forecast revenue of $73 billion to $76 billion for Q4. Meanwhile, capital expenditures for 2026 are expected to range from $135 billion to $145 billion.
What Does Wall Street Think of Meta Platforms Stock?
Wall Street isn't giving up on Meta Platforms. Morgan Stanley raised its price target on META stock to $820 with an “Overweight” rating, fueled by positive ad revenue growth and greater adoption of the company's AI technology.
Yorkville Ives analyst Dan Ives feels that a dip in U.S. data-center building due to the midterm elections could be positive for Meta. As new facilities come online slowly, the value of data-center capacity and available computing power may increase. That could provide advantages to bigger hyperscalers like Meta. Ives has an “Outperform” rating and a $920 price target for META stock.
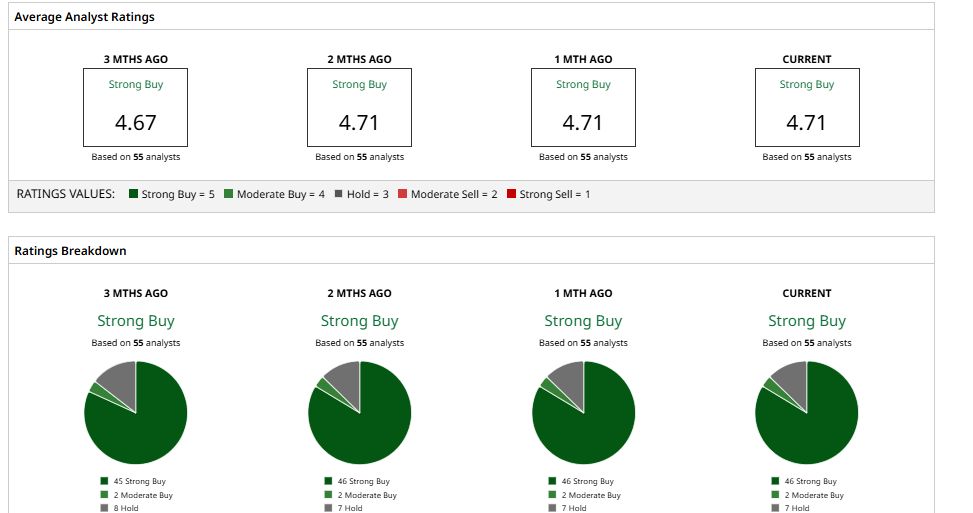
Overall, Meta Platforms has a consensus “Strong Buy” rating on Wall Street. The average price target of $858.65 points to potential upside of approximately 34% from current levels, while the Street-high target of $1,050 suggests a possible 64% climb from here.
 www.barchart.com
On the date of publication, Nauman Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
QumulusAI Just Scored a Major Deal to Expand AI Capacity. How to Play QMLS Stock Here. Meta Stock Has Fallen 3% YTD. Its Cheapest AI Model Could Change Everything. Cisco Systems Had a Stellar Quarter, But CSCO Tumbled - Is It Too Cheap Here? Down 62% From All-Time Highs, Here’s How to Play CRWV Stock as CoreWeave Smashes Q3 Estimates