

Diamondback Energy, Inc. (FANG), headquartered in Midland, Texas, operates as an independent oil and natural gas company. With a market cap of $49.5 billion, the company acquires, develops, explores, and exploits unconventional, onshore oil and natural gas reserves in the Permian Basin in West Texas.
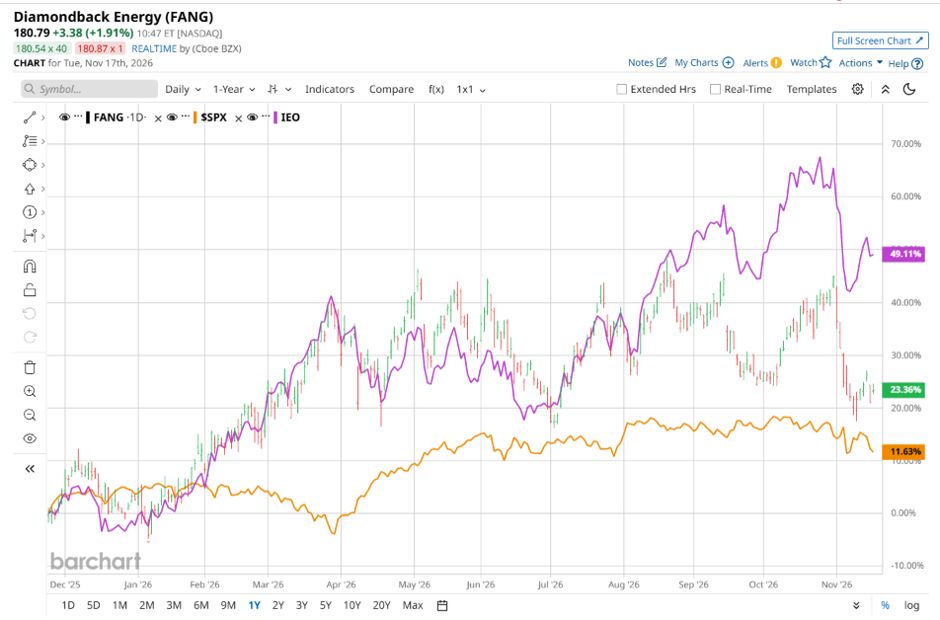
Shares of this leading independent oil and gas company have outperformed the broader market over the past year. FANG has gained 23.8% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.1%. In 2026, FANG stock is up 20.6%, surpassing the SPX’s 8.3% rise on a YTD basis.
Don’t Miss a Day: From crude oil to coffee, sign up free for Barchart’s best-in-class commodity analysis.
Narrowing the focus, FANG’s underperformance is apparent compared to the iShares U.S. Oil & Gas Exploration & Production ETF (IEO). The exchange-traded fund has gained about 47.7% over the past year. Moreover, the ETF’s 53.6% returns on a YTD basis outshine the stock’s gains over the same time frame.
 www.barchart.com
FANG’s mixed performance reflects investor caution around growth and cost pressures, even as strong Permian execution, technological gains, and operational efficiency drove solid results. CEO Kaes Van't Hof emphasized a disciplined over 32% reinvestment rate to maximize free cash flow, supported by faster well times, AI automation, and a strategic shift toward full-field development in the Barnett. Looking to the 2030s, management remains focused on capital allocation discipline, balancing debt reduction, buybacks, and dividend growth, while navigating ongoing service inflation through robust operational excellence.
On Nov. 2, FANG shares tumbled 5.8% after reporting its Q3 results. Its adjusted EPS of $5.86 beat Wall Street expectations of $4.92. The company’s revenue was $5.4 billion, beating Wall Street forecasts of $4.3 billion.
For the current fiscal year, ending in December, analysts expect FANG’s EPS to grow 67.5% to $22.40 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
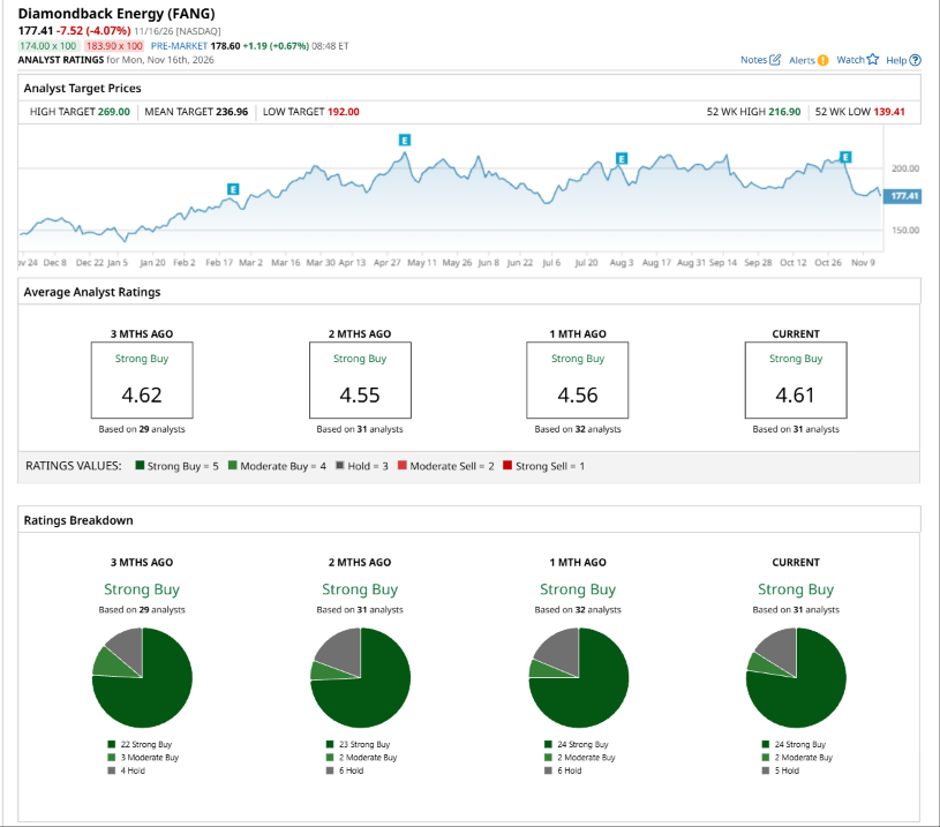
Among the 31 analysts covering FANG stock, the consensus is a “Strong Buy.” That’s based on 24 “Strong Buy” ratings, two “Moderate Buys,” and five “Holds.”
 www.barchart.com
This configuration is more bullish than two months ago, with 23 analysts suggesting a “Strong Buy.”
On Nov. 12, Scott Hanold from RBC Capital maintained a “Buy” rating on FANG with a price target of $240, implying a potential upside of 35.3% from current levels.
The mean price target of $236.96 represents a 33.6% premium to FANG’s current price levels. The Street-high price target of $269 suggests a notable upside potential of 51.6%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Sugar Prices Face Seasonal Headwinds: Will Energy Markets Add More Selling Pressure? Could Last Friday's Events Have Ripple Effects for This Week's Markets? Why Did Friday's Commodity Complex Bring to Mind Candy and Nuts? 1 Million Reasons to Buy the Dip in Tesla Stock (You Can Thank Terafab)