

The most valuable spot in online shopping may soon belong to whoever can help customers decide what to buy. Amazon (AMZN) — which operates an online marketplace alongside cloud computing, advertising, streaming, and subscription businesses — is already seeing that shift. The company's third-quarter results showed that more than 400 million customers used Alexa for Shopping over the preceding 12 months, while customer interactions surged 570% from a year earlier.
That growing appetite for artificial intelligence (AI) assistance gives Amazon plenty to defend. The company generated $201.9 billion in Q3 revenue, up 12% year-over-year (YOY), showing the scale of the business behind its shopping ambitions.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Amazon’s proposed shopping data repository brings another intriguing possibility into focus. The real test is whether knowing what shoppers want can become as valuable as selling it to them in the first place. Let’s take a closer look.
Inside Amazon’s Shopping Data Strategy
Amazon’s reported World Product Graph would give shoppers fewer reasons to leave its platform while deciding what to buy. The proposed data repository would collect information on products worldwide, including items Amazon does not sell. The proposal combines feeds from brands and retailers with website crawling to help shoppers compare models, understand product differences, and decide what suits them without leaving Amazon.
That matters as competing AI agents take on more shopping decisions. If another assistant provides better answers, customers could follow its recommendations elsewhere. Bringing more product information together could help Amazon improve its own shopping assistant and remain involved from research through purchase, protecting opportunities to earn sales and advertising revenue.
The proposal still comes with uncertainty. Amazon says the brainstorming document does not necessarily reflect current plans, and the project could change or be abandoned.
The move deserves a cautiously positive view as a defense of Amazon’s relationship with shoppers. Keeping more research and purchasing within its ecosystem could benefit the business, but the investment case depends on execution. Until Amazon confirms a rollout and demonstrates measurable benefits, the proposal gives shareholders a reason to watch its progress rather than raise earnings expectations.
What Amazon’s Numbers Tell Investors
Amazon’s Q3 results, released on Oct. 29, showed revenue increasing 12% YOY to $201.9 billion, broadly matching the $202.3 billion consensus estimate. Meanwhile, GAAP earnings of $1.89 per share missed the $1.96 forecast, as Amazon Web Services (AWS) revenue exceeded expectations while advertising fell short.
The quarter continued a longer expansion, with trailing annual revenue reaching $797.5 billion compared with $458 billion five years earlier, representing 11.7% annualized growth. Amazon's Q4 revenue guidance of about $243.5 billion at the midpoint implies 14% YOY growth and broadly matches expectations.
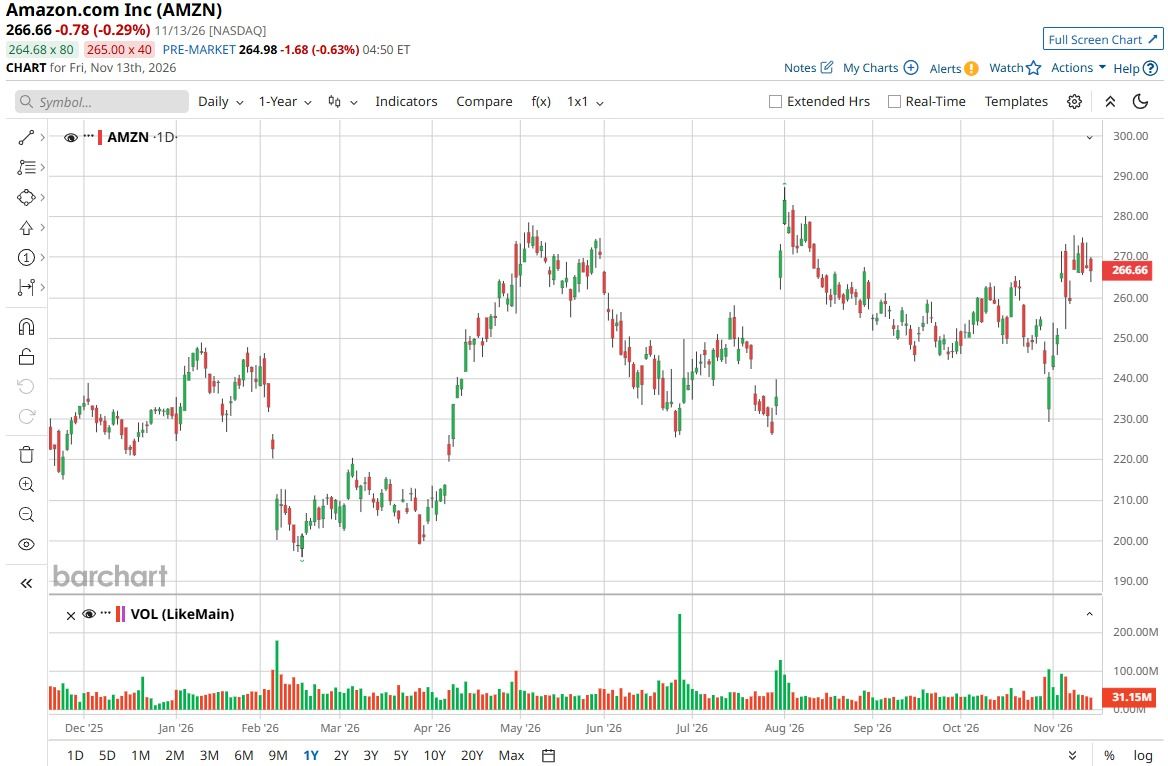
Amazon stock’s performance reflects expectations for continued expansion. AMZN stock is up 12% so far this year and 11% over the past 52 weeks, giving Amazon a market capitalization of approximately $2.78 trillion.
 www.barchart.com
Amazon’s cloud business remains central to supporting that valuation. AWS revenue grew more than 39% YOY, reaching a $184 billion annualized run rate (ARR), while management projected growth above 40% in 2027 and 2028. Amazon sees AWS potentially reaching $1 trillion in annual revenue within five to 10 years, with inference already contributing more than half of AWS AI revenue.
Amazon is also expanding its consumer reach. The company's Nov. 5 partnership with Uber's (UBER) Uber Eats offers Prime members $0 delivery on eligible orders of $25 or more across some 10,000 cities and towns in the United States. Meanwhile, the Ring business recently introduced two autonomous security products, extending Amazon’s robotics ambitions.
What Does Wall Street Expect for Amazon Stock?
Amazon’s next earnings release is expected on Feb. 4, 2027, with analysts forecasting earnings of $2.47 per share for the December quarter. That would represent a 27% increase from $1.95 a year earlier.
Morgan Stanley’s longer-term outlook is more ambitious. The bank named Amazon its “Top Pick” and maintained an “Overweight” rating on AMZN stock, citing opportunities across Prime, e-commerce, cloud computing, and advertising. Analyst Brian Nowak sees AI as a potentially overlooked growth driver that could help AWS reach $1 trillion in annual revenue. Nowak’s assumptions also show what reaching that outcome would require; factoring in higher Nvidia (NVDA) GPU shipments, he forecast AWS revenue growth of 47% in 2027 and 42% in 2028.
Scotiabank's latest assessment offers a more measured view. After earnings, the firm lowered its price target to $300 from $325 but retained an “Outperform” rating, citing delayed free cash flow conversion. This reduced target signals more restrained valuation expectations without abandoning the bullish case.
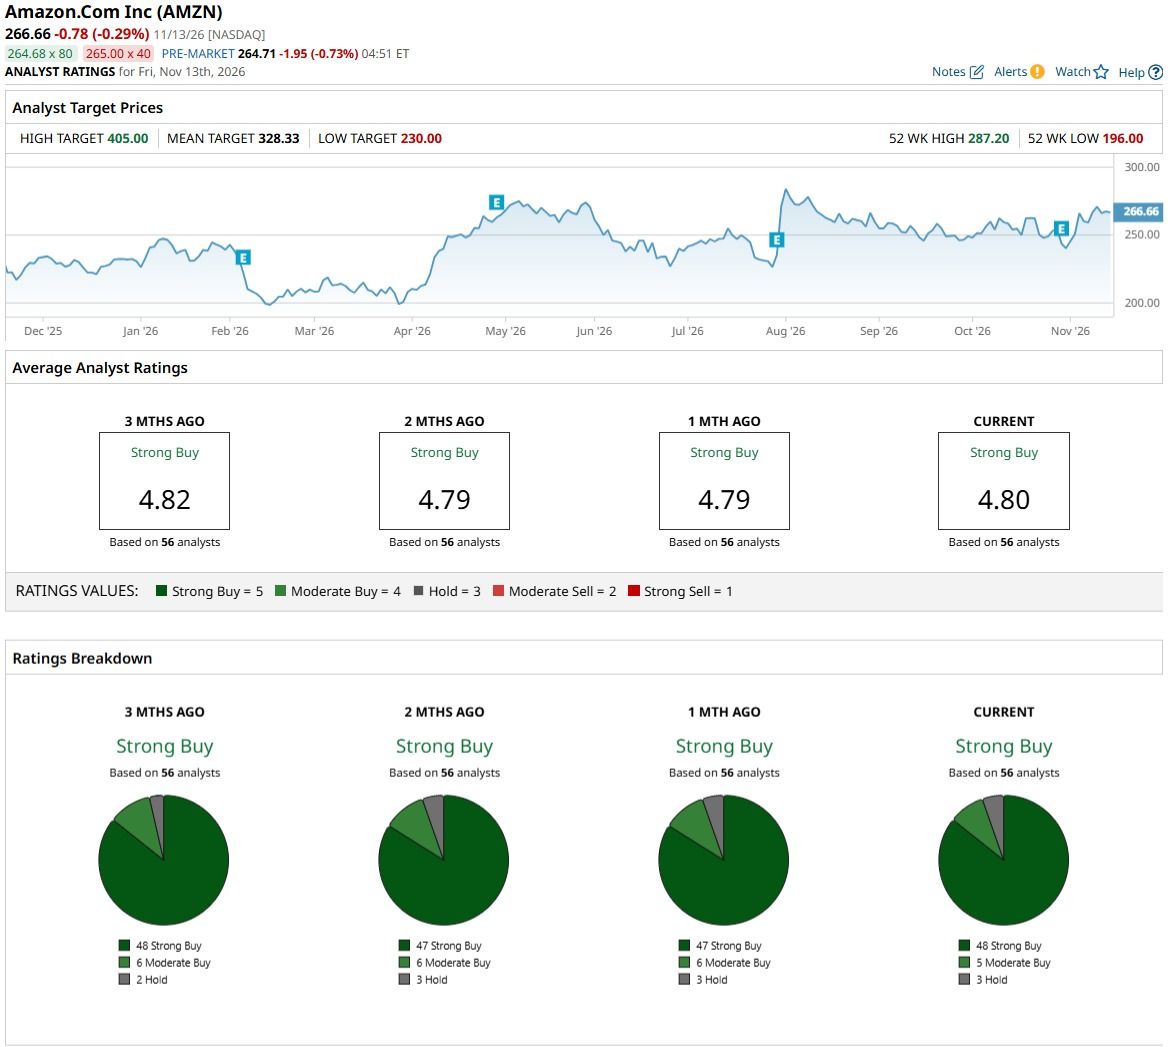
That positive stance extends across Wall Street. AMZN stock has a consensus “Strong Buy” rating from 56 analysts with coverage. The average price target of $328.42 suggests potential upside of 27% from current levels.
 www.barchart.com
Conclusion
Amazon has good reason to make this move. Keeping shoppers on its platform matters when AI assistants could start making their buying decisions elsewhere. The likely payoff is gradual, with better recommendations helping Amazon hold on to customers rather than suddenly lifting profits. Shareholders should welcome the idea without paying extra for a business that has yet to materialize. It strengthens the case for watching Amazon stock, but the numbers still need to show that shoppers are buying more often.
On the date of publication, Ebube Jones did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Amazon Is Building a Massive Shopping Data Repository to Compete With AI Agents. Shareholders Should Welcome the Move. Applied Materials Reports Another Double Beat in Q4. AMAT Stock Could Gain 66% From Here. A $3 Billion Reason Why Disney Stock Is in Focus Today A $5 Billion Reason Why Nike Stock Is in Focus Today