

Tutor Perini Corporation TPC is entering a more profitable phase as its nine mega projects, with a combined value of roughly $16 billion, move further into construction. These projects represent a substantial portion of the company’s near-record $19.9 billion backlog at the end of the second quarter of 2026 and should provide meaningful revenue and earnings visibility over the next several years.
The margin impact is already becoming visible. Management noted that the newer mega projects carry higher margins than much of Tutor Perini’s older work. As execution ramps, the company expects these projects to increasingly influence its profitability. In the second quarter of 2026, the Civil segment delivered a 15.3% operating margin, above management’s expected 12%-15% range. Building margin reached 5.6%, near the upper end of its 3%-6% target range.
Specialty Contractors provides another potential source of margin upside. Its operating margin improved to 2.2% from 0.3% sequentially and negative 10.2% a year earlier. The turnaround is being driven by increased electrical and mechanical activity in New York and Texas, with many projects still in the early stages of execution. As volumes build, Tutor Perini is targeting sustainable Specialty margins of 5%-8%, leaving considerable room for further improvement.
The broader opportunity pipeline strengthens that outlook. Tutor Perini has identified more than $200 billion of potential projects over the next three to four years, roughly three times the level seen a few years ago. This larger pool allows the company to remain selective and prioritize projects with favorable contract terms, adequate contingencies and higher expected margins rather than simply chasing backlog growth.
Overall, the ramp-up of Tutor Perini’s $16 billion mega-project portfolio should support healthy margins and could create further upside as execution advances. However, management continues to frame Civil margins around 12%-15% and Building margins at 3%-6%, suggesting that continued improvement is more likely to be gradual than a straight-line expansion.
Mega-Project Execution Raises the Bar for Infrastructure Margins
Tutor Perini’s roughly $16 billion portfolio of nine mega projects places it alongside contractors pursuing large, complex infrastructure work where project mix and execution can materially influence margins. MasTec, Inc. MTZ and Fluor Corporation FLR are also benefiting from stronger backlogs and mission-critical demand.
MasTec is seeing a similar shift toward larger, more complex infrastructure opportunities. In the second quarter of 2026, backlog reached a record $21.4 billion, up nearly $5 billion year over year, while adjusted EBITDA margins improved 100 basis points. MTZ is pursuing more large opportunities across power delivery, clean energy, pipelines and mission-critical infrastructure, along with the Superior acquisition, which are supporting higher-value growth.
Fluor is likewise strengthening its backlog with projects carrying improving margin profiles. FLR’s second-quarter new awards exceeded $6 billion, lifting backlog to nearly $27 billion, with opportunities spanning mining, nuclear, power, LNG and data centers. Management said margins on new awards are improving versus existing backlog, supported by selective commercial negotiations, disciplined risk pricing and adequate contingencies.
TPC Stock’s Price Performance & Valuation Trend
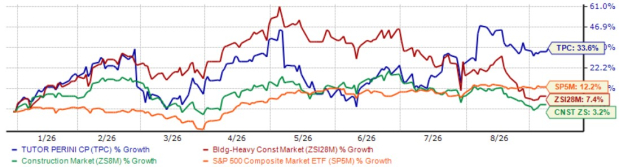
Shares of this California-based civil and building construction company have gained 33.6% year to date (YTD), outperforming the Zacks Building Products - Heavy Construction industry, the broader Construction sector and the S&P 500 Index.
TPC YTD Share Price Performance
Image Source: Zacks Investment Research
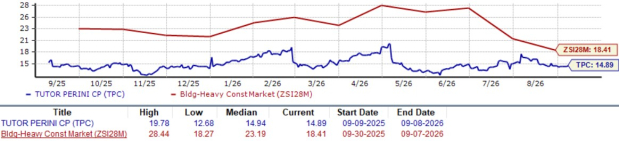
TPC stock is currently trading at a discount compared with the industry peers, with a forward 12-month price-to-earnings (P/E) ratio of 14.89, as evidenced by the chart below.
TPC Valuation
Image Source: Zacks Investment Research
Earnings Estimate Revision of TPC Stock
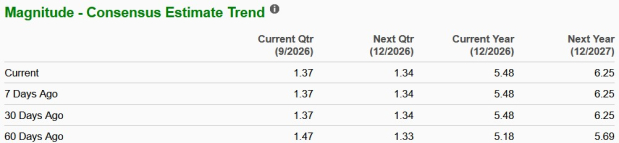
TPC’s earnings estimates for 2026 and 2027 have moved upward over the past 60 days to $5.48 per share and $6.25, respectively. The revised estimates for 2026 and 2027 imply year-over-year growth of 27.7% and 14.1%, respectively.
Image Source: Zacks Investment Research
TPC’s Zacks Rank
Tutor Perini stock currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Tutor Perini Corporation (TPC): Free Stock Analysis Report
Fluor Corporation (FLR): Free Stock Analysis Report
MasTec, Inc. (MTZ): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).