

Bunge Global SA BG is benefiting from a stronger oilseed environment just as the Viterra combination expands its processing and origination reach. Second-quarter gains in soybean and softseed processing show the operating potential of the larger platform.
The trade-off is execution. Grain merchandising remains uneven, cash conversion is weak and returns on invested capital trail key benchmarks. With the stock also above its five-year median valuation, the investment case depends on whether processing resilience and synergies can translate into steadier cash returns.
Bunge’s Oilseed Engine Supports the Upside Case
Second-quarter 2026 adjusted EBIT in Soybean Processing and Refining rose 46.4% year over year to $445 million. Softseed Processing and Refining adjusted EBIT increased to $255 million from $14 million as results improved across regions.
The broader demand backdrop remains supportive, with population growth, rising incomes and biofuel use underpinning grain, oilseed and vegetable oil consumption. Archer-Daniels-Midland Company ADM also reported improved second-quarter oilseed crushing results in a constructive biofuels environment. Darling Ingredients Inc. DAR offers another biofuel-linked reference through its Diamond Green Diesel joint venture, which has capacity to produce more than 1.2 billion gallons annually.
Bunge Global SA Price and Consensus
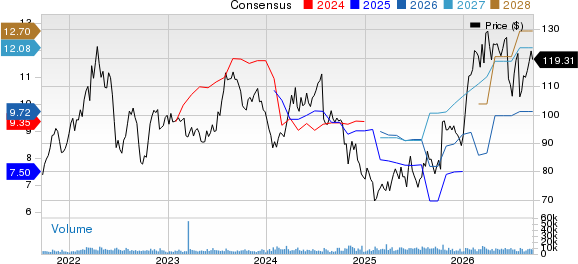
Bunge Global SA price-consensus-chart | Bunge Global SA Quote
BG’s Viterra Platform Broadens Regional Resilience
Viterra is adding more than scale. Bunge’s softseed processing volumes rose 79.3% in the second quarter, reflecting added production capacity in Argentina, Canada and Europe, while soybean volumes also benefited from greater capacity in Argentina.
Management increased its Viterra cost-synergy target to approximately $350 million and said progress was ahead of plan, giving the integration a clearer path to operating benefits.
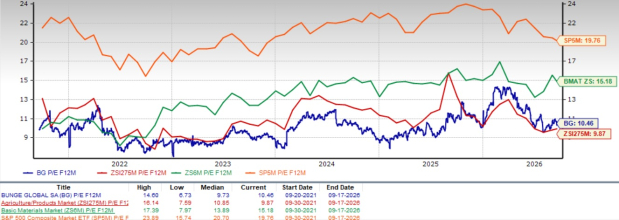
The Zacks Consensus Estimate for earnings for 2026 suggests year-over-year growth of 28.4%. The estimate for 2027 indicates growth of 24.3%.
Image Source: Zacks Investment Research
Bunge’s Valuation Leaves Less Room for Missteps
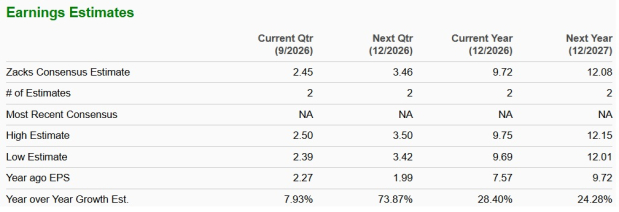
BG’s forward 12-month price-to-earnings ratio is 10.46, above its five-year median of 9.73 and the Zacks sub-industry’s 9.87.
The ratio remains below the Basic Materials sector’s 15.18 and the S&P 500’s 19.76. That valuation makes execution on synergies and earnings consistency more important.
Image Source: Zacks Investment Research
BG’s Cash Conversion and Returns Need Improvement
Trailing-12-month return on invested capital is 6.7%, below Bunge’s 10-year median of 7.8% and the industry median of 8.1%. Free cash flow conversion is negative 69.2%, even though that is better than the company median of negative 146.9%.
Cash demands remain meaningful. Net interest expense is expected at $620-$660 million for 2026, while capital expenditures are guided to $1.5-$1.7 billion. Integration costs and working-capital needs add to the burden as the company invests in growth and productivity.
Bunge’s Grain Weakness Keeps the Thesis Balanced
Grain Merchandising and Milling improved sequentially in the second quarter, helped by ocean freight, commercial services, global cotton and wheat milling. Those gains were partly offset by weaker global grain merchandising and sugar results.
Management lowered its full-year 2026 outlook for the segment. Persistent merchandising weakness could therefore limit earnings consistency even if soybean and softseed conditions remain constructive.
BG’s Style Profile Supports a Measured View
Bunge has meaningful operating support from oilseeds, added regional breadth from Viterra and a higher synergy target. Valuation, cash conversion, below-benchmark returns and grain volatility keep the investment case balanced rather than one-sided.
BG currently carries a Zacks Rank #3 (Hold), with a VGM Score of A and Value Score of B, Growth Score of B and Momentum Score of B. The favorable Style Scores complement the Rank rather than supersede it, while the #3 designation places BG in the middle of the short-term ranking scale. Continued earnings delivery, synergy capture and better cash realization remain important to the stock’s profile.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Bunge Global SA (BG): Free Stock Analysis Report
Archer Daniels Midland Company (ADM): Free Stock Analysis Report
Darling Ingredients Inc. (DAR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).