

Talen Energy Corporation TLN has a clearer cash-flow story as power demand rises and its contracted revenue base expands. Recent acquisitions and stronger PJM market conditions have broadened the company’s earnings base.
The trade-off is a sizable debt burden, continued wholesale-market exposure and execution risk around data-center projects. Valuation and estimate revisions add to the mixed setup, making cash-flow durability central to the investment case.
TLN’s Cash Flow Growth Supports the Bull Case
Trailing 12-month free cash flow conversion stands at 440%, well above Talen’s 235.5% trailing 12-month median. The unusually high rate can be influenced by earnings volatility and timing, so it should not be viewed as a steady-state level.
First-half 2026 adjusted free cash flow reached $562 million, compared with $9 million a year earlier. Talen also targets returning 70% of adjusted free cash flow to shareholders through repurchases, linking stronger cash generation to capital returns.
Talen’s Valuation Offers a Mixed Signal
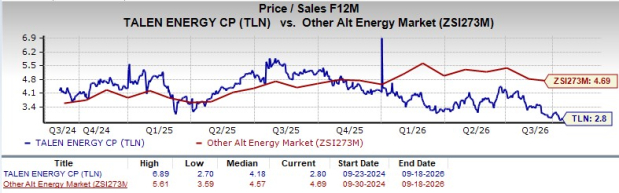
TLN trades at 2.80X forward 12-month sales per share, below its two-year median of 4.18X and the 4.69X Zacks sub-industry multiple. The stock nevertheless trades above the Zacks Oils-Energy sector’s 1.38X multiple.
Those comparisons do not point to a uniformly inexpensive stock. Investors still have to weigh the discount to Talen’s history and sub-industry against its premium to the sector, sizable leverage and execution risk.
TLN’s Debt Burden Limits Flexibility
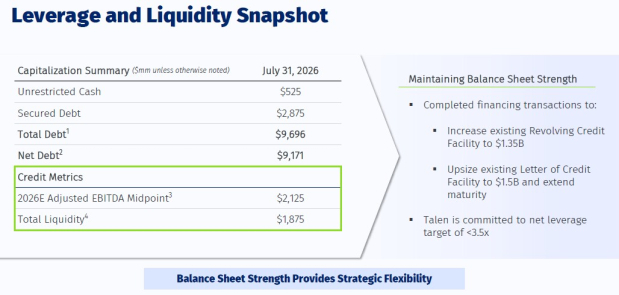
At June 30, 2026, total principal debt stood at about $9.7 billion. First-half interest expense and other finance charges reached $333 million, up from $136 million in the prior-year period.
Talen had about $1.9 billion of liquidity as of July 31 and is targeting net leverage below 3.5X net debt to adjusted EBITDA. Even so, weaker power-market conditions could reduce the cash available for acquisitions, development spending and repurchases.
Talen’s Contract Strategy Could Stabilize Cash Flow
Talen’s expanded agreement with Amazon Web Services calls for up to 1,920 MW of power from Susquehanna through 2042. Yet a meaningful portion of Talen’s earnings outlook still depends on PJM energy and capacity revenues, leaving results sensitive to power prices, fuel costs and market conditions.
Constellation Energy CEG said in August that it had signed an additional 920 MW of long-term nuclear power purchase agreements. Vistra Corp. VST has 20-year agreements with Meta supporting three nuclear plants in PJM. Both illustrate the broader push toward long-duration power contracting.
TLN’s Estimate Revisions Temper the Outlook
The Zacks Consensus Estimate calls for 2026 revenues of $4,549 million and earnings of $21.65 per share. For 2027, the consensus estimate rises to $5,190 million in revenues and $32.37 per share in earnings.
Near-term revisions are less supportive. The Zacks Consensus Estimate for 2026 earnings has moved 2.4% lower over the past four weeks, raising the importance of execution against Talen’s stronger longer-term cash-flow outlook.
TLN’s Scores Point to a Balanced View
Talen’s improving cash generation and expanding contracted revenue base are meaningful positives, but debt, wholesale exposure and project execution remain material offsets. The stock’s current signals therefore remain mixed rather than uniformly favorable.
TLN currently carries a Zacks Rank #3 (Hold), alongside a Value Score of C, Growth Score of C, Momentum Score of F and VGM Score of D. The Rank represents a neutral short-term signal, while the weaker Momentum and VGM readings provide less support than the A or B scores associated with stronger style characteristics.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Talen Energy Corporation (TLN): Free Stock Analysis Report
Constellation Energy Corporation (CEG): Free Stock Analysis Report
Vistra Corp. (VST): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).