

As Costco Wholesale Corporation COST prepares to unveil its fourth-quarter fiscal 2026 earnings results on Sept. 24, after the market closes, investors face an important decision: Should they buy, hold or sell the stock? With expectations and market conditions in focus, it is crucial to evaluate the key factors influencing Costco’s performance and whether the stock offers an attractive entry point.
Costco's strategic investments, customer-centric approach, merchandise initiatives and focus on membership growth have supported steady sales and earnings growth, positioning COST as a consumer defensive stock.
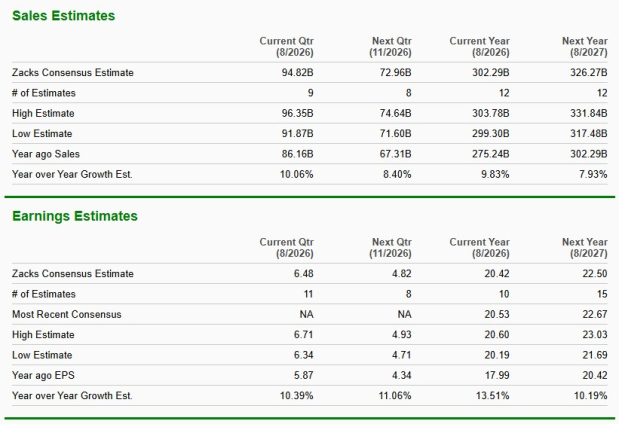
The Zacks Consensus Estimate for fourth-quarter revenues stands at $94.82 billion, calling for a 10.1% increase from the prior-year reported figure. On the earnings front, the consensus estimate has fallen by 3 cents to $6.48 per share over the past 30 days but still implies a 10.4% year-over-year jump.
Costco has a trailing four-quarter earnings surprise of 1%, on average. In the last reported quarter, this Issaquah, WA-based company beat the Zacks Consensus Estimate by a margin of 0.4%.
Image Source: Zacks Investment Research
What the Zacks Model Predicts About COST’s Q4 Earnings
As investors prepare for Costco's fourth-quarter announcement, the question looms regarding an earnings beat or miss. Our proven model does not conclusively predict an earnings beat for Costco this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. However, that’s not the case here. You can see the complete list of today’s Zacks #1 Rank stocks here.
Costco has a Zacks Rank #3 but an Earnings ESP of -0.19%. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
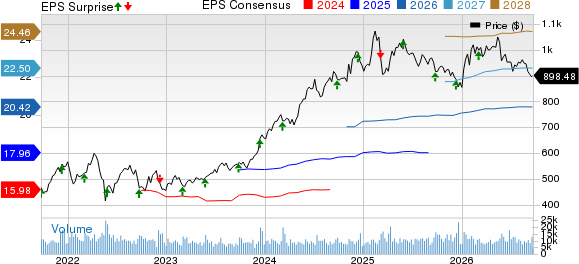
Costco Wholesale Corporation Price, Consensus and EPS Surprise
Costco Wholesale Corporation price-consensus-eps-surprise-chart | Costco Wholesale Corporation Quote
Costco: Key Factors at Play
Costco’s fourth-quarter performance is likely to have benefited from the continued strength of its value-focused merchandising model, which supports shopping frequency and basket expansion even in a cautious consumer environment. Members continued to respond well to the combination of quality, value and newness, with healthy demand likely across fresh foods, nonfoods and everyday essentials. Kirkland Signature also remained an important engagement driver through new product launches and attractive pricing, reinforcing traffic and member loyalty.
In its August sales report, Costco highlighted that net sales rose 11.3% year over year to $93.9 billion for the 16-week fourth quarter. Comparable sales increased 9.4% companywide. The United States posted a 10.7% comparable-sales gain, while Canada and Other International rose 5% and 7%, respectively.
The company’s expanding paid membership base and healthy growth in Executive memberships are also likely to have contributed to fourth-quarter performance. Executive members generally shop more frequently and spend more with Costco, supporting sales. Meanwhile, targeted digital communications and retention efforts are helping stabilize renewal trends, while management remained encouraged by new-member sign-ups. The continued shift toward Executive memberships, along with the benefit from the earlier fee increase, is likely to have supported membership-fee income.
Costco’s expanding digital capabilities and warehouse network may have provided further support to the top line. The company has been improving checkout speed, mobile-wallet functionality and digital membership access while expanding same-day delivery and personalized online recommendations. We note that digitally enabled comparable sales climbed 19.5% during the final quarter. At the same time, Costco remained focused on opening and relocating warehouses, remodeling high-volume locations and improving parking and gas-station capacity to enhance convenience and support higher volumes.
However, Costco may have faced pressure from an uncertain cost environment. Inflationary pressures stemming from higher input and component costs, along with tariff-related uncertainty, remained concerns. Combined with the company’s continued focus on maintaining attractive prices for members, these factors are likely to have weighed on margins in the fourth quarter.
Costco Stock Price Performance
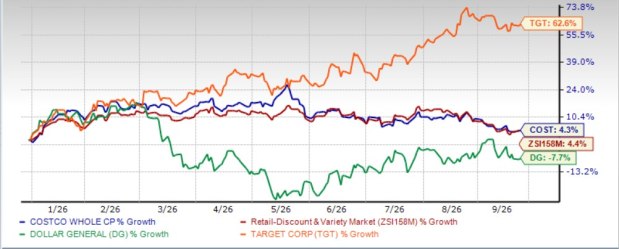
Costco, which competes with Dollar General Corporation DG and Target Corporation TGT, has seen its shares jump 4.3% in the year-to-date period compared with the industry’s rise of 4.4%. While shares of Target have surged 62.6%, those of Dollar General have fallen 7.7% in the aforementioned period.
Image Source: Zacks Investment Research
Does Costco Tick the Boxes for Value Investing?
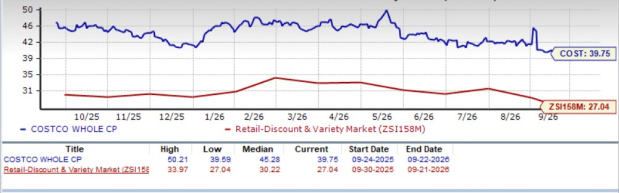
From a valuation standpoint, Costco currently trades at a premium relative to its industry peers. The company’s forward 12-month price-to-earnings (P/E) ratio is 39.75, higher than the industry average of 27.04 and the S&P 500’s 20.06. However, the stock is trading below its median P/E level of 45.28, observed over the past year.
Costco is trading at a premium to Target (with a forward 12-month P/E ratio of 16.30) and Dollar General (15.16).
Image Source: Zacks Investment Research
How to Play Costco Stock Ahead of Q4 Earnings?
Costco’s resilient sales trends, strong membership base, digital momentum and value proposition support the long-term story, but margin pressures, a premium valuation and the lack of a clear earnings-beat signal warrant some caution ahead of the release. Existing investors may consider holding their positions, while prospective investors may be better served waiting for greater clarity from the fourth-quarter results before initiating a position. Overall, the risk-reward setup suggests a measured approach rather than aggressive buying ahead of earnings.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Costco Wholesale Corporation (COST): Free Stock Analysis Report
Target Corporation (TGT): Free Stock Analysis Report
Dollar General Corporation (DG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).