

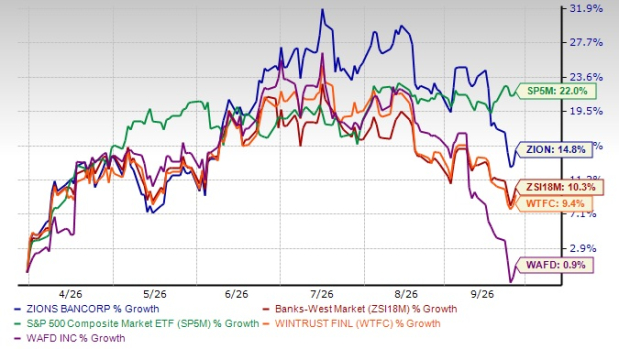
Shares of Zions Bancorporation ZION have gained 14.8% in the past six months, outperforming the industry’s 10.3% growth. Over the same period, the S&P 500 Index has rallied 22%.
If we compare the company’s price performance with its close peers like Wintrust Financial Corporation WTFC and WaFd, Inc. WAFD, it appears that ZION has outperformed both. In the past six months, WTFC and WAFD shares have rallied 9.4% and 0.9%, respectively.
6-Month Price Performance
Image Source: Zacks Investment Research
Does the ZION stock have more upside left despite recent strength in price? Let us find out by looking at its fundamentals and growth prospects.
Key Positives of Zions Bancorporation
Robust Top-Line Growth: Zions continues to benefit from consistent organic growth across its core lending and fee-based businesses. The company’s total revenues have seen a compound annual growth rate (CAGR) of 3.9% over the five years ended 2025, while loans and leases witnessed a 2.6% CAGR. Both metrics continued to improve in the first half of 2026.
Revenue Trend
Image Source: Zacks Investment Research
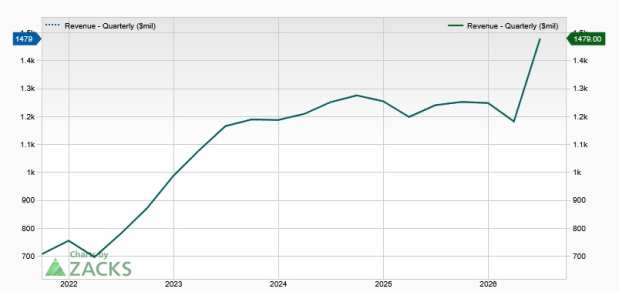
Looking ahead, a favorable earning-asset mix, and loan and deposit growth should support improvement in net interest income (NII), a primary revenue component. We project NII on a fully taxable-equivalent (FTE) basis to see a CAGR of 4.3% through 2028.
At the same time, Zions is working to expand fee income, particularly through its capital markets business. The acquisition of Basis Multifamily’s agency lending platform has strengthened the company’s multi-family origination and servicing capabilities, broadening its offerings to commercial real estate (CRE) clients, and creating fee-income opportunities. We expect these factors to support sustained top-line growth. Adjusted revenues are expected to increase 4% in 2026, 3.9% in 2027 and 5.8% in 2028.
Expanding Net Interest Margin (NIM): Zions continues to benefit from favorable funding dynamics and asset repricing. Following the Federal Reserve’s cumulative rate cuts over the past two years, deposit costs have reset lower, helping reduce funding costs and supporting margin expansion. Consequently, Zions’ NIM improved to 3.21% in 2025 from 3% in 2024, with the positive momentum continuing in the first half of 2026.
Going forward, continued deposit repricing, loan growth and the repricing of fixed-rate assets should support margins. An elevated interest-rate environment should also remain conducive to earning-asset yields. We project Zions’ NIM to improve to 3.27% in 2026, 3.30% in 2027 and 3.34% in 2028.
Improving Funding Mix: Zions continues to strengthen its funding profile through solid customer deposit growth and reduced reliance on wholesale borrowings. As of June 30, 2026, customer deposits, excluding brokered deposits, totaled $72.7 billion, up from $69.9 billion a year earlier, supported by focused deposit-gathering initiatives. Meanwhile, total borrowed funds declined 53% year over year mainly due to a reduction in short-term borrowings, including lower Federal Home Loan Bank advances.
The improvement has also strengthened Zions’ liquidity position. Total available liquidity reached $46.6 billion at June 30, 2026, up from $44.6 billion at 2025-end and equivalent to 135% of uninsured deposits. Importantly, available liquidity exceeded the company’s $34.4-billion uninsured deposits without requiring the sale of investment securities, providing a substantial cushion against potential funding stress.
Overall, the combination of growing core deposits, lower short-term wholesale funding dependence and ample contingent liquidity should enhance funding stability and balance-sheet flexibility, supporting Zions’ ability to fund loan growth and navigate changing market conditions.
Efficient Capital Distributions: Zions continues to demonstrate its commitment to returning excess capital to shareholders through dividends and share repurchases. In July 2026, the company raised its quarterly dividend 6.7%, following a 4.7% increase in 2025. Over the past five years, Zions has increased its dividend four times, translating into an annualized growth rate of 3.7%.
In May 2026, the company authorized up to $225 million of share buybacks for the final three quarters of 2026, after repurchasing $75 million in shares in the first quarter.
Supported by strong earnings generation, ample liquidity and a healthy capital position, Zions appears well-placed to sustain shareholder distributions while retaining sufficient flexibility to support balance-sheet growth.
What’s Hurting ZION’s Growth?
Rising Expenses: Zions’ elevated cost base remains a key concern as the company continues to invest in technology, marketing and franchise expansion. Despite declines in non-interest expenses in 2020 and 2024, the metric saw a 4.6% CAGR over 2020-2025, with the upward trend continuing in the first half of 2026 due to higher salaries and employee benefit costs. Technology spending accounted for roughly 13% of total non-interest expenses in 2025 and the first half of 2026.
Expense Trend
Image Source: Zacks Investment Research
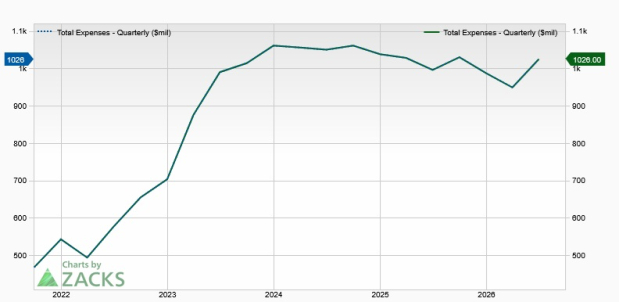
Continued investments in digital capabilities and growth initiatives are likely to keep expenses elevated and constrain operating leverage, particularly if revenue growth moderates. We expect total non-interest expenses to rise 4.7% in 2026, 3.6% in 2027 and 4.6% in 2028, potentially exerting pressure on Zions’ profitability.
Weak Asset Quality: Zions’ asset quality has weakened over the past few years, increasing its exposure to credit-cycle risks. Although provisions were relatively stable in 2025 and declined in 2024, they rose materially in 2022 and 2023 amid a softer operating backdrop. Net charge-offs (NCOs) recorded a CAGR of 17.9% over 2022-2025, highlighting increased credit losses.
While credit metrics improved in the first half of 2026, the company’s loan-loss outlook remains sensitive to macroeconomic conditions and commercial credit trends. We expect provisions to witness a CAGR of 13.8% over the next three years, which could weigh on earnings.
Analyst Sentiments for ZION
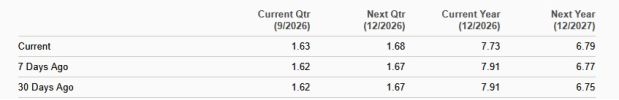
Analysts have a mixed stance toward Zions. Over the past 30 days, the Zacks Consensus Estimate for the company’s 2026 earnings has been revised 2.3% lower. The estimate for 2027 earnings has been revised marginally upward.
Earnings Estimate Revision
Image Source: Zacks Investment Research
Final Verdict on ZION Stock
Zions’ improving revenue trajectory, expanding NIM and stronger funding profile support its long-term prospects. Solid core deposit growth, reduced dependence on wholesale borrowings and ample liquidity provide balance-sheet flexibility, while the company’s capital position supports continued dividends and share repurchases.
However, rising operating expenses, weaker asset-quality trends and expectations for higher credit-loss provisions temper the near-term outlook. The recent downward revision to 2026 earnings estimates suggests limited catalysts for meaningful upside in the near term.
Given the balance between improving fundamentals and persistent cost and credit risks, existing investors may continue to hold on to ZION, while prospective investors may prefer to wait for a more attractive entry point.
Currently, Zions carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Zions Bancorporation, N.A. (ZION): Free Stock Analysis Report
Wintrust Financial Corporation (WTFC): Free Stock Analysis Report
WaFd, Inc. (WAFD): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).