

AMERISAFE, Inc. AMSF is benefiting from rising voluntary premiums, strong customer retention and disciplined underwriting. With a market cap of approximately $441 million, the company is a specialty provider of workers’ compensation insurance focused on small- to mid-sized employers in high-hazard industries, principally construction, trucking, logging and lumber, agriculture, services, manufacturing and maritime.
AMSF stock has lost about 30.6% over the past three months, underperforming the industry’s decline of 4.4% during the period. AMSF currently carries a Zacks Rank #3 (Hold) and a value score of B.
Where Do Estimates for AMSF Stand?
The Zacks Consensus Estimate for AMERISAFE’s 2026 earnings is pegged at $1.97 per share, which has remained stable over the past 60 days. The consensus mark for revenues is pegged at $342.6 million for 2026, indicating a 10.3% year-over-year rise. The company missed on earnings in three of the past four quarters and met once, delivering an average negative surprise of 7.8%.
AMERISAFE, Inc. Price, Consensus and EPS Surprise
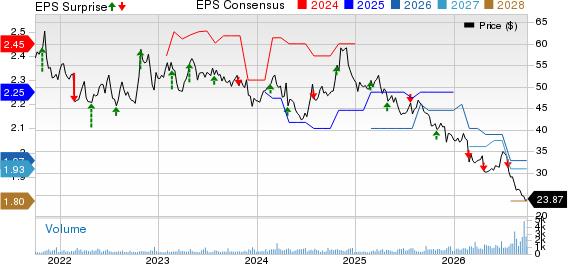
AMERISAFE, Inc. price-consensus-eps-surprise-chart | AMERISAFE, Inc. Quote
AMSF Stock’s Growth Drivers
AMERISAFE's growth continues to benefit from its specialized focus on high-hazard industries and disciplined underwriting. In the first half of 2026, gross premiums written increased 6.7% year over year to $174.5 million, while net premiums earned rose 10.2% to $152.3 million. The company also recorded its ninth consecutive quarter of premium growth, supported by renewal retention of more than 93% and a 5.7% increase in voluntary premiums.
AMERISAFE is following a measured growth strategy that emphasizes profitable business rather than premium growth at any cost. Its sales strategy focuses on working with the right agencies and choosing new customers that fit the company’s risk profile.Selective underwriting, healthy renewal retention and continued agency relationships provide a foundation for sustaining mid-single-digit growth even as competition intensifies.
Operational efficiency remains an important part of the growth story, although the first-half numbers were affected by a one-time expense. The underwriting expense ratio increased slightly to 30.8% from 30.6% a year ago, primarily due to an approximately $700,000 bad-debt write-off tied to an older account. Excluding such one-time pressure, the underlying cost structure remains supported by higher premium volumes. Favorable reserve development also remained a positive factor.
AMERISAFE's conservative investment portfolio and approximately $771 million in investments, cash and cash equivalents at quarter-end provide financial flexibility. Return on average equity was 18.1% in the first half of 2026, up from 17.5% a year earlier. The company repurchased $9.7 million worth of shares in the first six months of 2026. It also paid a quarterly cash dividend of 41 cents per share in the second quarter, up 5.1% from the year-ago period. These capital returns complement the company's focus on maintaining financial strength while supporting long-term growth.
Risks for AMSF Stock
There are some factors, however, that investors should keep an eye on.
AMERISAFE continues to face pressure from declining workers' compensation rates and rising claims costs. The first-half 2026 current accident-year loss ratio was 72%, while claim frequency increased from the prior accident year at six months. Favorable prior-year reserve development totaled $14.9 million in the first six months of 2026, down from $17.4 million a year earlier, providing less support to underwriting results.
Net investment income declined 1.6% to $13.1 million in the first six months of 2026 from $13.3 million a year earlier, primarily due to lower average investable assets following capital returned through dividends and share repurchases. Lower investment income could provide less support to overall earnings if the trend continues.
Key Picks
Some better-ranked stocks in the broader Finance space are Mercury General Corporation MCY, Heritage Insurance Holdings, Inc. HRTG and United Fire Group, Inc. UFCS, each sporting a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Mercury General’s 2026 earnings is pegged at $12.75 per share, indicating 61.4% year-over-year growth. MCY has witnessed two upward revisions in the past 60 days, with no movement in the opposite direction. It beat earnings estimates in each of the trailing four quarters, with the average surprise being 70.2%. The consensus estimate for 2026 revenues is pinned at $6.43 billion, implying 9.5% year-over-year growth.
The Zacks Consensus Estimate for Heritage Insurance’s 2026 earnings is pegged at $5.50 per share, which has witnessed two upward revisions in the past 60 days, with no movement in the opposite direction. HRTG beat earnings estimates in three of the trailing four quarters and missed once, with the average surprise being 81.5%. The consensus estimate for 2026 revenues is pinned at $860.96 million, implying 1.6% year-over-year growth.
The Zacks Consensus Estimate for United Fire Group’s 2026 earnings is pegged at $5.00 per share, which has witnessed one upward revision in the past 60 days, with no movement in the opposite direction. UFCS beat earnings estimates in each of the trailing four quarters, with the average surprise being 75.8%. The consensus estimate for 2026 revenues is pinned at $1.54 billion, implying 11% year-over-year growth.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
AMERISAFE, Inc. (AMSF): Free Stock Analysis Report
United Fire Group, Inc (UFCS): Free Stock Analysis Report
Mercury General Corporation (MCY): Free Stock Analysis Report
Heritage Insurance Holdings, Inc. (HRTG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).